❌

Reading view

France Is a Warning to California's Tax-the-Rich Crowd
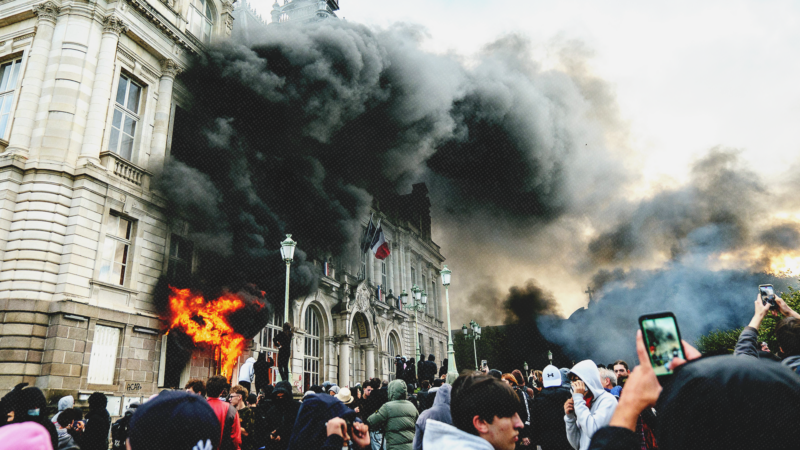
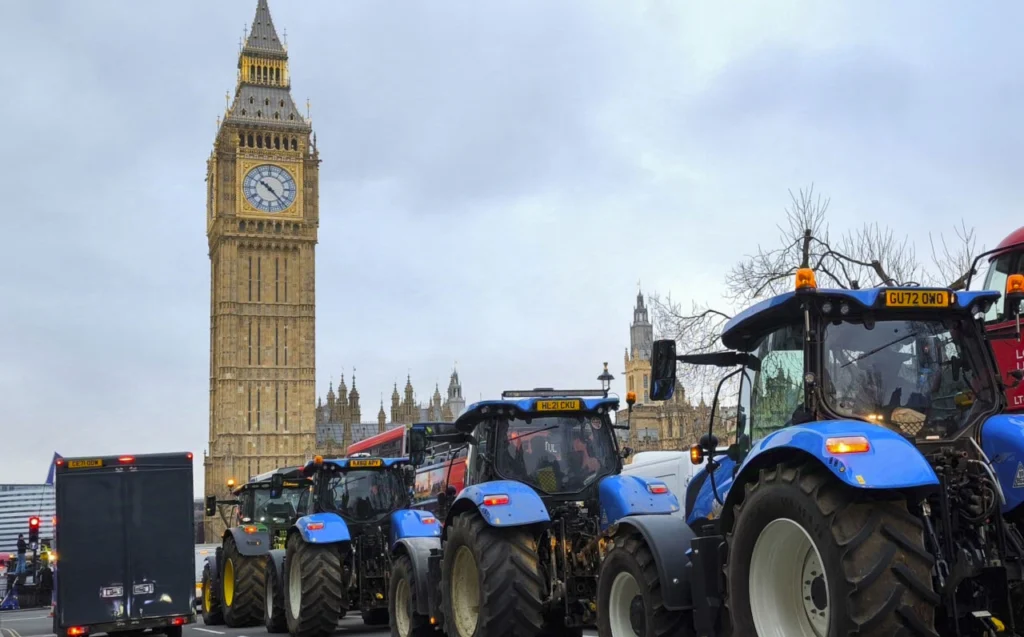
Protest in France | Elise Cabane/ZUMAPRESS/Newscom

French economist Gabriel Zucman has come to California bearing a familiar French solution to a fiscal problem: another tax.

Once based at the University of California, Berkeley, Zucman is back and campaigning for Proposition 40, which would impose an allegedly one-time 5 percent tax on the net worth of Californians worth more than $1 billion. Zucman, who coauthored the proposition, estimates that the tax could raise about $100 billion and claims that 90 percent of the proceeds would go to health care.

The California Legislative Analyst's office is far more cautious, saying it would raise only "tens of billions" and could cause a long-term loss of income-tax revenue as wealthy people leave the state with the companies they created.

I've written plenty about why wealth taxes are economically destructive, administratively nightmarish, and unlikely to achieve anything close to what their advocates promise. But Zucman's prescription is wrong for a more fundamental reason, as his (and my) native country shows: Raising taxes to fuel ever-larger demands for government spending is a recipe for disaster.

Unless you've been living in a remote cave recently, you've likely seen all the protests and destruction in France. But do you know why it's happening?

As another economist, Paul Krugman, rightly noted back in 2017, "France offers a social safety net beyond the wildest dreams of U.S. progressives: guaranteed high-quality health care for all, generous paid leave for new parents, universal pre-K, and much more."

For decades, France has answered any perceived desire with government spending, then responded to the resulting fiscal problem by seeking new revenue sources. Today, French government spending consumes roughly 58 percent of gross domestic product (GDP).

Krugman gloated that France wasn't suffering social collapse and speculated that it was due to all the spending. He certainly can't say that anymore. In fact, he is now worried that France may be on the precipice of a debt crisis. The truth is that France hasn't done well for some time, even when Krugman cheered its spending.

One of the groups in the street today, young people, has faced widespread unemployment for a long time. The youth unemployment rate in France (ages 15-24) has hovered between 17 percent and 27 percent since 2000. In the second quarter of 2026, it was 21.6 percent, against 14.8 percent in the Eurozone and 9.9 percent in the U.S.

French people also pay some of the highest taxes in the developed world, and they're not happy with the return. The government already takes more than 52 percent of the country's output in revenue, runs deficits exceeding 5 percent of GDP, and has accumulated debt approaching 120 percent of GDP. Nonetheless, French students complain that the government is shortchanging schools, while everyone sees that it is shortchanging its army and police.

The students aren't wrong to feel left out. At The Two Cents Substack, Hoover Institution scholar Hanno Lustig calculates that, between 1995 and 2024, spending on social protection and health (most of which benefits older people) rose from 53.1 percent to 58.7 percent of all French government spending. The share devoted to education, defense, and public order fell from 15.2 percent to 13.7 percent. Transportation fell from 5.3 percent to 3.8 percent.

In other words, France has built an enormous welfare state, much of it devoted to older citizens, while letting other state capacities and basic services fall apart. As transfers of wealth swallow a larger share of the budget, everything else gets squeezed.

That is the fiscal ratchet Californians should worry about when Zucman tells them Proposition 40 is necessary to "save" health care. Proponents claim Washington "cut" Medicaid, but that language is misleading. California's deficit started long before any Washington spending reductions. Besides, federal Medicaid spending isn't falling—not even close. The Congressional Budget Office estimates it will reach $708 billion in 2026, 8 percent more than in 2025. What Washington did in the 2025 budget reconciliation law was reduce Medicaid's future growth relative to previous projections, partly by changing eligibility and enrollment rules and financing arrangements.

This is how the ratchet works. Once the government projects a spending increase, anything less becomes a cut. And once Washington fails to finance the entire projected increase, Californians are told that Sacramento must backfill the missing money. And how should it do that? Conveniently, by creating an entirely new tax.

France has run this experiment for decades. It has an incredibly generous welfare state paid for with very high taxes; it's even tried a wealth tax and has a value-added tax, yet somehow it's never enough. Its welfare state has not eliminated scarcity. It has merely transferred the job of rationing scarce resources to politicians.

Zucman looks at California and sees hundreds of billions of dollars of private wealth waiting to solve a public finance problem. Californians should look across the Atlantic and ask a different question: What happens after politicians decide that every spending adjustment can be delayed until tomorrow by finding another pot of private wealth?

France should not be sending California tax advice. It should be sending a warning.

COPYRIGHT 2026 CREATORS.COM

The post France Is a Warning to California's Tax-the-Rich Crowd appeared first on Reason Magazine.
  •  

Trump administration abandons appeals in fight over student loan forgiveness program

The Trump administration has abandoned its goal to reform the Public Service Loan Forgiveness (PSLF) program, dropping a legal fight over the changes this week.  The Education Department wanted to place limits on who could qualify for PSLF, which gives student loan forgiveness to people in government and nonprofit jobs after 10 years of payments. It…

  •  

UK Public Debt Tops £3 Trillion for First Time

UK public debt crossed the £3 trillion mark for the first time at the end of September 2026, the National Statistics Office reported on Wednesday, October 21.


The accumulated public sector liabilities stood at £3.005 trillion, equivalent to €3.57 trillion, according to the provisional estimate released by the National Statistics Office. The figure represented 94 percent of UK gross domestic product and marked a historic high, the agency reported.

The balance grew by £91.7 billion compared with the level recorded twelve months earlier, about €109.074 billion, according to the provisional estimate.

RELATED: U.K. Slashes International Aid Budget by 56% to Fund Defense

Despite the nominal record, the weight of the liabilities on the economy as a whole fell by seven tenths compared with the 2025 level, the agency reported. The agency recalled that net debt exceeded £2 trillion in June 2020, during the COVID-19 pandemic, and had surpassed £1 trillion in February 2010, following the global financial crisis.

September public borrowing amounted to £24.5 billion, or €29.142 billion, and was the second highest recorded for that month, according to the National Statistics Office. Only the September 2020 figure, unadjusted for inflation, was higher. Compared with the previous year, the imbalance increased by £1.8 billion, or 7.7 percent, because spending growth outpaced income growth, the agency reported.

Britain’s national debt has climbed above £3tn for the first time, underlining the pressure on the public finances before John Healey’s maiden Budget next week

🔗 https://t.co/xKIQKqOhib pic.twitter.com/ExKxQ7hI95

— The Telegraph (@Telegraph) October 21, 2026

Central government debt interest reached £10.9 billion in September, the highest figure recorded in the ninth month of the year since monthly records began in 1997, according to the National Statistics Office.

Annual inflation stood at 3.5 percent in September, four tenths above the August figure and the largest increase since October 2025, according to the National Statistics Office. The price of goods rose 3.2 percent year on year, compared with 2.7 percent in August, while services became 3.7 percent more expensive. Core inflation, which excludes energy, food, alcohol and tobacco, advanced to 2.8 percent, two tenths more than in August.

  •  

Takaichi’s next vote is in the bond market

Sanae Takaichi has done something few Japanese leaders manage. She’s reached her first anniversary in office more popular than her predecessors, and she looks well placed to keep the job. In a country that has burned through five prime ministers in a decade, this counts for a lot. Popularity, though, is only one of two […]

The post Takaichi’s next vote is in the bond market appeared first on Asia Times.

  •  

Student-loan borrowers win as Trump drops legal battle to narrow a major forgiveness program for public servants

Donald Trump
The Trump administration agreed to drop its appeal of a ruling that blocked its plan to limit Public Service Loan Forgiveness.

Anna Moneymaker/Getty Images

  • The Trump administration agreed to drop its appeal of a Public Service Loan Forgiveness ruling.
  • The ruling blocked Trump's plan to limit PSLF eligibility from taking effect.
  • An advocacy group said it's a victory for borrowers pursuing PSLF.

Student-loan borrowers pursuing a major forgiveness program got a rare legal win.

On Wednesday, the Trump administration agreed to drop two of its appeals of a June ruling that had blocked its plan to narrow eligibility for the Public Service Loan Forgiveness program, which forgives student debt for government and nonprofit workers after 10 years.

The Education Department intended to implement a plan on July 1 to exclude employers from PSLF who did not align with the administration's definition of "public service," listing actions like assisting with gender-affirming care or 'acts of terrorism.

A judge ruled at the end of June that the plan was unlawful and would not take effect. This followed a series of lawsuits filed by advocacy groups and nonprofits, including Student Defense, which said the education secretary did not have the authority to roll out those changes.

The administration appealed the ruling at the end of August. With the appeal set to be dismissed, borrowers will not face any immediate changes to PSLF. Another appeal in a separate PSLF lawsuit is still pending.

"The Trump administration's attempt to weaponize public service loan forgiveness against organizations it disagrees with was anti-democratic and unlawful from the start," Dan Zibel, chief counsel at Student Defense, said in a statement. "This is a significant victory for millions of Americans who have dedicated their careers to public service."

The Education Department did not immediately respond to a request for comment from Business Insider.

Undersecretary of Education Nicholas Kent previously said that the rule had been intended to "ensure federal benefits go to our Nation's teachers, first responders, and civil servants who tirelessly serve their communities."

Borrowers pursuing PSLF are still facing challenges. The Education Department recently removed some borrowers' payments toward forgiveness, citing Biden-era coding errors. Others have reported delays getting their payments counted toward relief, leaving them in limbo.

A department spokesperson previously said that the agency "remains committed to ensuring that every qualifying payment is properly credited to a borrower's account."

Have a story to share about student loans? Contact this reporter at asheffey@businessinsider.com.

Read the original article on Business Insider

  •  
  •  

Elon Musk says 'AI and robots' are the only way to solve America's debt burden

Elon Musk in Oval Office
Elon Musk said his stint at DOGE led him to this conclusion.

Kevin Dietsch/Getty Images

  • Elon Musk said that "AI and robots" are the key to fixing America's national debt.
  • On a podcast, Musk said it would be "impossible" to tackle any other way.
  • He predicted "digital superintelligence" could boost the output of goods and services by 20% to 30%.

Elon Musk said artificial intelligence and robots — not government spending cuts — are the only way to fix the US national debt problem.

Speaking on a newly released episode of author Walter Isaacson's "The Builders" podcast, Musk said his 130-day stint as a special government employee in the second Trump administration led him to that view.

Musk, the world's richest person, served as the de facto leader of the White House DOGE office from January to May 2025, where he sought to slash federal spending.

"I came to the conclusion that the only way we're going to solve the national debt is with AI and robots. We're not going to solve it by trying to save our way there," Musk told Isaacson, calling the latter "impossible."

The US national debt load hit a record $40 trillion in August and has continued to climb, according to Treasury data.

"Maybe if the president made that his, you know, primary goal, we could do that, but the problem is if you try to solve the deficit and stop wasteful spending, you make a lot of enemies in that situation," Musk said.

The Tesla and SpaceX CEO said political leaders in Washington are mostly unwilling to rein in federal spending enough to significantly shrink the deficit.

"The appetite is not there, and it's not just at the presidency. The appetite is not there at the presidency, the House, the Senate, or the judiciary," Musk said.

He added, "Basically, no one in authority in the government whatsoever, really, with maybe a few rare exceptions of like the Rand Pauls of the world type of thing, actually wants to reduce spending — no, they don't."

Musk estimated that "digital superintelligence" could boost the global output of goods and services by 20% to 30% — an increase he estimated could add roughly $30 trillion a year to the world economy.

"If you have robots and you get to space and can do a mass driver on the moon, then you can get to, I think, potentially a million times the size of the Earth economy," he said.

This could ultimately make money "irrelevant," Musk said.

"There will still be currency, but I think currency will be measured in fundamental physics metrics like wattage and tonnage, mass and energy," he said, predicting, "Conventional currency will not matter."

During the interview, Musk also reflected on his chainsaw-wielding time with the Department of Government Efficiency, admitting he got "carried away."

"I think I should have been more in the background and probably only had it last for a month or two, because at that point you've sort of seen most of what there is to see," Musk told Isaacson.

Musk said he should have left and "focused on AI a little sooner than I did."

Read the original article on Business Insider

  •  

Student-loan borrowers are waiting for 'legally required' debt relief that Trump isn't delivering, new legal filing says

President Donald Trump
A new legal filing said that the Trump administration is failing its obligation to process debt relief for defrauded student-loan borrowers.

Kevin Dietsch/Getty Images

  • Student-loan borrowers are still waiting for the relief they're entitled to through a settlement, a new legal filing said.
  • A borrower advocacy group is asking a court to enforce compliance with the relief settlement.
  • The Education Department said it disagrees with the motion and is working to enact relief.

Student-loan borrowers are legally entitled to debt relief — but they're still waiting for it to arrive, an advocacy group contends in a new court filing.

The Project on Predatory Student Lending — a borrower advocacy group — filed a new motion in its years-long lawsuit to get relief for thousands of defrauded borrowers.

In July, a federal court denied the Trump administration's request to delay relief under the Sweet v. McMahon settlement, which has provided $23 billion in relief to over 500,000 borrowers. Now, PPSL says that over 1,000 members of the settlement class are still waiting for loan discharges or refunds that the Education Department "was legally required to provide by deadlines that have long since passed."

The group filed a motion asking the court to enforce the settlement and hold the department in contempt, in order to compel compliance with the settlement terms and process relief within the set deadlines. Specifically, the motion asks the department to resume weekly meetings with the plaintiffs' counsel for status updates on the processing of the relief, and asks the court to enforce penalties if the department does not comply.

The Education Department said in its response that the motions are "baseless."

Additionally, a declaration from the department's ombudsman said that borrowers still awaiting refunds are not due to department failure, but rather, that those borrowers' accounts "warranted further review."

"Although it has taken staff some time to understand all of the complexities, the current staff have been reviewing and resolving Sweet complaints since approximately April 2024 with some staff added in 2025," the ombudsman said. "They are all incredibly well-versed in Sweet complaint resolution."

A public hearing in the case is scheduled for November 5.

Student-loan borrowers first filed a lawsuit against the department in 2019, accusing it of failing to process their borrower defense to repayment applications — claims borrowers can file if they believe they were defrauded. If approved, their student debt from the school would be wiped out.

A settlement in the case was reached under the Biden administration in 2022, and while batches of borrowers have received relief, PPSL said that others who qualify are still waiting.

Have a story to share about student loans? Contact this reporter at asheffey@businessinsider.com.

Read the original article on Business Insider

  •  

Student-loan borrowers and parents are facing spiking payments and fewer options for relief, a new report says

President Donald Trump
Student-loan borrowers are facing higher monthly bills under President Donald Trump's repayment overhaul, a new report says.

Kent NISHIMURA / AFP via Getty Images

  • Student-loan borrowers and parents are facing payment surges, a new report said.
  • Borrowers could see an average annual increase of over $2,000 due to Trump's repayment changes.
  • The financial strain puts borrowers at greater risk of defaulting on their debt.

A big financial hit could be coming for student-loan borrowers, a new report says.

On Monday, the Center for American Progress, a left-leaning think tank, released a report showing how President Donald Trump's student-loan repayment overhaul will affect bills and relief for millions of borrowers. The think tank shared the report exclusively with Business Insider.

The student-loan changes, signed into law in Trump's "big beautiful" spending legislation, took effect July 1 and included new income-driven repayment plans and borrowing caps. Borrowers moving from the Biden-era SAVE plan to the new Repayment Assistance Plan, or RAP, could see their student-loan bills increase by $2,163 annually on average, the report said.

For example, the report said a typical borrower with a bachelor's degree with earnings of about $68,615 annually would see their monthly payments increase from $136 to $343. That's a total increase of $2,482 annually, on average.

The findings are based on income data from the US Census Bureau's American Community Survey and the Survey of Income and Program Participation, adjusted for inflation using the consumer price index. CAP then estimated how much typical borrowers with different educational circumstances would have to pay under SAVE and RAP based on those plans' rules.

The SAVE plan allowed for lower payments and a shorter timeline to debt relief. The Trump administration eliminated the plan and is requiring borrowers to transition to a new plan, recommending RAP as an option. While the benefits of RAP include waiving unpaid monthly interest, borrowers must make on-time payments — meaning no grace period — to receive them.

Sara Partridge, associate director of higher education at CAP and a coauthor on the report, told Business Insider that while SAVE allowed zero-dollar monthly payments, RAP's minimum payment is $10. "Those $0 payments were a really important protection that many borrowers will struggle without," Partridge said.

For example, per the report, a single borrower without dependents earning $35,000 annually in 2026 would have $0 payments under SAVE. Under RAP, they would owe $88 monthly.

She added that these changes come "at a time when there is high inflation, stagnating wages, and people are generally feeling financially strained," making it more difficult for borrowers to fit a higher monthly bill into their budgets.

Parents and borrowers face increased risk of default

Trump's student-loan repayment overhaul also limits parents' options. Previously, the parent PLUS program allowed parents to borrow up to the full cost of attendance for their kids. Now, parents who took out loans after July 1, 2026, face a lifetime borrowing cap of $65,000. Those new parent borrowers will be limited to the costlier tiered standard repayment plan and will lose access to the income-contingent repayment plan.

Along with higher payments, the repayment overhaul also eliminates all borrowers' ability to defer their loan payments in the event of economic hardship or unemployment, beginning next year.

"This is a tool that borrowers relied on to help them out during times when they were struggling," Partridge said. "And without those options, borrowers may be more likely to become delinquent on their loans or eventually default, which we know can come with some devastating consequences."

Defaulting on federal student loans, which typically occurs after 270 days of nonpayment, can lead to wage garnishment and the seizure of federal benefits, such as Social Security. The most recent data from Federal Student Aid showed that 9.3 million borrowers are in default, with another 1.5 million at risk of defaulting in the next six months.

The Trump administration has said that its changes are intended to simplify a complex repayment system and curb excessive borrowing.

Nicholas Kent, the department's undersecretary, said in a statement that the changes "will ensure students continue to have the access that they need for federal student loans, while helping prevent borrowers from taking on unmanageable debt levels that they may never be able to repay."

Have a story to share about student loans? Contact this reporter at asheffey@businessinsider.com.

Read the original article on Business Insider

  •  

He retired after he got notified of student-loan forgiveness. Then his payments came back.

Photo collage featuring  Donald Knierim and Private Student Loan elements.
Donald Knierim is fighting to get his Public Service Loan Forgiveness restored.

Vanessa Valadez for BI

Donald Knierim planned his retirement around student-loan forgiveness.

He spent most of his career designing financial data systems for major companies. At the age of 60, he took a pay cut and moved to the public sector, working for Metra, Chicago's commuter railway. His primary draw to the job was lower stress, and an added bonus was that it qualified for the Public Service Loan Forgiveness program, which erases student debt for government and nonprofit workers after 10 years.

Knierim had a $62,000 balance remaining on the student loans he took out to send his kids to college. If all went according to plan, a decade at Metra would wipe that clean.

In November 2025, the now-71-year-old logged on to his Federal Student Aid dashboard. It read "Congratulations! You've satisfied your obligation, and no additional payments are required for this loan." That tracked — Knierim said he had never missed a payment, always verifying that his payments were counting toward his forgiveness progress. So he put in his notice and retired.

Donald Knierim
Knierim retired after thinking his student-loan payments were done.

Vanessa Valadez for BI

Months later, he received an update: 15 payments that had previously counted toward forgiveness were changed to "non-qualifying." The notice said his payments were below the amount required under his income-driven repayment plan, but did not specify the proper amount. That means he has at least another year and a half of payments — about $470 monthly — to achieve PSLF.

"If I have to restore that payment, it's going to put my wife and me in a bad situation," Knierim said. "We're too tight in retirement to be shelling out money for stuff that we can't afford."

Since 2023, Business Insider has heard from student-loan borrowers whose loan forgiveness was rescinded. Over the past few months, issues with PSLF have become more widespread, with borrowers reporting challenges in receiving accurate payment counts. Some had their payments toward forgiveness removed after the Department of Education said it was correcting accounts following Biden-era coding errors.

An Education Department spokesperson said that the agency "remains committed to ensuring that every qualifying payment is properly credited to a borrower's account."

Donald Knierim
For years, Knierim said he made sure his payments were counting toward his forgiveness progress.

Vanessa Valadez for BI

Knierim said that even if he could land a new public service job, he wouldn't be able to take it. Caring for his wife, who is facing serious health issues, is a full-time job. He has reached out to his servicer and filed multiple complaints with Federal Student Aid, requesting his payments to be returned to a qualifying status. Meanwhile, he has not made the new payments his servicer said were due, which has lowered his credit score by more than 200 points. He recently received a notice that his account is delinquent and at risk of default, putting him at risk of seizure of federal benefits, like the Social Security he relies on to stay afloat.

Now, he's asking for the initial communication he received from his student-loan servicer to be honored.

"I thought I was done, they gave me that notification that I was done, and then they clawed it back," Knierim said. "I didn't know where that came from, or what to do."

An error-riddled student-loan forgiveness program

There are a few reasons a borrower might get their PSLF notices rescinded. An internal Education Department memo from 2023, reviewed by Business Insider, said that servicer MOHELA erroneously discharged loans for 64 student-loan borrowers "due to inadequate staff training." The memo recommended that MOHELA send notices to affected borrowers explaining what had happened.

In 2023, one borrower received a notice that his loans had been discharged under PSLF. Nine months later, he received a notice that the forgiveness was a mistake, and his payments were restarted. Between those two notices, the borrower said he had bought a home and paid for his son's preschool. The reversal required him to reconfigure his family's budget.

Donald Knierim
Some student-loan borrowers have seen their PSLF payments rescinded, which the Trump administration attributed to Biden-era errors.

Vanessa Valadez for BI

More recently, the Trump administration removed some PSLF borrowers' qualifying payments, with the Education Department citing Biden-era code errors that "resulted in inaccurate payment counts for some borrowers."

Bonnie Latrielle, an official in the Education Department's Federal Student Aid office under former President Joe Biden, said PSLF errors often arise during communication between the Education Department and servicers; servicers report qualifying PSLF payments to the department, and the department matches that information with a borrower's employment records to determine if the borrower is PSLF eligible.

"Those are all things that are outside of the borrower's control," Latrielle said.

Knierim said his servicer told him that some of the payments he made toward the Temporary Expanded PSLF program — a Biden-era program that allowed payments previously deemed ineligible to count toward forgiveness — did not qualify because they were below the required amount. He said he did not receive any further explanation as to why his payment amounts did not qualify, despite following his servicer's guidance on reaching forgiveness.

"I have a flawless payment history," Knierim said. "I have never missed a payment, and I paid what they told me to pay."

From relief to repayment

The Education Department has a "stated policy of holding borrowers harmless," Latrielle said, and borrowers have the right to submit complaints to the department's ombudsman if they have been harmed by their servicer.

However, amid staffing cuts in the department as part of the Trump administration's plan to dismantle the agency, it has stopped monitoring servicer performance and routine borrower complaints. Latrielle said a growing number of states have student-loan ombudsmen and a borrower bill of rights, offering resources and protections for borrowers within the state. Borrowers can also file lawsuits against their servicer if it violates state law, Latreille said.

Knierim, with the help of his daughter, an attorney, sent a letter to his servicer offering to pay the shortfall in his monthly payments. He said the letter was never acknowledged. He does not want to resume payments or switch repayment plans if doing so could further complicate his progress toward forgiveness. Still, his account is also inching toward default, and finding a resolution is becoming more urgent.

Donald Knierim
Knierim is hoping that his forgiveness denial will be reconsidered so he can continue retirement without a student-loan payment burden.

Vanessa Valadez for BI

In September, eight state student-loan ombudsman offices, including those from Massachusetts, California, and Illinois, where Knierim lives, sent a letter to the Education Department and congressional leaders calling for stronger oversight of PSLF. They cited an example of a public service worker who had more than the required number of payments for forgiveness, but his progress tracker was reset to zero.

"Borrowers have received no clear explanations for individual reductions, making it difficult to verify the accuracy of the new totals, even though these retroactive adjustments can delay forgiveness by years," the letter said.

Knierim is still searching for clarity on where his student-loan forgiveness stands. He said he recently spoke with a Federal Student Aid representative who told him that a "reconsideration request" for the payment denial is in progress. That process could take up to two months, Knierim said he was told, and in the meantime, he's seeking to put his loans on forbearance until he gets a final answer.

"I kept getting different answers," Knierim said. "I can't go back and work. I have no recourse here."

Have a story to share about student loans? Contact this reporter at asheffey@businessinsider.com.

Read the original article on Business Insider
  •  

Weak Links Start to Show in A.I. Borrowing

Debt trouble at CoreWeave, Oracle and SoftBank raises questions about whether there are broader problems with the data center build-out.

© Ivan Pierre Aguirre for The New York Times

The site where Project Jupiter, an artificial intelligence data center, is under construction in Santa Teresa, N.M. Oracle is having trouble obtaining state permits for its energy needs.
  •  

How Many Economists Does it Take to Wreck an Economy?

The UK economy will grow 1.3% in 2026, according to the IMF. But will it really, asks David Craig. With unemployment rising, it's just an illusion of out-of-control borrowing. But try getting an economist to admit it.

The post How Many Economists Does it Take to Wreck an Economy? appeared first on The Daily Sceptic.

  •  

The Federal Government Collected $5.4 Trillion. It Still Can't Pay Its Bills.

U.S. Capitol in red as money falls around it | Illustration: Nikolai Sorokin/Songquan Deng/Dreamstime

The federal government just closed fiscal year 2026 with a deficit of nearly $2 trillion, according to figures the Congressional Budget Office (CBO) released last Thursday. Only the two pandemic years of 2020 and 2021 were worse. Today, though, there is no recession and no emergency. These enormous budget deficits are the new normal.

The usual response to a deficit warning is that the government just needs more money. It doesn't. Thanks to the remarkable strength of the private sector, federal revenue rose by 3 percent, to more than $5.4 trillion, over the fiscal year. But spending rose by 6 percent, reaching $7.4 trillion.

Some will blame the Supreme Court for striking down most of President Donald Trump's tariffs and forcing the government to issue refunds. But even if Washington had kept the $130 billion in illegal levies, it would cover less than one-tenth of the gap. Tariffs were never a serious revenue source at our insanely high level of spending.

Look at where the money went. Spending on the three main entitlement programs—Social Security, Medicare and Medicaid—grew by 7 percent. That's faster than total spending growth. Defense grew by 5 percent. Interest on the debt rose by 11 percent, exceeding $1.1 trillion. That last figure is the bill for every earlier year of borrowing—years when Washington was sending clear signals that it isn't serious about fiscal responsibility.

If you want to see where such irresponsibility can lead, look at France. The country that big spenders from Paul Krugman to Sen. Bernie Sanders (I–Vt.) have cited as proof that big government is viable and full of upsides is now on the brink of a serious crisis. France's debt equals 120 percent of its gross domestic product (GDP), and interest payments are rising quickly. Slow growth and social unrest aren't helping.

The U.S., of course, has some advantages that France doesn't, largely because we're a country of innovators with a private sector unmatched at creating wealth. Nonetheless, debt that is swelling out of control should still worry us. First, the same anti-wealth and anti-growth forces that brought France to where it is now are gaining popularity here. Second, we too will see debt reach 120 percent of GDP in a few years, and our interest payments are already consuming an alarming share of resources.

A wise Congress would put us on safer footing if only because debt raises interest rates for everyone, from homebuyers to small businesses. This operates as a drag on growth, and hence on wages. In other words, controlling debt should be part of an affordability agenda in the same way as streamlining regulation.

When legislators decide to take affordability seriously, I recommend looking at a September Advancing American Freedom (AAF) report on this topic. Its section on fiscal restraint offers a useful menu of reforms, including targeting the programs that most drive the debt.

Start with Social Security. Under current law, benefits will be cut by roughly 20 percent when the program's trust fund runs dry in the early 2030s. Nobody believes Congress will actually let that happen, but we'd better hope its answer isn't to double down by borrowing the difference between payroll taxes and benefits.

Nor are tax increases an option. The payroll tax meant to fund entitlements is now 12.4 percent of wages. It began at 2 percent when Social Security was first rolled out. It is also the most burdensome tax for many Americans. Enough already. The fixes AAF fellow Rachel Greszler proposes are worth considering: Index the retirement age to life expectancy, use an accurate inflation measure for cost-of-living adjustments, and move gradually toward a flat universal benefit that protects lower-income retirees while ending Social Security's de facto welfare for the wealthiest.

Next is Medicare. More than 40 percent of its financing already comes from general revenue rather than from payroll taxes. The report recommends converting the program to premium support, giving beneficiaries a fixed contribution to spend on traditional Medicare or on competing private plans. It would also raise the eligibility age to 67, matching Social Security, and trim subsidies for well-off seniors. That's a start.

As for Medicaid, the problem is one of pricing. And yet competition based on price—the best cost-control tool—has never been seriously tried. Washington covers 90 percent of the cost of states' expanded Medicaid programs for adults. A state can buy a dollar of spending with just a dime of its own money. Changing the states' incentives would be key here. Implementing risk-adjusted per-capita caps, through which the federal government would give states a fixed amount per enrollee, would do just that. States would pay for their own inefficiencies or would be able to use every dollar they save by becoming more efficient.

The same logic supports returning more welfare programs to states, starting with the federal share of the Supplemental Nutrition Assistance Program. State governments have to balance their budgets in some form.

None of these reforms are painless. But the alternatives will prove far more painful. The U.S. will either continue paying a slow, unlegislated tax called inflation or face a fast, ugly fiscal crisis when bond buyers stop giving Washington the benefit of the doubt.

COPYRIGHT 2026 CREATORS.COM

The post The Federal Government Collected $5.4 Trillion. It Still Can't Pay Its Bills. appeared first on Reason Magazine.

  •  

IMF warns of debt-fueled AI spending as bubble fears grow

The International Monetary Fund warned Tuesday that the global economy faces serious risks from Big Tech firms taking on massive debt to fund the buildout of artificial intelligence data centers worldwide. The IMF’s latest Global Financial Stability Report outlines a number of risks to economic growth in the coming years, including a reliance on AI […]

The post IMF warns of debt-fueled AI spending as bubble fears grow appeared first on Asia Times.

  •  

France’s Debt Crisis Deepens as Eurozone Ministers Demand Credible Budget

France faces growing pressure from eurozone governments and financial markets to secure its 2027 budget as borrowing costs climb towards levels not seen for more than two decades, raising questions about Paris’s ability to restore control over its public finances.

France is coming under increasingly direct pressure from its eurozone partners to resolve the political dispute surrounding its 2027 budget, with European finance ministers warning that continued uncertainty threatens confidence in the country’s public finances.

The warning follows a sharp increase in French government borrowing costs. Yields on ten-year sovereign bonds have risen by nearly 80 basis points since September, reaching levels last recorded in 2002. Investors are demanding higher returns to finance a government whose debt continues to increase while its capacity to impose spending restraint remains constrained by parliamentary divisions.

At the Eurogroup’s October discussions, finance ministers and European Central Bank officials pressed Paris to demonstrate that it can adopt a credible budget and comply with its commitments under the EU’s fiscal framework.

France’s difficulties have implications beyond its domestic politics. As the eurozone’s second-largest economy, France occupies a position fundamentally different from smaller countries that experienced sovereign debt crises during the previous decade.

Borrowing costs expose political weakness

The French government expects to borrow approximately €340 billion in 2027, making continued access to financial markets at sustainable rates an essential element of its fiscal strategy.

That financing requirement reflects both the need to cover the annual deficit and to refinance existing debt as government securities mature.

France’s public debt is already approaching 120 per cent of gross domestic product. As EU Today previously reported, official projections indicated that the debt ratio could reach 121.7 per cent in 2027, up from 115.7 per cent at the end of 2025.

The latest increase in yields adds another complication. Higher interest costs do not affect the entire stock of debt immediately because much of it was issued at earlier rates. They do, however, increase the cost of new borrowing and refinancing, progressively reducing the money available for other government commitments.

France also faces a difficult political timetable. With the presidential election approaching in 2027, parties are reluctant to accept measures involving spending reductions, higher taxation or changes to public services.

Prime Minister Sébastien Lecornu’s government has been attempting to reduce the deficit from an estimated 5.4 per cent of GDP in 2026 towards five per cent. Even that objective remains substantially above the EU’s three per cent reference value.

Brussels has limited room to compromise

Economic Commissioner Valdis Dombrovskis has emphasised the importance of predictable fiscal policy and credible deficit reduction.

France is already subject to the EU’s excessive deficit procedure, under which member states must demonstrate progress towards agreed fiscal objectives.

The reformed European fiscal framework permits certain deviations from expenditure commitments in exceptional circumstances, but it does not provide an unrestricted exemption from debt sustainability requirements.

Paris therefore faces a double constraint. It must convince domestic political forces to support a budget while demonstrating to Brussels that its spending plans are sufficiently credible.

The danger is not necessarily an immediate financing crisis. France retains a large, diversified economy, deep financial markets and substantial tax-raising capacity.

The more immediate risk is that prolonged political deadlock produces progressively higher borrowing costs, making future fiscal adjustments more expensive.

Why the ECB cannot simply intervene

The European Central Bank has instruments designed to counter destabilising market conditions, but these are not intended to finance governments that are unwilling or unable to implement sustainable fiscal policies.

Bank of France Governor Emmanuel Moulin said on 7 October that France did not currently require ECB assistance. He argued that the solution lay in adopting a credible budget rather than expecting monetary intervention.

His position follows increasing speculation about whether the ECB could intervene if French bond yields continue rising.

Such intervention would raise difficult questions about the relationship between monetary policy and national fiscal responsibility. The ECB must consider financial stability across the entire eurozone, but it cannot remove the political obligations of individual governments.

France’s existing excessive deficit procedure also complicates its eligibility for certain forms of exceptional support.

The wider European consequences

France’s problems are developing at a particularly difficult moment for European public finances.

Governments are confronting higher defence commitments, expensive measures to protect households against energy inflation and demands for greater investment in industrial competitiveness.

Italy, another heavily indebted eurozone economy, is facing related pressures. The combination places additional importance on the credibility of the EU’s fiscal rules.

The political consequences within France are already visible. Marine Le Pen has presented a programme proposing €140 billion in spending reductions, while other parties have advanced sharply different approaches to taxation, debt and public expenditure.

Those competing programmes illustrate the difficulty of securing a parliamentary consensus capable of reassuring markets.

The approaching presidential election reduces the likelihood of a durable settlement before voters choose France’s next head of state.

Eurozone partners cannot resolve that impasse from Brussels or Frankfurt. They can insist on fiscal commitments and provide a framework for adjustment, but the political decisions remain with Paris.

France’s immediate challenge is to prevent its budget dispute from becoming a broader loss of confidence in the government’s capacity to manage its finances.

  •  

French Debt Sell-Off Reshapes Eurozone Bond Market as Investors Turn to Germany

France’s borrowing costs have risen to levels last seen more than two decades ago as investors shift towards German, Dutch and other lower-risk European debt, placing Paris at the centre of renewed concern over eurozone public finances.

France is emerging as the principal source of concern in Europe’s government bond market as investors reassess the fiscal strength of eurozone states and increasingly move money towards Germany and other countries regarded as safer borrowers.

The yield on French ten-year government debt has reached its highest level since 2002 after rising by about 70 basis points during September. The difference between French and equivalent German borrowing costs approached 160 basis points last week, its widest since 2012, according to market reporting on the sell-off.

The shift represents a sharp reversal in how investors view French sovereign debt. France has traditionally traded close to Germany and benefited from its status as one of the eurozone’s largest and most liquid bond markets. It is now being treated increasingly as a country whose political and fiscal outlook warrants a substantial premium.

The immediate concern is the French budget.

Paris said in September that this year’s deficit would exceed the government’s five per cent target, while the country faces the additional challenge of issuing a record €340 billion of government bonds in 2027. The money will be needed both to finance current expenditure and refinance debt accumulated during the Covid period.

EU Today reported earlier this week that French debt concerns had already pushed the euro to a 17-month low against the dollar. Political uncertainty ahead of the 2027 presidential election has added to market concern over whether any government will be able to deliver the spending reductions required to stabilise the public finances.

Bond markets, however, are responding to France’s present position rather than promises extending into the next presidential term.

The movement is also beginning to alter longstanding assumptions about which European sovereign borrowers are considered risky.

Italy remains vulnerable. Its ten-year bond spread over Germany rose to about 130 basis points last week, compared with roughly 80 basis points a month earlier. Italian public debt stands at around 138.6 per cent of GDP, and Rome expects its deficit to move above the EU’s three per cent ceiling.

Yet French debt has recently come under greater pressure than Italian debt.

Spain provides an even more striking contrast. During the eurozone sovereign-debt crisis in 2012, Spanish ten-year bonds yielded around five percentage points more than French debt. Spain’s ten-year yield is now approximately 75 basis points below France’s.

The difference reflects stronger Spanish growth and improved confidence in Madrid’s finances, although investors are watching Spanish and Portuguese debt for evidence that the French sell-off is spreading elsewhere in the currency union.

So far, the movement is not comparable with the eurozone crisis of the early 2010s. At that time, Italian bond spreads above Germany exceeded 500 basis points and Greece’s reached thousands of basis points. Current differences remain far smaller.

The direction of capital flows is nevertheless notable. Germany has re-established itself as Europe’s principal bond-market safe haven despite questions earlier this year about Berlin’s increased spending on defence and infrastructure. German ten-year yields fell as investors bought Bunds during the recent turbulence.

Higher sovereign yields feed into the interest costs faced by governments when refinancing debt and can affect borrowing throughout an economy. For a country already running a large deficit, rising yields make efforts to restore the public finances more difficult because an increasing share of expenditure must eventually be devoted to debt servicing.

  •  

When Asia’s central banks turn bond vigilante on Trump

TOKYO – For decades, the US enjoyed a remarkable luxury: its two biggest creditors, Japan and China, kept showing up at Treasury auctions with checkbooks open. Now, Donald Trump’s trade wars, tariff threats and widening geopolitical confrontations raise an uncomfortable question: what happens if Washington’s most reliable bankers decide they’ve had enough? Granted, global investors […]

The post When Asia’s central banks turn bond vigilante on Trump appeared first on Asia Times.

  •  
❌