❌

Reading view

Don’t mistake Indonesia’s MSCI scare for economic weakness

When MSCI floated the idea of downgrading Indonesia to a Standalone Market, anxiety quickly swept through Jakarta’s financial community. Predictably, alarming headlines immediately pointed to foreign capital flight, stock prices dropped and local regulators quickly moved to calm jittery investors. Yet, treating this stock market tremor as a proxy for Indonesia’s overall economic health represents […]

The post Don’t mistake Indonesia’s MSCI scare for economic weakness appeared first on Asia Times.

  •  

ECB Says Artificial Intelligence and Reduced Dependence on Fossil Fuels Are Shielding Europe’s Economy

The European Central Bank says artificial intelligence investment, changing energy consumption and increased government spending have helped the eurozone withstand this year’s energy crisis, although economists warn that several sources of growth may prove temporary.

The eurozone economy has proved more resilient to the energy price shock of 2026 than economists initially expected, supported by increased investment in artificial intelligence, reduced dependence on fossil fuels and higher government expenditure, according to an assessment published by the European Central Bank on Wednesday, 21 October.

ECB economists Óscar Arce, Gerrit Koester and Beatrice Pierluigi found that structural changes in European energy consumption have reduced the economic consequences of rising oil and gas prices. Stronger international demand for technology equipment and additional public spending, particularly in Germany, have also supported growth.

The findings come as the ECB faces renewed inflationary pressure following disruption to global energy markets caused by the conflict involving Iran, raising questions about the outlook for interest rates and economic activity.

Eurozone growth withstands energy shock

In their assessment of the eurozone’s economic resilience, ECB economists reported that economic output continued to expand despite the sharp increase in energy prices earlier this year.

Excluding Ireland, where economic statistics are frequently affected by the activities of multinational companies, real eurozone GDP in the second quarter was 0.6 per cent above its level at the end of 2025.

The ECB also identified quarterly growth of approximately 0.3 per cent over the preceding four quarters, excluding Irish figures.

These results exceeded earlier expectations that the disruption to energy markets would have a greater impact on European manufacturing, consumer spending and business investment.

Nevertheless, the eurozone’s rate of expansion remains modest compared with its longer-term historical performance.

The ECB’s findings suggest that the economy has become better able to absorb international disruptions without experiencing the immediate contractions that might previously have followed comparable energy price increases.

Reduced reliance on imported oil and gas

One of the most significant structural changes concerns energy consumption.

According to the ECB, the eurozone economy is now approximately half as dependent on oil as it was during the early 1990s, measured against economic output.

Greater energy efficiency, the expansion of services and investment in alternative electricity generation have progressively reduced the amount of fossil fuel required to produce economic activity.

The growth of renewable energy has also altered the relationship between natural gas prices and electricity costs.

In Spain, the proportion of hours during which gas-fired power stations determined wholesale electricity prices fell from approximately 80 per cent in 2020 to just over 20 per cent during the first nine months of 2026.

France recorded a similar decline, from approximately 60 per cent to around 20 per cent, supported by its extensive nuclear generating capacity.

Consequently, increases in international gas prices are having a smaller effect on electricity markets in countries with substantial renewable or nuclear generation.

The ECB cautioned, however, that European economies remain exposed to global energy disruptions, particularly through industrial activity and international supply chains.

Artificial intelligence provides unexpected support

The international expansion of artificial intelligence has generated an additional source of demand for European manufacturers and technology companies.

Investment in computing infrastructure, digital services and specialised equipment has increased demand for products supplied by European businesses.

According to the ECB, global trade has performed considerably better than expected at the end of 2025.

The latest projections indicate international trade growth of approximately 4.7 per cent in 2026, compared with the 2 per cent forecast in December.

AI-related investment accounts for part of that improvement.

European manufacturers producing specialised machinery and technology equipment have benefited from increased export orders, while domestic investment in technology has supported economic activity.

However, the ECB found that the effects vary considerably between sectors.

Technology-equipment manufacturers recorded comparatively strong growth in output, employment and new orders.

Software companies performed better in output terms, but the improvement was less evident in employment and new business.

This uneven performance suggests that the economic benefits of the AI investment cycle are concentrated in particular industries.

German spending strengthens European demand

Fiscal policy has provided another source of support.

The ECB estimates that the expansionary fiscal stance in the eurozone has increased to approximately 0.5 percentage points of GDP, twice the level anticipated in December 2025.

Much of the additional stimulus reflects higher German government spending on defence and infrastructure.

Other eurozone governments have introduced measures to limit the effect of energy prices on households and businesses.

Public investment and expenditure have therefore helped compensate for weakness in areas affected by higher import costs and international uncertainty.

Yet the ECB warned that fiscal support cannot necessarily continue at its present level.

Several eurozone governments face borrowing constraints, while additional public spending can place pressure on national budgets.

Interest-rate decisions remain difficult

The ECB’s assessment comes amid expectations of further monetary tightening as policymakers respond to renewed energy-related inflation.

The central bank must consider whether higher energy costs will remain temporary or begin influencing wages, prices and inflation expectations more broadly.

Additional interest-rate increases could reduce inflationary pressures but would also raise borrowing costs for businesses, governments and households.

The economic recovery remains exposed to potential reversals in global demand, international trade and investment in artificial intelligence.

The ECB’s economists also identified geopolitical escalation and further supply-chain disruption as continuing risks.

Their findings indicate that reduced fossil-fuel dependence has made the eurozone less vulnerable to energy shocks, while technology investment and government spending have provided additional support.

Whether that resilience continues into 2027 will depend partly on the durability of international demand and the ability of European governments to maintain investment without increasing inflationary pressure.

  •  

Venezuela’s Acting President Reviews Wage Consensus With Business, Unions

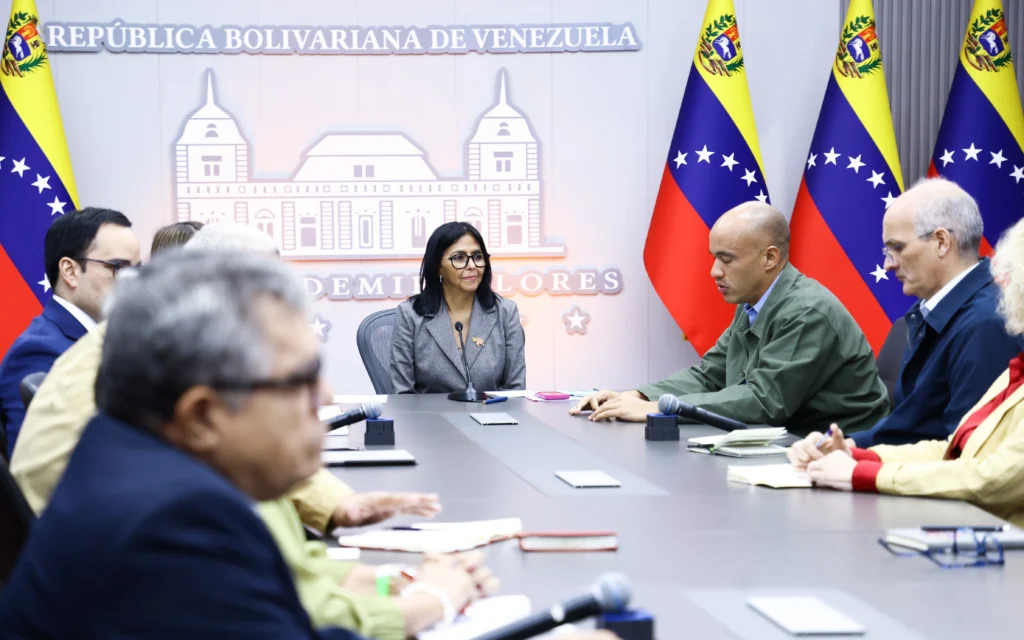
The Acting President, Delcy Rodríguez, led a strategic meeting aimed at consolidating labor and social consensus between the state, business federations and trade union centers of the country. Photo: Venezuelan Presidential Press.

Acting President Delcy Rodríguez led a meeting on Monday with Venezuela’s main business federations and national union confederations to consolidate agreements on wage restoration, salary scales and worker’s protections.


The meeting brought together the Federation of Chambers and Associations of Commerce and Production of Venezuela (Fedecámaras), the Federation of Chambers and Companies of Venezuela (Fedeindustria) and the country’s various union confederations.

The dialogue table evaluated the progress made in the days of debate focused on restoring workers’ purchasing power.

RELATED: Venezuela Promotes Venezuela Feeds Plan and Local Economy Law to Achieve “Hunger 0”

Three core areas shaped the agenda. The first was the progressive conversion of workers’ income into formal salary, a shift the government describes as progressive salary restructuring.

The second involved adjusting salary scales and tables. The third centered on designing guarantees of stability for Venezuelan workers. In this sense, the working group also reviewed draft laws and regulatory instruments meant to shield the framework of social and economic protection for workers.

Dialogue for Sovereign Growth

Venezuelan Acting President Rodríguez reiterated the government’s unwavering commitment to protecting the inalienable rights conquered by the people. She insisted on preserving the workday, end of year bonuses, additional bonuses, vacations, seniority premiums and social benefits in the face of external economic aggression. Following this, the authorities said the three-way dialogue strengthens the model of social justice and lays the groundwork for sovereign economic growth.

The government’s participants included Economy Minister and sector Vice-president Anabel Pereira, Sectoral Vice President for Social and Territorial Socialism Héctor Rodríguez, Planning Minister Ricardo Menéndez and Economy Sectoral Vice-President Calixto Ortega. Labor Minister Carlos Alexis Castillo, University Education Minister Ana María San Juan and Presidential Commissioner for the Constituent Assembly and Labor Consensus Eduardo Piñate also attended.

The labor meeting follows Rodríguez’s announcement days earlier before the UN Food and Agriculture Organization (FAO) that the executive will submit a draft Law for the Local Economy to the National Assembly.

Rodríguez explained that the legal text has as its strategic objective the dynamization of the domestic productive apparatus through the effective linkage of the different economic sectors of the country. Before the multilateral delegations, the Venezuelan Acting President detailed the guiding principles of the norm, designed to strengthen the food sovereignty and security of the Venezuelan people against the blockade of foreign powers.

  •  

How Many Economists Does it Take to Wreck an Economy?

The UK economy will grow 1.3% in 2026, according to the IMF. But will it really, asks David Craig. With unemployment rising, it's just an illusion of out-of-control borrowing. But try getting an economist to admit it.

The post How Many Economists Does it Take to Wreck an Economy? appeared first on The Daily Sceptic.

  •  

Burnham’s “Common Good” is Reheated Fabian Socialism

Andy Burnham's vision of the "common good" – with Net Zero at its heart – is just reheated Fabian socialism, says Dr Tilak Doshi – and the fingerprints of Left-wing economist Mariana Mazzucato are all over it.

The post Burnham’s “Common Good” is Reheated Fabian Socialism appeared first on The Daily Sceptic.

  •  

Central Europe’s Growth Model Is Losing Momentum, IMF Warns

Growth potential across Central and Eastern Europe has fallen sharply from the levels seen around EU accession, with ageing populations, weak productivity, Chinese competition and slower German industry increasingly testing the region’s economic convergence.

The economic model that transformed Central and Eastern Europe after EU accession is losing momentum, according to the International Monetary Fund, which is warning governments that structural reforms are needed if the region is to continue narrowing the income gap with Western Europe.

Carlos Mulas-Granados, the IMF’s regional representative, said on Tuesday that medium-term growth potential across Central and Eastern Europe had declined to around 2.5 per cent, compared with roughly 5 per cent before countries in the region joined the European Union.

The slowdown does not mean that every economy is stagnating. Poland continues to grow faster than much of Western Europe, while the Czech economy has recovered from recent shocks. The concern is instead about the underlying rate at which these economies can expand once temporary fiscal stimulus, EU funding and post-crisis recoveries are stripped out.

Several of the forces behind the region’s earlier success are becoming weaker.

EU accession opened access to the single market, attracted foreign investment and integrated Poland, Czechia, Slovakia and Hungary deeply into European industrial supply chains. German manufacturers in particular moved production eastwards, taking advantage of lower labour costs, skilled workforces and geographic proximity.

That process generated rapid gains in productivity and incomes. It cannot simply be repeated.

Demographics are one of the most immediate constraints. Working-age populations are shrinking across much of the region while ageing increases spending requirements for pensions, health care and social support.

The IMF’s country assessments illustrate the problem. Its assessment of Poland says demographic pressures are mounting even as labour productivity remains comparatively strong, and calls for higher labour participation, better skills and deeper capital markets.

In Slovakia, the Fund expects growth of only 0.9 per cent this year and says adverse demographics and weaker productivity are weighing on the medium-term outlook. The economy remains particularly exposed to manufacturing and the automotive industry.

The Czech Republic faces a similar structural constraint. The IMF estimates its medium-term potential growth at around 1.8 per cent, with population ageing and modest productivity gains limiting further convergence.

External conditions have also changed.

Germany, the region’s principal industrial partner, has experienced prolonged weakness in manufacturing. Central European producers therefore face softer demand from the market around which many of their supply chains were originally built.

At the same time, China has moved from being primarily a source of imports and components to a direct competitor in sectors where Central Europe has substantial industrial exposure, including cars, batteries, machinery and electrical equipment.

That combination is particularly difficult for economies built around export-oriented manufacturing.

The problem overlaps with the wider European competitiveness debate. EU Today reported in July that only 15.7 per cent of the reforms recommended in Mario Draghi’s competitiveness report had been fully implemented at that stage, with important work still outstanding on capital markets, energy and investment.

For Central Europe, progress on those issues has a direct bearing on growth. Smaller national capital markets make it harder for companies to finance expansion. Fragmented energy systems add to industrial costs, while limited access to venture capital can restrict the development of businesses outside established manufacturing sectors.

There are significant differences between countries. Poland’s larger domestic market gives it more insulation from industrial weakness elsewhere and the IMF expects relatively strong growth. Hungary has faced a different combination of weak investment and fiscal constraints, while Slovakia’s dependence on car production leaves it particularly exposed to changes in the European automotive sector.

EU funding remains an important source of investment across the region, particularly for infrastructure and modernisation. But EU transfers cannot by themselves replace improvements in productivity.

The IMF’s argument is therefore less about an immediate recession than about the end of an unusually favourable period of convergence.

Central Europe entered the EU with lower wages, substantial scope to import Western technology and a powerful incentive for Western European manufacturers to move production eastwards. As those gaps narrow, future growth depends more heavily on innovation, skills, investment and domestic productivity.

The region is still converging with Western Europe. The question raised by the latest IMF warning is how quickly that process can continue once the economic advantages that powered its first two decades of EU membership become less powerful.

  •  

There is No Economic Growth. We’re in a Deep Recession

Britain supposedly had 0.4% growth in the last quarter. But when you look closely, says David Craig, it's clear this 'growth' all came from government borrowing and the real economy is already in deep recession.

The post There is No Economic Growth. We’re in a Deep Recession appeared first on The Daily Sceptic.

  •  
❌