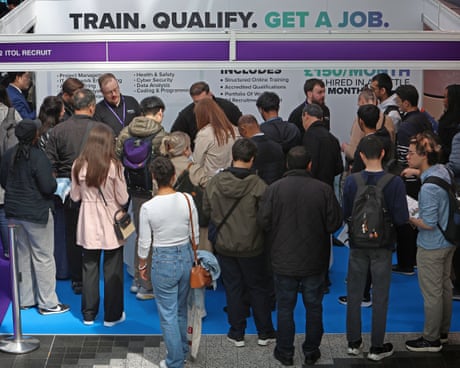
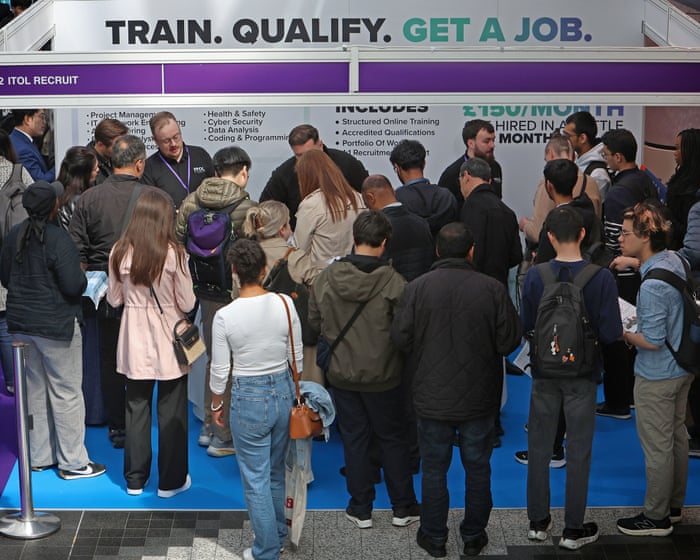
Unemployment in the UK has fallen unexpectedly in the final snapshot of the jobs market before John Healey’s first budget next week.
The jobless rate fell to 4.7% in the three months to August, from 4.9% according to the Office for National Statistics. City economists had forecast a rise to 5%.
The government has made improvements to the Medicare Plan Finder, a key online tool, in time for open enrollment. It helps seniors compare policies to avoid costly surprises.
Blythe Carey went to see a doctor last year after being told the physician was in her Medicare Advantage network. The doctor wasn’t, and later Ms. Carey received a large bill.
The couple has been together for four years without merging bank accounts.
Courtesy of Catherine Work
My fiancé and I have been together for four years and have never had a joint bank account.
We're transparent about our incomes, savings, and spending, and we've never had a fight about money.
We plan to pay for our wedding together, but we won't combine our finances after we get married.
My parents have a shared bank account and kept all their large purchases in both their names, so I thought sharing an account would be my financial destiny, too, if I ever got married. I didn't question it until recently. Now, my partner and I are getting married in just a few months, and we don't plan to combine our finances.
After four years together, we've never had any accounts or cards in both of our names. The closest we ever got to that was me using his credit card on a payment app when we were in Vietnam because mine didn't work. We both contribute to rent and household expenses. We pay back the other person our half of large purchases like flights and hotels, but we don't keep a tab of who owes who what (a nice change from my previous romantic relationships).
We've always been open about money
We were upfront about our income, debt (or lack thereof), and our mutual desire to live below our means from day one. After about three years of dating, we told each other how much we have in savings. We continue to be transparent about money and agree on the vast majority of each other's purchases — it helps that we're both very frugal.
We've built up trust over the years, and we'll continue to offer up personal financial information when we want to, knowing we have privacy. Neither of us has the login information for the other's bank, but we know we can always ask how much the other is earning or spending.
I thought the next step was a shared bank account with two credit cards — I assumed that's what love and commitment meant in an economic way. We kept asking ourselves how having both our names on one account would improve our lives, and we kept coming up blank. I also didn't want to waste time filling out paperwork or calling my bank for something I wasn't even interested in.
Keeping finances separate works for them.
Courtesy of Catherine Work
Our system works for us
We've lived together for almost four years and never had a fight about money. I have some financial anxiety, and I think having a shared account might actually make that worse. Since my fiancée makes more and pays for more, I regularly check in to see if he's still OK with that.
We approached our wedding, our first big purchase together, the same way we plan travel — with Excel, conversations, and making sure we stay under budget to cover unexpected costs. My fiancée bought our rings, and I bought our flights (we're getting married in Denmark). We both agreed to contribute the same amount of money to the wedding. Every payment we make for the big day goes into a spreadsheet, and at the end of all our purchases, if one of us has spent significantly more, the other will make the next large purchase.
Keeping our financial stressors low is also made easier by the fact that we won't plan to have kids or pets, or make any large purchases like a house or a car. Taking care of our parents is the only thing that might one day impact how we view our financial setup.
Another thing we agreed on from the start was that we wanted a pre-nup. Not sharing a bank account and having a pre-nup might not sound romantic (or like we can't share) to some, but if anyone were to look at our purchases, they'd immediately see we do spend our money on each other—just with separate accounts intact.
We haven't fought about money, and I'd like to keep it that way
I know I'm going into a marriage with dignity and respect. My future husband won't get a notification if I spend over $100, he won't be able to review a bank statement at the end of the month to see how many ice creams I've treated myself to, and we won't know how much the other person spent on a Christmas present. We'll never have to ask the other person if we can spend money or fear that our separate emergency funds will be depleted by the other.
My parents shared a bank account, and they often fought over money — one thing I promised myself I'd never do with my future spouse. Keeping our finances separate has worked so far, and I believe it'll continue to after we're married. We're both open to changing our minds one day, but until we have a good reason, we're very happy having separate accounts, together.
France has called for money collected through European Union fines against Google to be used to reduce national contributions to the EU budget as governments negotiate the bloc’s next seven-year financial framework.
Europe Minister Benjamin Haddad said proceeds from penalties imposed on the US technology company should be treated as EU revenue and used to lower the sums governments must pay into the common budget.
The proposal comes as negotiations intensify over the 2028–34 Multiannual Financial Framework, for which the European Commission has proposed expenditure of almost €2 trillion.
Haddad referred to about €4.6 billion in revenue associated with Google penalties and interest.
The proposal is less radical in budgetary terms than it first appears because fines that become final already enter the EU budget as “other revenue”.
The Commission’s explanation of EU budget revenue states that gross national income-based contributions act as the balancing element of the budget after customs duties, VAT-based resources and other revenues — including fines on companies — are taken into account.
Higher income from definitive competition fines can therefore reduce the amount required from national governments.
France is pressing for that mechanism to be applied clearly to the Google proceeds at a time when governments are seeking ways to limit increases in their national payments.
Google has accumulated substantial EU penalties through both competition law and the Digital Markets Act.
A €460 million penalty concerned the Commission’s finding that Google gave preferential treatment to its own services in search results. A further €430 million fine concerned restrictions affecting developers’ ability to direct users towards alternative purchasing channels outside Google Play.
Google has contested elements of the EU enforcement regime and has continued legal proceedings over Commission decisions.
France also faces a sharp increase in its projected contribution.
Against that background, governments are looking at both expenditure reductions and new revenue streams that could limit demands on national treasuries.
The wider negotiations cover possible EU “own resources” — revenue that flows directly or indirectly to the European budget rather than being provided through conventional national contributions.
Existing resources include customs duties, a VAT-based contribution, a plastics contribution and national payments calculated according to gross national income.
The Commission has also proposed additional sources linked to carbon pricing and other EU policies.
Company fines differ from permanent own resources because their size is unpredictable and depends on enforcement decisions and subsequent legal proceedings.
A large fine can provide a one-off boost to EU revenue, but it cannot readily finance recurring expenditure across a seven-year financial framework.
Definitive fines have nevertheless affected member-state contributions before. Commission budget amendments have explicitly incorporated competition penalties as additional revenue, reducing the amount that must be raised elsewhere.
France is now seeking to ensure that the Google proceeds are reflected directly in the sums demanded from national budgets.
The proposal comes before another round of negotiations over the Multiannual Financial Framework, where the size of the budget remains unresolved.
With agreement requiring unanimity among all 27 governments, even relatively small sources of additional revenue are becoming part of the bargaining over who ultimately pays for the EU’s expanding spending commitments.
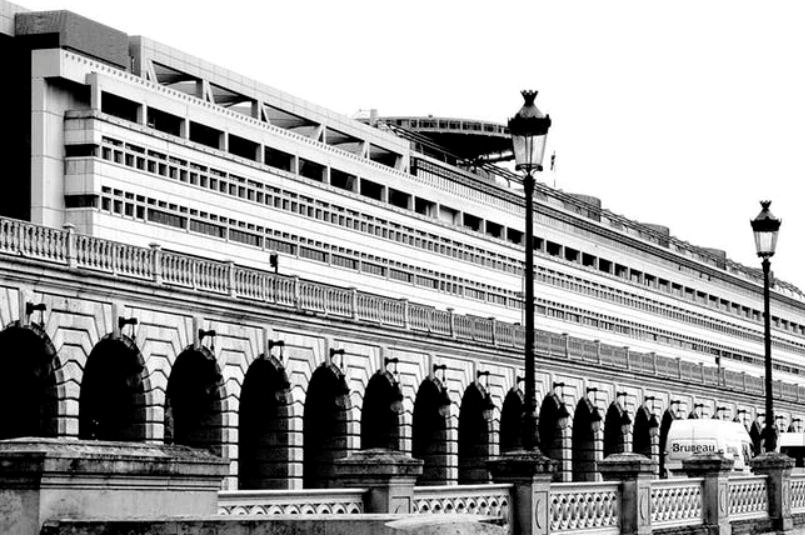
The Ministry of Finance in Paris (Bercy). Jean-François Gornet / Flickr, CC BY-SA
France has crossed a critical threshold as its public debt exceeded €3.5 trillion in the first quarter of 2026, reaching 117.5% of GDP. The French Court of Auditors has sounded the alarm over what it describes as an “alarming” fiscal situation, as public deficits hit record levels and debt-interest costs continue to soar.
The Ministry of Finance in Paris (Bercy). Jean-François Gornet / Flickr, CC BY-SA
Public Debt Exceeds €3.5 Trillion
During the first quarter of 2026, France’s public debt passed the symbolic milestone of €3.5 trillion, reaching €3.5361 trillion at the end of March. The figure underscores the scale of the country’s budgetary challenges.
To put this amount into perspective, France would theoretically have to sell its entire gold reserve, all publicly traded and privately held state assets—including companies such as EDF, Engie, and Airbus—as well as all government-owned buildings and land in an attempt to repay the debt in a single payment. Even such a drastic measure would likely fall short.
In just one quarter, France’s Maastricht-defined public debt increased by €75.6 billion, a sharp rise in a very short period. This growing debt burden reflects a longstanding reality: for more than fifty years, the French government, local authorities, and social security system have collectively spent more each year than they have collected in revenue, particularly through taxation. To cover this structural gap, France has continued borrowing from financial markets.
Debt-to-GDP Ratio Nears Historic High
Beyond the headline figure, analysts and financial institutions are particularly concerned about debt relative to economic output. According to France’s National Institute of Statistics and Economic Studies (INSEE), public debt now equals 117.5% of gross domestic product.
The increase has been dramatic. In 1980, public debt represented only 20% of GDP. By 2000, it had risen to approximately 60%. Over four decades, the debt-to-GDP ratio has nearly increased sixfold.
The current level of 117.5% is approaching the all-time record of 117.8% recorded in the first quarter of 2021 during the COVID-19 pandemic. At that time, President Emmanuel Macron launched an unprecedented economic rescue effort, pledging to spend “whatever it takes” to prevent economic collapse.
Although the health crisis has long since passed, France’s debt trajectory has not slowed significantly. Within the European Union, only Greece and Italy have higher debt ratios, making France the third most indebted country in Europe.
Warnings from the Court of Auditors
In response to what it views as a critical situation, France’s independent Court of Auditors, responsible for overseeing public finances, issued a warning report describing the state of the nation’s finances as “alarming.”
The report, revealed by France Inter and released ten months before the 2027 elections, calls for “strong, credible, and swift measures” to restore fiscal stability.
The court highlights several aggravating factors. First, France remains the only country in the eurozone whose debt level is higher today than it was at the end of the COVID-19 crisis. Second, public deficits continue to break records. France posted a budget deficit equal to 5.1% of GDP in 2025, the second-highest in the eurozone after Italy.
The government’s goal of keeping the deficit at 5% is viewed as unrealistic by the Court of Auditors, which fears a further deterioration of public finances.
Debt-Interest Costs Are Soaring
A particularly troubling development is the rapid increase in debt-servicing costs. As debt accumulates and interest rates rise in financial markets, the amount spent on interest payments has grown dramatically.
In the current state budget, debt-servicing expenses have become the government’s single largest expenditure category, surpassing spending on the national education system (excluding pension obligations).
Paradoxically, this situation coincides with a significant increase in taxation. Taxes rose by €38 billion across 2025 and 2026 as part of efforts to limit further deficit growth. Yet France already has the highest overall tax burden in Europe when taxes and social contributions are combined.
This creates both political and economic tensions: higher taxes have not been sufficient to slow the growth of public debt, raising questions about the effectiveness of current fiscal measures.
France’s current trajectory highlights a troubling economic reality: structural public spending is growing faster than tax revenues, creating a persistent deficit that is difficult to eliminate.
Programs such as social welfare, pensions, healthcare, and public investment involve long-term commitments, while tax revenues tend to fluctuate with economic conditions.
This divergence between economic growth and debt growth raises a fundamental question for France’s public finances. If GDP expands by only 1% to 2% annually while debt continues to grow by 3% to 4% per year, the debt-to-GDP ratio will inevitably continue rising unless major policy changes are implemented.
French voters heading to the polls in 2027 will likely face a difficult choice between maintaining current levels of public services and restoring fiscal sustainability.
Breaking the Debt Spiral
To reverse the trend, experts and institutions such as the Court of Auditors recommend a combination of measures: controlling the growth of public spending, improving the efficiency of existing expenditures, broadening the tax base without increasing marginal tax rates, and accelerating economic growth to boost revenues.
As the eurozone’s second-largest economy after Germany, France possesses significant economic resources. However, meaningful structural reforms will require political consensus and a willingness to accept difficult compromises.
In the short term, the government must demonstrate that its deficit-reduction commitments are credible. In the medium term, comprehensive reforms of public spending—particularly in pensions and healthcare—appear unavoidable. Over the long term, only sustained economic growth combined with spending discipline will be capable of reversing the debt dynamics that have characterized France for decades.

 Login