❌

Reading view

Electric Car Sales Surge 70 Per Cent as France and Germany Seek Changes to EU Emissions Rules

Registrations of fully electric cars across 17 European markets increased by 70.3 per cent in September, according to industry figures published on Monday, 19 October, as France and Germany seek to ease the European Union’s emissions requirements for new vehicles.

The data show that 300,202 battery-electric cars were registered during the month, accounting for 32.6 per cent of new passenger-car registrations in the markets surveyed.

The figures emerge three days after Paris and Berlin announced a joint position on the future of Europe’s automotive industry, proposing greater flexibility in the EU’s 2035 emissions regime while introducing measures intended to favour vehicles manufactured in Europe.

Electric vehicles gain market share

The latest figures, compiled by E-Mobility Europe, New Automotive and Fier Automotive, indicate that electric vehicle demand accelerated sharply during September.

According to the industry data published on 19 October, approximately 1.98 million battery-electric cars have been registered across the 17 markets during the first nine months of 2026, an increase of 38.1 per cent compared with the equivalent period last year.

Higher oil prices, government incentives and the introduction of more affordable electric models have all contributed to demand.

The figures represent a substantial change in the composition of European new-car sales, although they cover selected markets rather than constituting a complete statistical account of the EU’s 27 Member States.

France recorded 65,243 battery-electric registrations in September, representing 41.7 per cent of its new-car market. Germany registered 88,724 electric vehicles, giving the technology a market share of 34.6 per cent.

Both countries have substantial automotive manufacturing industries and are directly involved in negotiations over Europe’s future emissions legislation.

Significant differences between European markets

Despite the overall increase, electric vehicle adoption remains uneven across the continent.

Norway retained its position as Europe’s most electrified new-car market, with battery-electric vehicles accounting for 98.8 per cent of registrations in September.

Denmark followed with 88.8 per cent, while Finland recorded 62.7 per cent and Sweden 49 per cent.

Electric models also accounted for approximately half of new-car registrations in Belgium, the Netherlands, Ireland and Portugal.

At the other end of the market, battery-electric vehicles represented only 11.2 per cent of registrations in the Czech Republic, 7.6 per cent in Italy and 6.2 per cent in Poland.

These differences illustrate the difficulty of establishing a uniform European transition timetable.

Household incomes, purchase incentives, vehicle prices and charging infrastructure differ substantially between countries. The availability of affordable electric cars is particularly important in markets where buyers are more sensitive to the initial purchase price.

The varying national figures also complicate the EU’s industrial calculations, since manufacturers must operate across markets progressing at different rates.

France and Germany reach automotive compromise

On 16 October, French President Emmanuel Macron and German Chancellor Friedrich Merz agreed on a joint approach to changes in European automotive regulations.

Under the proposed compromise, car manufacturers would be required to reduce carbon dioxide emissions from new vehicles by 90 per cent by 2035 compared with the 2021 reference level.

The agreement would also remove a proposed requirement to compensate for the remaining emissions through measures such as the use of low-carbon steel.

The change would create additional opportunities for manufacturers to continue selling vehicles powered by combustion engines beyond 2035, subject to the final legislative framework.

In their joint declaration on the automotive industry’s future, the French and German governments argued that emissions reduction must be combined with industrial competitiveness, investment and European manufacturing capacity.

The agreement also envisages preferential treatment for vehicles produced in Europe under certain public procurement and subsidy arrangements.

Britain could potentially benefit from provisions allowing selected European partners to qualify under the proposed industrial framework.

The Franco-German understanding is not, however, a final EU legislative decision. Changes to the regulatory regime require agreement through the relevant European legislative procedures.

Automotive competitiveness enters the debate

The principal argument advanced by supporters of greater regulatory flexibility is that European manufacturers need additional time to adapt production, protect employment and compete with international rivals.

German manufacturers retain extensive investment in combustion-engine and hybrid technology, while French producers have placed considerable emphasis on electric vehicles and maintaining European supply chains.

The negotiations therefore concern more than emissions limits. They also involve battery production, access to raw materials, manufacturing costs and the ability of European companies to compete with producers in China and other markets.

Supporters of the existing transition timetable argue that weakening long-term requirements could discourage investment in electric manufacturing capacity just as consumer demand is increasing.

Manufacturers seeking greater flexibility maintain that regulatory targets must account for uneven market conditions and the cost of developing new technologies.

September’s sales figures provide evidence that electric vehicle adoption is accelerating, but they do not establish whether the same rate of growth will continue without existing incentives.

The debate now centres on whether regulatory relaxation will preserve Europe’s automotive industry during the transition or slow investment in the technology that is already capturing an increasing share of the market.
  •  

EU Parliament Moves to Strengthen Critical Raw Materials Rules Amid Growing Dependence on China

The European Parliament is preparing to vote on amendments to the as Brussels seeks to reduce its dependence on foreign suppliers of minerals essential for defence equipment, electric vehicles, advanced electronics and industrial production.

The proposals, scheduled for debate in Strasbourg on Monday, 19 October, and a vote on Tuesday, would strengthen coordination over strategic supplies and revise the responsibilities of European companies that depend on vulnerable international supply chains.

At the centre of the discussions is a proposal to establish a European Critical Raw Materials Centre, which would coordinate purchasing arrangements, assess supply risks and support the development of strategic reserves.

The initiative comes amid increasing concern over China’s dominant position in the processing and supply of several materials regarded as indispensable to European industry.

Parliament considers stronger European coordination

According to the European Parliament’s October plenary briefing, the proposed Critical Raw Materials Centre would operate as an EU body responsible for several functions currently distributed between European institutions and national authorities.

These would include identifying vulnerabilities in supply chains, conducting risk assessments, coordinating contingency stocks and supporting joint purchasing arrangements.

The objective is to give European governments and manufacturers greater capacity to respond to interruptions in supplies of minerals and processed materials that cannot easily be replaced.

The legislative report has been prepared by the Parliament’s Committee on Industry, Research and Energy, with Dutch Social Democrat MEP Mohammed Chahim serving as rapporteur.

The committee examined amendments to the existing legislation during 2026, with its revised report submitted for plenary consideration on 9th October.

Tuesday’s vote is intended to establish Parliament’s position for negotiations with the Council. It would not, by itself, constitute final adoption of the amended regulation.

China’s position creates supply risks

The European Union depends heavily on imported critical raw materials, particularly those required for batteries, permanent magnets, semiconductors and specialist industrial equipment.

China occupies a particularly important position in the refining and processing of rare earth elements, graphite and several other materials used in high-technology manufacturing.

The concentration of production creates vulnerabilities because disruption at a single stage of processing can affect manufacturers operating across multiple European countries.

According to the Council of the European Union’s assessment of strategic mineral supplies, China is the principal supplier to the EU for numerous materials, including gallium, germanium, magnesium and rare earth elements.

These substances are used in applications extending well beyond electric vehicles.

Permanent magnets are required for certain electric motors, wind turbines and defence systems, while other critical materials are used in radar, satellites, aircraft components and advanced electronic equipment.

Restrictions affecting their availability can therefore have consequences for European industrial output, defence procurement and the development of new technology.

The question for EU policymakers is not simply whether minerals can be obtained, but whether Europe has sufficient alternative sources and processing capacity to withstand restrictions imposed by a dominant supplier.

Existing targets remain difficult to achieve

The Critical Raw Materials Act entered into force in May 2024 and established benchmarks intended to strengthen European production and diversify imports by 2030.

Under the existing framework, the EU aims to develop extraction capacity equivalent to at least 10 per cent of its annual consumption of strategic raw materials, where geological reserves allow.

The corresponding benchmarks are 40 per cent for processing and 25 per cent for recycling.

The legislation also seeks to prevent any single non-EU country from supplying more than 65 per cent of the Union’s annual consumption of a particular strategic raw material at any relevant processing stage.

These are policy benchmarks rather than binding production quotas imposed on individual companies.

Their achievement depends on the development of mines, processing facilities and recycling operations, as well as the ability to attract investment.

New extraction projects frequently require lengthy environmental assessments, infrastructure development and extensive capital investment. Processing operations face additional challenges involving energy costs, technical expertise and commercial competitiveness.

Consequently, reducing import dependence involves more than identifying mineral deposits within European territory.

Greater obligations for manufacturers

The proposed amendments also address the responsibilities of major European companies using strategic raw materials.

Under provisions examined by the parliamentary committee, the European Commission would take a greater role in identifying large manufacturers whose operations depend on strategically important supplies.

These companies could face requirements to assess vulnerabilities in their supply chains, including the geographical location of extraction and processing operations and the ownership of relevant facilities.

The arrangements would be particularly significant for businesses producing batteries, aircraft, drones, satellites, advanced chips and other products considered strategically important.

Where significant risks are identified, companies could be expected to consider measures including diversification, improved material efficiency or maintaining stocks.

The proposals also seek to strengthen recycling and the recovery of valuable materials from existing products, reducing the quantity of newly extracted resources required by European industry.

Recycling alone cannot remove the need for imports, particularly where demand for new technologies is increasing, but it can provide an additional source of supply.

Supply security becomes an industrial priority

The legislation forms part of a wider effort to link European industrial policy with economic security.

Brussels has been seeking additional raw materials partnerships with third countries, while manufacturers remain concerned about the commercial cost of building alternative supply chains.

Recent EU discussions concerning cooperation with Vietnam illustrate the emphasis being placed on securing alternative access to minerals such as tungsten and rare earth elements.

However, diversifying supplies does not necessarily mean transferring extraction and processing to Europe. Partnerships with reliable external producers may remain essential, particularly for materials unavailable in sufficient quantities within the Union.

The proposed European centre would therefore have to balance internal production, international purchasing, strategic stocks and commercial demand.

The immediate legislative issue is whether the revised framework gives European institutions sufficient powers to coordinate these activities without placing disproportionate administrative obligations on businesses.

Tuesday’s parliamentary vote will determine the negotiating position MEPs take into discussions with EU governments over how those responsibilities should be distributed.

  •  

Electricity costs put UK steelmakers in worst position in three years against EU rivals

Premium paid over French counterparts has risen to almost £30 a megawatt hour, analysis by lobby group finds

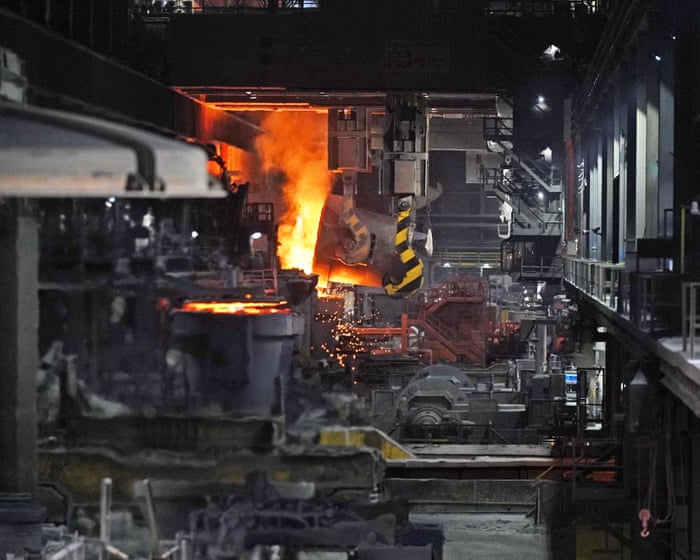
British steelmakers have been pushed further behind European rivals on electricity costs after the US-Israeli war on Iran caused a surge in global gas prices.

The premium paid by the British industry over its French counterpart has risen to almost £30 a megawatt hour (MWh), its highest level in three years, according to analysis by the lobby group UK Steel.

Continue reading...

© Photograph: Ian Forsyth/Getty Images

© Photograph: Ian Forsyth/Getty Images

© Photograph: Ian Forsyth/Getty Images

  •  
❌