❌

Reading view

French Debt Sell-Off Reshapes Eurozone Bond Market as Investors Turn to Germany

France’s borrowing costs have risen to levels last seen more than two decades ago as investors shift towards German, Dutch and other lower-risk European debt, placing Paris at the centre of renewed concern over eurozone public finances.

France is emerging as the principal source of concern in Europe’s government bond market as investors reassess the fiscal strength of eurozone states and increasingly move money towards Germany and other countries regarded as safer borrowers.

The yield on French ten-year government debt has reached its highest level since 2002 after rising by about 70 basis points during September. The difference between French and equivalent German borrowing costs approached 160 basis points last week, its widest since 2012, according to market reporting on the sell-off.

The shift represents a sharp reversal in how investors view French sovereign debt. France has traditionally traded close to Germany and benefited from its status as one of the eurozone’s largest and most liquid bond markets. It is now being treated increasingly as a country whose political and fiscal outlook warrants a substantial premium.

The immediate concern is the French budget.

Paris said in September that this year’s deficit would exceed the government’s five per cent target, while the country faces the additional challenge of issuing a record €340 billion of government bonds in 2027. The money will be needed both to finance current expenditure and refinance debt accumulated during the Covid period.

EU Today reported earlier this week that French debt concerns had already pushed the euro to a 17-month low against the dollar. Political uncertainty ahead of the 2027 presidential election has added to market concern over whether any government will be able to deliver the spending reductions required to stabilise the public finances.

Bond markets, however, are responding to France’s present position rather than promises extending into the next presidential term.

The movement is also beginning to alter longstanding assumptions about which European sovereign borrowers are considered risky.

Italy remains vulnerable. Its ten-year bond spread over Germany rose to about 130 basis points last week, compared with roughly 80 basis points a month earlier. Italian public debt stands at around 138.6 per cent of GDP, and Rome expects its deficit to move above the EU’s three per cent ceiling.

Yet French debt has recently come under greater pressure than Italian debt.

Spain provides an even more striking contrast. During the eurozone sovereign-debt crisis in 2012, Spanish ten-year bonds yielded around five percentage points more than French debt. Spain’s ten-year yield is now approximately 75 basis points below France’s.

The difference reflects stronger Spanish growth and improved confidence in Madrid’s finances, although investors are watching Spanish and Portuguese debt for evidence that the French sell-off is spreading elsewhere in the currency union.

So far, the movement is not comparable with the eurozone crisis of the early 2010s. At that time, Italian bond spreads above Germany exceeded 500 basis points and Greece’s reached thousands of basis points. Current differences remain far smaller.

The direction of capital flows is nevertheless notable. Germany has re-established itself as Europe’s principal bond-market safe haven despite questions earlier this year about Berlin’s increased spending on defence and infrastructure. German ten-year yields fell as investors bought Bunds during the recent turbulence.

Higher sovereign yields feed into the interest costs faced by governments when refinancing debt and can affect borrowing throughout an economy. For a country already running a large deficit, rising yields make efforts to restore the public finances more difficult because an increasing share of expenditure must eventually be devoted to debt servicing.

  •  

When Asia’s central banks turn bond vigilante on Trump

TOKYO – For decades, the US enjoyed a remarkable luxury: its two biggest creditors, Japan and China, kept showing up at Treasury auctions with checkbooks open. Now, Donald Trump’s trade wars, tariff threats and widening geopolitical confrontations raise an uncomfortable question: what happens if Washington’s most reliable bankers decide they’ve had enough? Granted, global investors […]

The post When Asia’s central banks turn bond vigilante on Trump appeared first on Asia Times.

  •  

Le Pen Sets Out €140bn Spending-Cut Plan as French Debt Dominates 2027 Race

Marine Le Pen has set out plans to cut French public spending by €140 billion by 2032, reduce the deficit and impose a constitutional constraint on future borrowing, placing France’s deteriorating public finances at the centre of the campaign for the 2027 presidential election.

Marine Le Pen has presented a five-year fiscal programme under which a National Rally administration would seek €140 billion in net savings by 2032, restore France’s primary budget balance within 18 months and bring the headline deficit back below the European Union’s three per cent threshold by 2030.

The proposals, presented on Tuesday as Le Pen outlined the financial trajectory she would pursue during a presidential term, come as France faces rising borrowing costs and a public debt ratio approaching 120 per cent of GDP.

The scale of the problem was underlined on the same day by France’s Directorate-General of the Treasury. Its latest report on public debt projects the debt ratio at 119.3 per cent of GDP this year before rising to 121.7 per cent in 2027. Debt stood at 115.7 per cent at the end of 2025.

EU Today has already reported that French borrowing costs and concerns over the sustainability of the country’s finances have begun to weigh on the euro and widen the gap between French and German government bond yields.

Le Pen’s programme is therefore aimed not only at French voters but at financial markets increasingly focused on whether Paris can prevent debt from continuing to rise.

According to the proposals outlined on Tuesday, spending reductions would be concentrated heavily in the first three years of a Le Pen presidency. She would also seek to introduce what she calls a constitutional “golden rule”, requiring successive governments to reduce the budget deficit each year.

The measure would be put to a referendum and is intended to make deficit reduction binding beyond an individual government’s annual budget decisions.

Le Pen has also proposed reducing France’s public debt to around 112 per cent of GDP by 2032. That would reverse the trajectory currently expected by the French government, although the National Rally’s assumptions would depend on its ability to deliver the proposed savings and on economic growth during the next presidential term.

Among the most politically significant proposals is a plan to restrict France’s net contribution to the EU budget to €5 billion. The party argues that some European spending should instead be financed through harmonised taxes on products such as tobacco and alcohol.

Le Pen also expects substantial savings from tighter immigration controls and the introduction of the National Rally’s proposed “national preference” rules for access to parts of the welfare system. Her programme estimates that measures connected with immigration could eventually produce savings of as much as €29 billion annually.

Other elements include changes to pension policy, reductions in corporate and energy taxation, measures against VAT fraud, the abolition of more than 120 taxes and a reduction in the number of state agencies.

The programme marks an attempt by Le Pen to make fiscal policy a central part of a campaign that has until now been dominated largely by immigration, security and questions surrounding France’s political fragmentation.

The timing is significant. Prime Minister Sébastien Lecornu’s government has itself introduced a difficult fiscal consolidation programme. The 2027 budget presented by the Finance Ministry envisages €54 billion in measures to improve the public finances, including €43 billion contained directly in the state and social-security budgets.

The government expects the deficit to fall from 5.4 per cent of GDP in 2026 to five per cent next year. It forecasts growth of only 0.5 per cent this year before a recovery to one per cent in 2027.

The debt burden is becoming increasingly costly. Interest payments are expected to reach €91.2 billion in 2027, up from €79.2 billion this year, according to the Finance Ministry. By 2030, total public-sector interest costs are projected to reach 3.7 per cent of GDP.

That gives the presidential campaign an economic dimension that is difficult to separate from France’s relationship with Brussels. Paris remains subject to EU fiscal rules requiring a gradual reduction in its deficit, while any attempt to reduce the French contribution to the EU budget would require negotiations with the other member states.

Le Pen enters that debate from a strong electoral position. Recent polling examined by EU Today has placed her ahead in first-round scenarios for 2027, although the final field remains unsettled. EU Today reported in September that Le Pen was polling between 33 and 36 per cent depending on her opponents.

Her latest intervention shifts part of the campaign onto terrain traditionally associated with the centre-right: public spending, debt and the credibility of France’s finances.

With the government attempting to secure parliamentary support for its own austerity measures and French borrowing costs under closer scrutiny, the question of how the country pays for the state is now moving towards the centre of the contest to succeed Emmanuel Macron.

  •  

Euro Falls to 17-Month Low as French Debt Fears Return to Markets

The euro fell to its lowest level against the dollar since May 2025 on Monday as investors reacted to rising French borrowing costs, political uncertainty and doubts over Paris’s ability to stabilise its public finances before next year’s presidential election.

The euro fell to a 17-month low against the US dollar on Monday as renewed pressure on French government debt raised concern over the fiscal position of the eurozone’s second-largest economy.

The single currency dropped as far as $1.116 during trading, its weakest level since May 2025, before recovering part of the fall. By late Monday it was trading at around $1.121, still lower on the day.

The move followed a sharp sell-off in French government bonds and a widening gap between French and German borrowing costs.

According to market data published on Monday, the spread between French government debt and equivalent German Bunds had approached 160 basis points on Friday, its widest level since the eurozone sovereign-debt crisis in 2011.

The gap subsequently narrowed, but the scale of the movement has drawn attention back to France’s public finances.

French debt is already close to 120 per cent of gross domestic product and is expected to continue rising.

Investors are now assessing whether Prime Minister Sébastien Lecornu’s minority government can secure sufficient parliamentary support for measures intended to put the budget on a more sustainable path.

That challenge is becoming more difficult as France approaches its 2027 presidential election.

Spending cuts and tax increases are politically sensitive even under stable parliamentary conditions. Lecornu’s administration does not have an outright majority in the National Assembly, while opposition parties have challenged several elements of the government’s fiscal programme.

The French economy itself is providing little additional room.

Revised national accounts examined by EU Today showed that the economy failed to grow during the second quarter, while household purchasing power weakened and investment declined.

Slower growth makes deficit reduction harder because tax revenues tend to grow more slowly while welfare and debt-servicing costs remain high.

Bond markets have also changed the calculation.

For much of the period following the eurozone debt crisis, France was able to borrow at historically low rates. Higher interest rates now mean maturing debt has to be refinanced at greater cost.

France’s debt burden is therefore rising at the same time as the price of servicing it increases.

The euro’s fall on Monday shows that those concerns are no longer confined to the French bond market.

Currency traders are also assessing whether fiscal pressure in France could affect confidence in the wider euro area.

The comparison with the sovereign-debt crisis of 2010–12 should nevertheless be treated cautiously.

France remains one of Europe’s largest and most diversified economies, and the eurozone now has institutional mechanisms and European Central Bank instruments that did not exist at the beginning of the earlier crisis.

There is also no indication that France is unable to finance itself.

What markets are pricing is an increase in the risk attached to holding French debt and growing uncertainty over the country’s medium-term fiscal trajectory.

The euro has now fallen for four successive weeks against the dollar and has lost more than three per cent over that period.

US monetary policy is contributing to the movement. Persistent inflation indicators have supported the dollar even as expectations of an immediate Federal Reserve interest-rate increase have declined.

For Europe, however, Monday’s trading was dominated by France.

French fiscal policy has been a domestic political dispute for much of the past year. The widening bond spread and the euro’s fall show that it is increasingly becoming a eurozone market issue.

  •  

BT strikes £400M deal for TalkTalk

BT Group stepped in to acquire TalkTalk’s consumer and wholesale businesses out of administration, effectively preventing a collapse of one of the UK’s major broadband providers.

The deal will result in a total cash impact of £400 million in BT’s current financial year, which runs to 31 March 2027, involving the purchase price and other costs.

BT stated TalkTalk had embarked on a prolonged but ultimately unsuccessful sales process for its operations and it took action after recognising the risk to the country, especially vulnerable customers and key public services “should the company collapse”.

The deal will bring BT 1.5 million retail customers and 1 million wholesale customers across the UK.

BT stated TalkTalk reported revenue of £1.2 billion and “was loss-making” in the last 12 months, but it is confident the company would become value accretive as the business is stabilised and synergies realised.

CEO Allison Kirkby described the situation as “genuinely unprecedented”, saying millions of citizens and businesses were at risk if TalkTalk had collapsed.

She said the acquisition was “the only viable option to keep millions of customers connected and supported”.

The deal faces an antitrust review given BT owns UK broadband company Openreach, which is a major TalkTalk rival.

However, the government has issued a Public Interest Intervention Notice due to the impact a collapse of TalkTalk could have on vital phone and broadband services.

The Competition and Markets Authority is to report its findings to the government by 19 October.

Stark warning
Kester Mann, director of consumer and connectivity at FDM CCS Insight, said the BT deal cements “a painful decline” of one of the UK’s most established broadband providers and its demise should serve “as a stark warning to any value-focused telecom provider”.

“With a clear value-for-money proposition, it should have been thriving amid continued concerns over the cost of living. But it failed to respond sufficiently to a fast-changing and increasingly competitive market, became burdened with debt following a buy-out in 2021 and regularly suffered with poor perception over service.”

The post BT strikes £400M deal for TalkTalk appeared first on Mobile World Live.

  •  

BT pitches AI receptionist to UK businesses

BT Business rolled out a new AI suite in the UK to help businesses adopt the technology while overcoming complexity and security concerns which may be holding them back.

The operator stated AI from BT was introduced following research it conducted which revealed 66% of small businesses recognise the potential benefits of AI, but more than half are not yet realising its full-value.

It highlighted AI Receptionist as a standout feature. BT stated it can help businesses manage customer enquiries “around the clock” and never miss a call.

BT stated small businesses in the UK can lose £3.7 billion per year through missed calls, with 67% missing at least one potentially valuable call on an average day.

It stated AI Receptionist can simplify management of appointments, and provide a more efficient system for follow-ups and a tailored customer experience, with customisable voice and accent options.

The company stated it would be particularly useful across trades and field-based businesses, for estate agents, legal and financial services, the hospitality sector and retailers.

Other tools include an AI Adoption Hub offering practical guides, prompt packs, expert insights and real-world examples of businesses using the technology.

BT Business CEO Jon James said AI has the potential to drive growth in the UK “but many businesses are struggling to know how to begin and how adopt simply and securely”.

“AI Receptionist is the first step in the journey, helping businesses capture every opportunity, reduce admin and deliver responsive, personalised service around the clock, while keeping their customer data protected.”

The post BT pitches AI receptionist to UK businesses appeared first on Mobile World Live.

  •  

US blast simulation targets China’s alleged secret nuke testing

Faced with rising great-power suspicions and the challenge of verifying clandestine, cavity-muffled detonations, the US is turning to high-precision subterranean blast experiments in the Nevada desert to strip covert nuclear testing of its technical cover. Last month, the US Department of Energy (DOE) reported that the National Nuclear Security Administration (NNSA) conducted an underground, non-nuclear […]

The post US blast simulation targets China’s alleged secret nuke testing appeared first on Asia Times.

  •  

Blame AI for global bond market tremors

The global bond markets are a sensitive lot. And they’ve been having a particularly tricky time lately. Spooked by high inflation, high interest rates and high levels of government debt across the world, those markets have become less stable over the summer. The prices of government bonds – what governments sell to investors – have gone down. […]

The post Blame AI for global bond market tremors appeared first on Asia Times.

  •  

Bond markets aren’t buying the inflation-is-tamed fairy tale

TOKYO — Anyone betting that inflation risks are fading should look at the US Treasury market. The sharp selloff in Treasury Inflation-Protected Securities (TIPS) suggests the world’s biggest bond market is growing less convinced that price pressures are contained. Investors are rethinking the inflation outlook, with implications for Federal Reserve policy, real rates and stock […]

The post Bond markets aren’t buying the inflation-is-tamed fairy tale appeared first on Asia Times.

  •  

French Public-Sector Strike Adds Pressure Ahead of 2027 Budget

French public-sector workers went on strike on Tuesday as demonstrations and school blockades spread across the country, two days before the government is due to present its 2027 budget.

Teachers, firefighters and health workers were among those taking part, with around 170 demonstrations planned nationally. High-school students also blockaded hundreds of schools, extending protests that began over teacher shortages, overcrowded classrooms and conditions in the education system.

The industrial action, accompanied by the traditional violence, places Prime Minister Sébastien Lecornu’s government under additional pressure before ministers present the draft finance and social-security budgets on Thursday, 1st October.

The French Education Ministry reported that 13.71 per cent of teachers participated in Tuesday’s strike across most of metropolitan France and Réunion. Participation reached 15.28 per cent among primary-school teachers and 12.74 per cent in secondary education.

Separate student action affected hundreds of secondary schools.

Protests were reported in Paris, Lille, Lyon, Nice and other cities. Some demonstrations involved clashes with police and damage outside schools, although much of Tuesday’s public-sector action proceeded without major disruption.

The dispute is centred partly on government spending plans.

Trade unions oppose a proposed freeze in the salary index used to calculate public-sector pay and argue that years of inflation have already reduced employees’ purchasing power. Firefighters have also demanded additional resources following the extensive wildfires that struck France during the summer.

The government is preparing its budget against a worsening fiscal background.

France’s public debt has climbed close to 120 per cent of gross domestic product, while the budget deficit remains well above the European Union’s 3 per cent ceiling.

EU Today reported earlier this month that French debt was heading towards 120 per cent of GDP, accompanied by an increase in the premium investors demand to hold French government bonds rather than German debt.

Higher interest rates are adding to the pressure. Debt-servicing costs have become one of the largest areas of central government spending, restricting the room available for tax reductions or additional expenditure.

The government has also reduced its 2026 economic growth forecast to 0.5 per cent.

Finance Minister Roland Lescure has acknowledged that France will miss its earlier deficit target, leaving the 2027 budget with the difficult task of demonstrating a credible path towards stabilising the public finances without provoking further political resistance.

The budget is due to be formally presented on Thursday. The Finance Ministry has confirmed that Lescure, Public Accounts Minister David Amiel, Labour Minister Jean-Pierre Farandou and Health Minister Stéphanie Rist will present the finance and social-security bills following the Council of Ministers.

The argument is taking place while EU fiscal surveillance is itself entering a more demanding phase.

Under the revised Stability and Growth Pact, member states are expected to follow agreed medium-term expenditure paths designed to bring deficits and debt onto sustainable trajectories.

EU Today recently examined how the EU’s fiscal rules face an enforcement test in October, when finance ministers and the European Commission return to national budget compliance. France is one of the countries where implementation will receive particularly close attention because of its debt level, persistent deficit and political difficulty in securing parliamentary agreement for spending reductions.

The domestic parliamentary arithmetic remains difficult. Lecornu’s government does not control an outright majority in the National Assembly, meaning the budget could become the subject of amendments, confidence votes or further negotiations with opposition parties.

The government has previously relied on Article 49.3 of the constitution to pass financial legislation without a conventional parliamentary vote, although use of the mechanism exposes a government to motions of no confidence.

Tuesday’s strikes add another layer to those negotiations. Trade unions have indicated that further action is possible if the budget contains measures they regard as unacceptable. The CGT has demanded changes to planned spending reductions and public-sector pay policy.

The precise scale of the government’s fiscal measures will become clearer on Thursday. For France, the budget will have to address three pressures simultaneously: deteriorating public finances, the EU’s fiscal framework and domestic opposition to further restraint.

  •  

Bond vigilantes on a savage hunt as global yields run wild

TOKYO — The bond vigilantes are back — and now they’re patrolling every major debt market at once. As deficits balloon, spending runs unchecked and oil prices spike, investors are reasserting control over markets that once seemed shielded from shocks and sending yields skyrocketing. The revolt spans the US, Japan, Europe and beyond as a […]

The post Bond vigilantes on a savage hunt as global yields run wild appeared first on Asia Times.

  •  

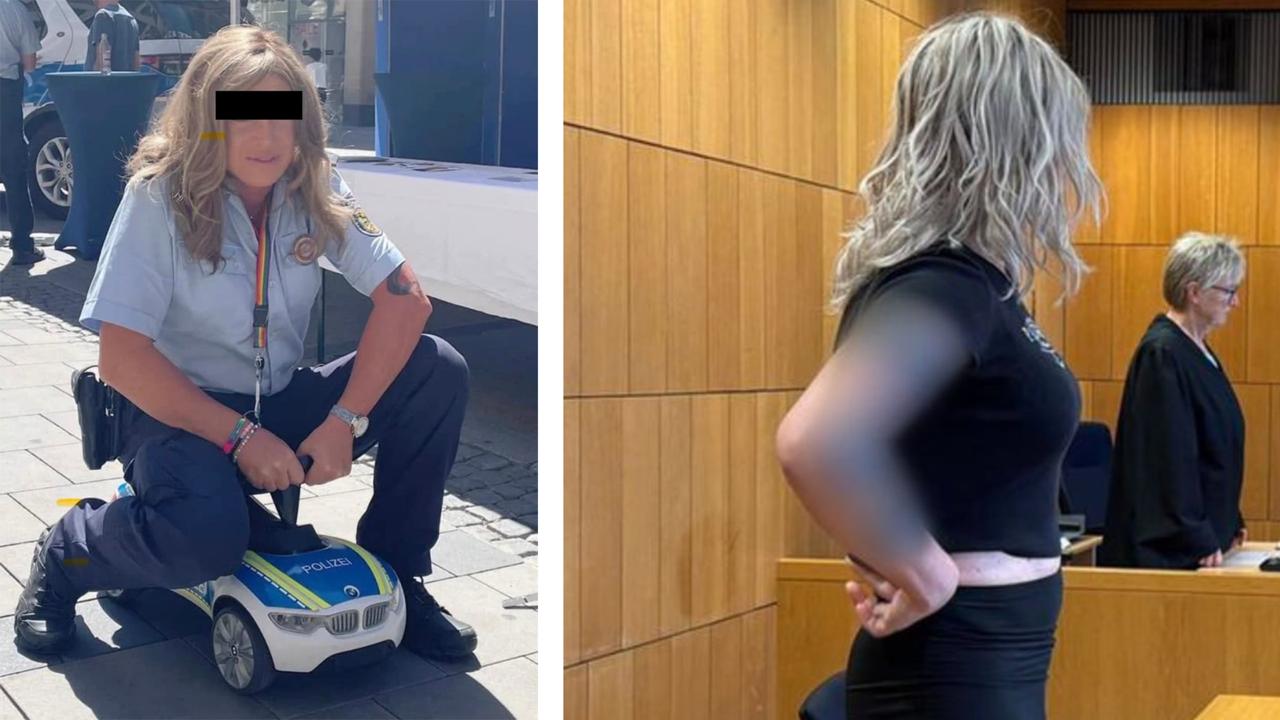
Germany: Transgender police officer confesses to raping 14-year-old girl in fast food bathroom, possessing up 2,000 violent child porn files, and producing animal porn

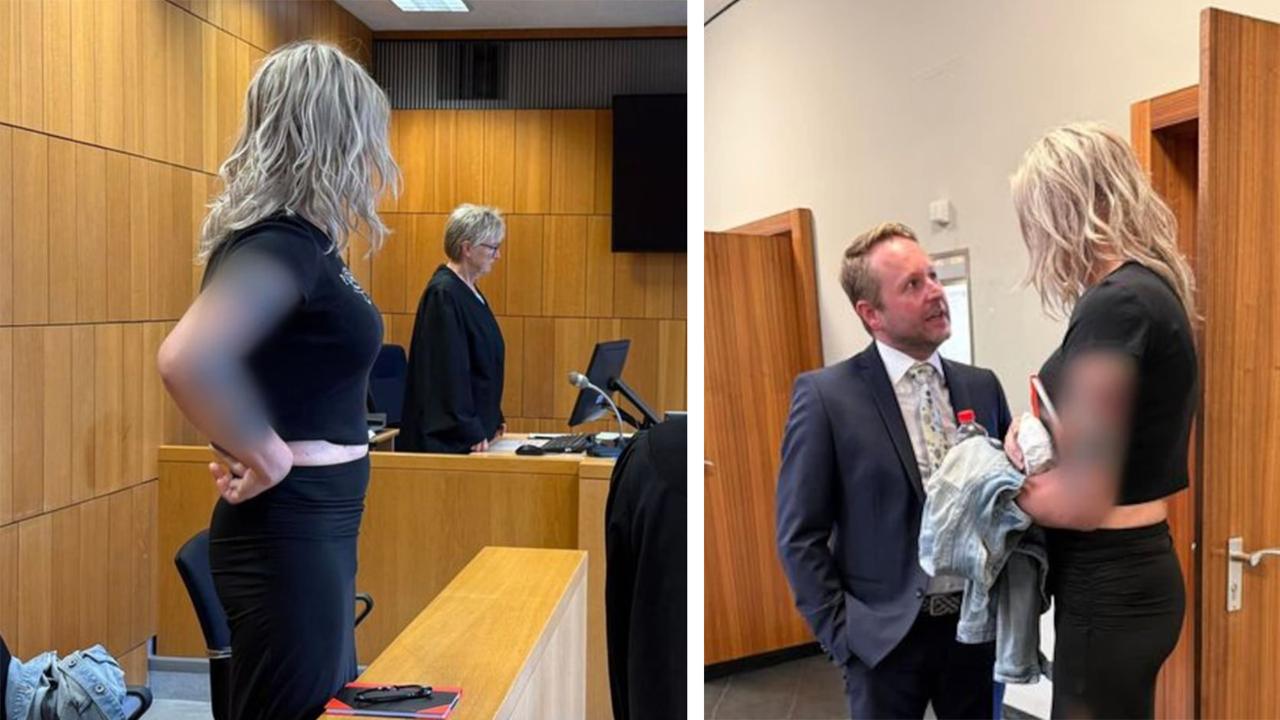
Transgender German federal police officer “Maja S.” has confessed yesterday to the rape of a minor and other serious charges before the Traunstein Regional Court as a part of a plea.

The former officer, who had 35 years of service, admitted to raping a friend’s 14-year-old daughter in the bathroom of a fast-food restaurant in August 2025.

“The injured party was unable to react to this, but stared at the accused in shock,” the court indictment states about the rape. “The accused left the toilet stall and the injured woman locked herself in the toilet, trembling all over her body while suffering from heart palpitations.”

Maja S. confessed to the charges as part of a plea agreement that is expected to result in a sentence of 3 to 3.5 years, according to media reports. Some commentators on social media are already decrying the potential sentence as far too lenient given the gravity of the crimes involved.

Maja S. also confessed to possessing around 2,000 pornographic files depicting brutal assaults and the sexual violence against children, some as young as three.

The transgender former officer also confessed to assault and the sexual abuse of juveniles.

The former officer admitted to producing pornographic videos involving animals, including with other sexual partners and a dog.

According to Bild, the former officer was previously assigned to a special unit of the Federal Police (GSG 9) and was deployed in Afghanistan, among other places. Maja S. continues to receive hormone therapy.

Maja S., who is biologically male, was previously housed in a women’s prison section but is now in the men’s wing of a prison in Munich. Maja’s lawyer has complained that Maja is facing harassment there, including being whistled at by other prisoners.

In addition to the potential prison time, Maja S. must also pay the 14-year-old victim €5,000 and give her a motorcycle. This is the first time Remix News has observed reports of a victim, especially a young victim who cannot even legally ride a motorcycle yet, receiving such a vehicle as part of a plea deal.

Notably, this does not appear to be the first time that Maja S. has offended. Welt newspaper reported that Maja S. must also pay a fine “resulting from a previous, apparently relevant, judgment of the Rosenheim District Court.”

The Welt report notes that the fact that Maja S. reoffended so quickly after this previous verdict from July 2025 was a detrimental factor in this more recent case.

The post Germany: Transgender police officer confesses to raping 14-year-old girl in fast food bathroom, possessing up 2,000 violent child porn files, and producing animal porn appeared first on Remix News.

  •  

Paid Phones

The most recent winner of the National Magazine Award for feature writing describes his turn to payday lending apps when AI gobbled up his livelihood (aka penning promotional web content for business clients). Sharp and darkly funny, the essay chronicles yet another nail in the coffin of the American dream:

Albert founder Yinon Ravid has said that he chose his app’s name for its suggestion of the kind of “smart, unassuming friend” you might come to for financial advice, but today, when I hear the name Albert, I am far more likely to picture an overwhelming force bent on my total destruction, a figure you might spot while being burned alive in a dream—black-robed, pale, teeth bared. When I first joined the app, about eighteen months ago, Albert offered me $25.00. To acquire this loan, I was required to pay an additional fee: A $6.99 instant deposit charge plus the cost of a $19.99-per-month subscription to Albert’s Standard plan, due in one week’s time alongside the full loan repayment. (If I really wanted to make the most of my $25.00, I also had the option of Albert’s $39.99-per-month Genius plan, which, among a very small handful of other talents, can “find restaurants based on your location, or in a specific area.”) On its own, this might’ve been manageable, but, true to the CRL’s findings, Albert’s offerings alone couldn’t keep me afloat, and so I soon signed up for the rest of the payday apps, each one toting its share of instant deposit and subscription fees. (Gallingly, Dave—the only publicly traded company of the bunch, valued at $4.72 billion as of this writing—has the nerve to ask for a tip after each transaction, a move that I suspect even the flintiest strip mall grift artists would dismiss as gauche.)

  •  

Germany: Trans police officer on trial for raping 14-year-old girl in fast food toilet stall, possessing hundreds of child and animal abuse videos

A trans person on trial in the German state of Bavaria on charges that include the alleged rape of a teenage girl and the possession of a large collection of child sexual abuse material while serving as a German police officer.

The trial of the 55-year-old defendant — who is a male-to-female trans person and who has been removed from duty — began today, Tuesday morning, at the Traunstein Regional Court, according to German news outlet Rosenheim24.

Prosecutors accuse the trans ex-officer of raping a 14-year-old girl in the toilet stall of a fast food restaurant and of possessing hundreds of files depicting the sexual abuse of children. Investigators say the material includes violent acts against children, with the youngest victims described as about three years old.

Photos of the trans ex-officer in the courtroom show a tall individual with long bleach-blonde hair, a large arm tattoo, and tall platform shoes.

The defendant also faces an accusation of producing animal pornography. The trans ex-officer is alleged to have made videos where the defendant had sex with a dog, along with several sexual partners. It remains unclear if any of these other individuals have been identified.

The most serious charge concerns an incident in August 2025. Prosecutors say that during an outing with a friend, the defendant raped the friend’s 14-year-old daughter in the restroom of a fast-food restaurant.
The defendant is also accused of sending a pornographic WhatsApp message to the girl, who was roughly 40 years younger than the defendant.

The court has scheduled four days of hearings. A verdict could be delivered on Oct. 8.

The post Germany: Trans police officer on trial for raping 14-year-old girl in fast food toilet stall, possessing hundreds of child and animal abuse videos appeared first on Remix News.

  •  

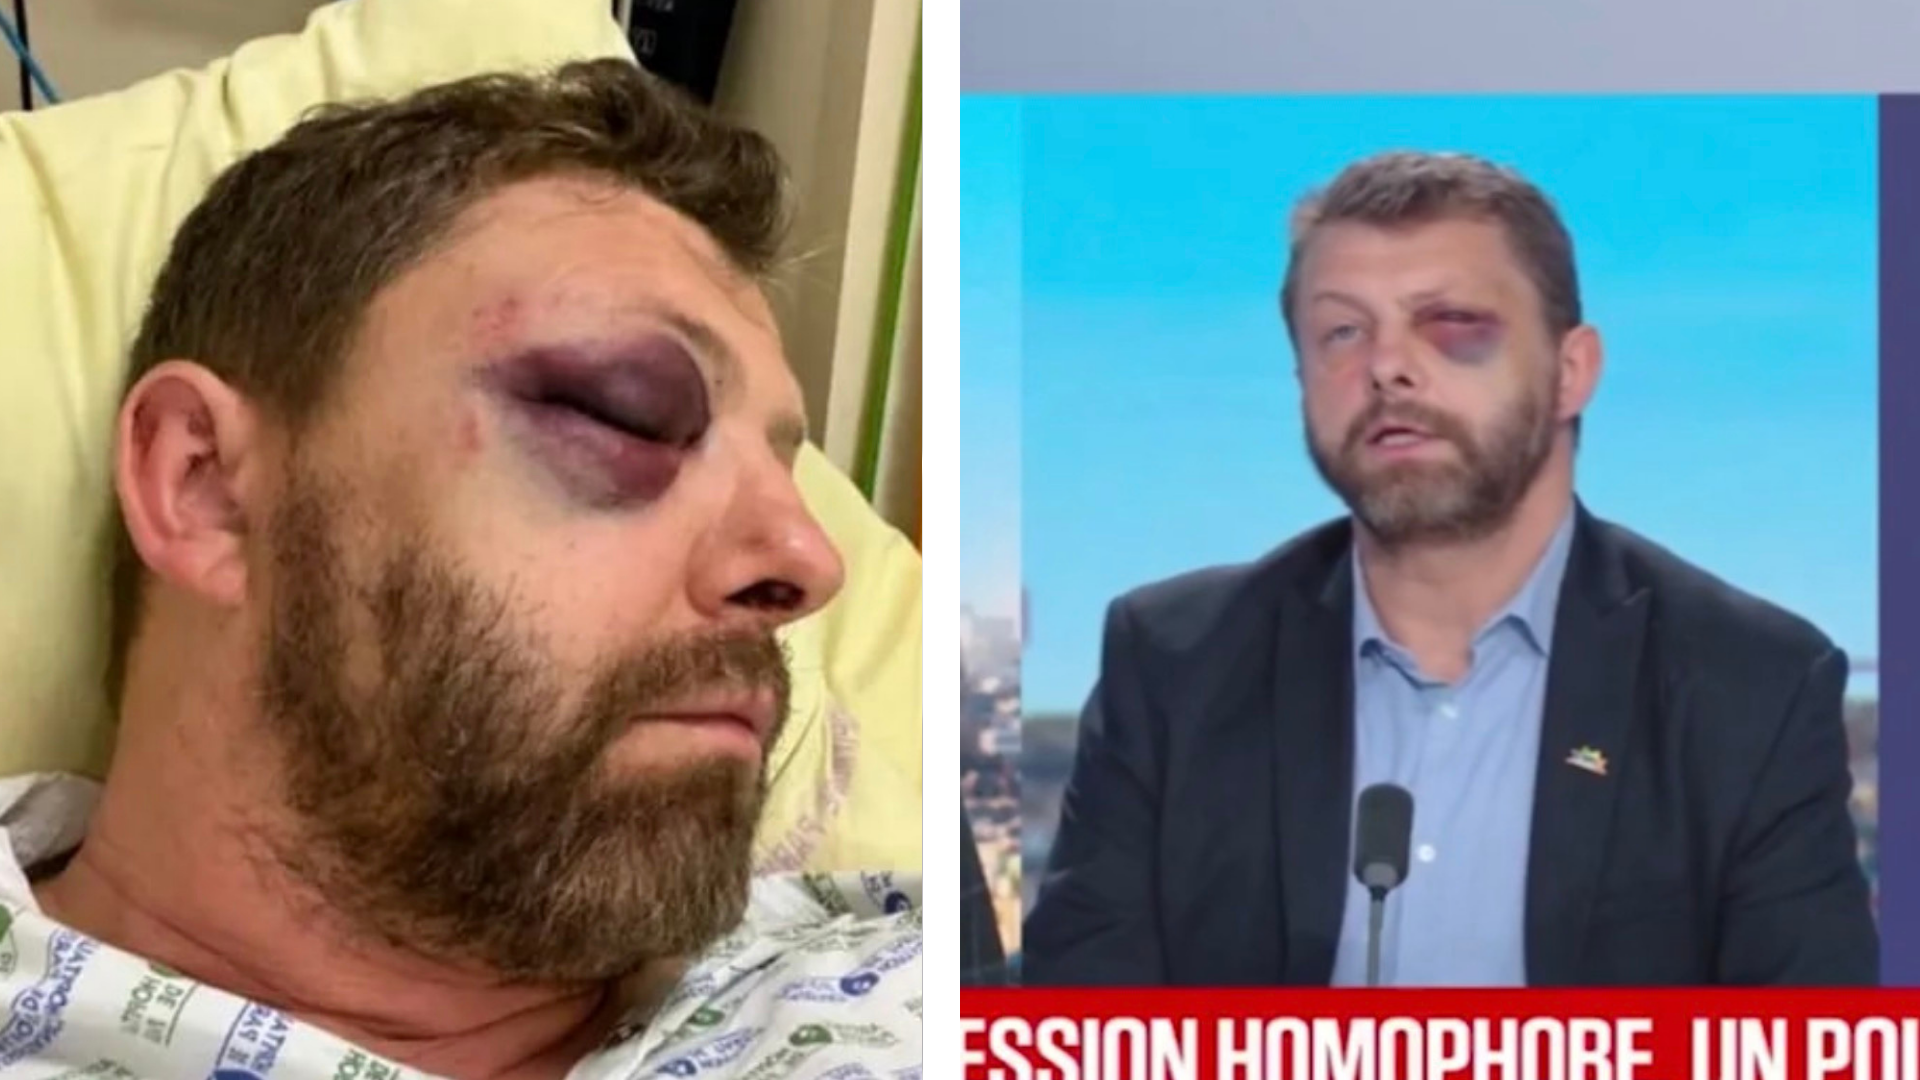
‘I’m going to kill you, you dirty faggot’ – French-Arab suspect severely beats president of LGBT law enforcement association outside Paris bar: report

A French police officer who leads an association for LGBT+ staff in France’s Interior and Justice ministries was beaten outside a bar in the Marais in the early hours of Aug. 29 and left with serious head and facial injuries, prosecutors said. The suspect is reportedly Taha W., a 20-year-old from the multicultural department Seine-Saint-Denis, according to French journalist Amaury Brelet.

Pierre Picavet, president of the FLAG! association, was leaving a bar in the Marais, which has long been a center of Paris’s gay nightlife, at around 4 a.m. when a man confronted him, according to his later account and the Paris prosecutor’s office. The attacker shouted homophobic slurs and threatened to kill him. Picavet said he produced his police identity card more than once and told the man to stop. The assault continued.

“At first I thought it was a joke, then he said, ‘I’m going to kill you, you dirty faggot,’” Picavet told RMC.

“That startled me. I stepped back. He repeated ‘I’m going to kill you’ with a very thick whiskey bottle in his hand,” he added.

Picavet said he tried to dodge blows and punched the man in the mouth. The attacker then struck him in the head with the bottle.

“It bled tremendously. I staggered. I didn’t lose consciousness right away. He went past me, I grabbed him, but he pinned me. The only way I could get free was to bite him. I bit him on the cheek. He threw me to the ground, I hit my head and I passed out,” said the police officer.

Firefighters were already treating him when police arrived. Prosecutors said he suffered internal bleeding, a skull injury described as an open wound, multiple facial fractures and a black eye. He was later given 40 days of total work incapacity.

A witness identified the attacker, who was arrested. The Paris prosecutor’s office opened an investigation for violence causing more than eight days of incapacity, committed because of the victim’s sexual orientation. An investigating judge was later appointed. The case also includes a theft count.

Prosecutors said the suspect, a man born in 2006 with no prior criminal record, was visibly drunk. They cited three aggravating circumstances: the homophobic motive, use of a weapon, and intoxication. He was charged with aggravated violence and released under judicial supervision.

In his complaint, Picavet said the man called him a “dirty faggot” several times. Showing his police card “did not deter the suspect from attacking him,” the prosecutor’s office said.

The empty bottle used in the attack was recovered and placed under seal.

While speaking with the media afterwards, Picavet said: “You have to know that in the neighborhood, there are more and more people coming to mug LGBT people, or beat them, or offer them narcotics… I really hope that it’s isolated and that people will manage to open their minds and not be like that anymore.”

He said that he has been frequenting the neighborhood for 30 years, but stated “yesterday, I went back with fear in my stomach. I went back with fear in my stomach, but I went back.”

Picavet also noted that since Europe’s migration crisis truly took off in 2016, the threat to LGBT people has soared.

“The number of homophobic crimes and offenses has tripled since 2016. Tripled! 4,900 homophobic assaults last year!” he stated.

The association Stop Homophobie called the attack a homophobic assault and published photographs of Picavet’s injuries that he sent from hospital. Paris Mayor Emmanuel Grégoire condemned what he described as an “odious homophobic attack” in the heart of the capital and offered support to the FLAG! president.

Speaking on France Inter after the assault, Picavet said he was “particularly shocked,” but added that the episode showed “there is still work to do.” He said: “When I get better, when I have healed my wounds, I will continue the fight.”

FLAG! represents LGBT+ personnel in the Interior and Justice ministries and campaigns against anti-LGBT discrimination and violence.

The post ‘I’m going to kill you, you dirty faggot’ – French-Arab suspect severely beats president of LGBT law enforcement association outside Paris bar: report appeared first on Remix News.

  •  

Fitch assigns Pakistan’s proposed dollar bond ‘B-‘ rating

KARACHI: Fitch Ratings has assigned a ‘B-‘ rating to Pakistan’s proposed U.S. dollar-denominated bond, with a Recovery Rating of ‘RR4,’ the ratings agency announced. Pakistan plans to use proceeds from the bond for general budgetary and sovereign financing purposes, according to Fitch. The bond rating is aligned with Pakistan’s Long-Term Foreign-Currency Issuer Default Rating, while ... Read more

The post Fitch assigns Pakistan’s proposed dollar bond ‘B-‘ rating appeared first on BOL News.

  •  

Pakistan returns to spot LNG market with fresh tender as power generation takes a hit

KARACHI: State-run Pakistan LNG Limited (PLL) has issued a fresh tender to procure one spot cargo of liquefied natural gas for delivery between September 4 and 8, as global supply disruptions stemming from the Middle East war continue to strain the country’s gas-fired power generation. PLL invited bids from international suppliers for a single cargo ... Read more

The post Pakistan returns to spot LNG market with fresh tender as power generation takes a hit appeared first on BOL News.

  •  

AfD-linked influencer Naomi Seibt prepares new media network with US government funding

German influencer Naomi Seibt, who is affiliated with the Alternative for Germany (AfD) party, is preparing to launch a media network called the “Freedom Alliance of the West (FAW)” using money from the U.S. government, according to a report in the Düsseldorf newspaper Handelsblatt.

The 25-year-old, who applied for asylum in the United States last year and lives there most of the time, aims to finance the project through a $4.9 million fund. The Trump administration created the fund to support European organizations that campaign “against censorship” and address the “consequences of mass migration.”

Seibt’s plans include creating a social media channel and broadcaster called “Freedom TV.” She has said she wants to collaborate on the project “with alternative media and polling institutes” as well as “with European lawyers representing freedom of expression cases.”

Seibt has garnered a large audience on X and has remained critical of mass immigration. As she rose to prominence, she said she became a target of surveillance by German authorities, including the powerful domestic spy agency the Federal Office for the Protection of the Constitution (BfV).

In a post on X where she discussed being a surveillance target, she said she also feared “state media defamation, and Antifa threats.”

I AM SEEKING ASYLUM IN THE U.S. 🇩🇪🇺🇸

My name is Naomi Seibt,

I am the 1st German applying for asylum under President Trump due to political persecution.

As a free speech advocate and supporter of the AfD party, I am the target of
• intelligence surveillance
• state media… pic.twitter.com/rdsj4Qg4BB

— Naomi Seibt (@NaomiSeibt) October 29, 2025

X and Tesla owner Elon Musk has openly supported Seibt on his platform, including retweeting her videos and commenting on her posts.

Remarkably, Handelsblatt is outraged that Seibt is receiving any money at all, despite left-wing causes receiving hundreds of millions through German and European Union government sources, not to mention wealthy donors like George Soros.

The German government also appears to be taking issue.

“As Handelsblatt learned, the Foreign Office in Berlin is dealing with the design and motivation of the fund. In July, Chancellor Friedrich Merz (CDU) criticized the fact that financial interventions from abroad constituted an impermissible interference in the democratic process,” wrote the financial newspaper.

The post AfD-linked influencer Naomi Seibt prepares new media network with US government funding appeared first on Remix News.

  •  

France: Public Debt Surges Past €3.5 Trillion, Raising Serious Concerns

The Ministry of Finance in Paris (Bercy). Jean-François Gornet / Flickr, CC BY-SA

The Ministry of Finance in Paris (Bercy). Jean-François Gornet / Flickr, CC BY-SA

France has crossed a critical threshold as its public debt exceeded €3.5 trillion in the first quarter of 2026, reaching 117.5% of GDP. The French Court of Auditors has sounded the alarm over what it describes as an “alarming” fiscal situation, as public deficits hit record levels and debt-interest costs continue to soar.

The Ministry of Finance in Paris (Bercy). Jean-François Gornet / Flickr, CC BY-SA

Public Debt Exceeds €3.5 Trillion

During the first quarter of 2026, France’s public debt passed the symbolic milestone of €3.5 trillion, reaching €3.5361 trillion at the end of March. The figure underscores the scale of the country’s budgetary challenges.
To put this amount into perspective, France would theoretically have to sell its entire gold reserve, all publicly traded and privately held state assets—including companies such as EDF, Engie, and Airbus—as well as all government-owned buildings and land in an attempt to repay the debt in a single payment. Even such a drastic measure would likely fall short.

In just one quarter, France’s Maastricht-defined public debt increased by €75.6 billion, a sharp rise in a very short period. This growing debt burden reflects a longstanding reality: for more than fifty years, the French government, local authorities, and social security system have collectively spent more each year than they have collected in revenue, particularly through taxation. To cover this structural gap, France has continued borrowing from financial markets.

Debt-to-GDP Ratio Nears Historic High

Beyond the headline figure, analysts and financial institutions are particularly concerned about debt relative to economic output. According to France’s National Institute of Statistics and Economic Studies (INSEE), public debt now equals 117.5% of gross domestic product.

The increase has been dramatic. In 1980, public debt represented only 20% of GDP. By 2000, it had risen to approximately 60%. Over four decades, the debt-to-GDP ratio has nearly increased sixfold.

The current level of 117.5% is approaching the all-time record of 117.8% recorded in the first quarter of 2021 during the COVID-19 pandemic. At that time, President Emmanuel Macron launched an unprecedented economic rescue effort, pledging to spend “whatever it takes” to prevent economic collapse.

Although the health crisis has long since passed, France’s debt trajectory has not slowed significantly. Within the European Union, only Greece and Italy have higher debt ratios, making France the third most indebted country in Europe.

Warnings from the Court of Auditors

In response to what it views as a critical situation, France’s independent Court of Auditors, responsible for overseeing public finances, issued a warning report describing the state of the nation’s finances as “alarming.”

The report, revealed by France Inter and released ten months before the 2027 elections, calls for “strong, credible, and swift measures” to restore fiscal stability.

The court highlights several aggravating factors. First, France remains the only country in the eurozone whose debt level is higher today than it was at the end of the COVID-19 crisis. Second, public deficits continue to break records. France posted a budget deficit equal to 5.1% of GDP in 2025, the second-highest in the eurozone after Italy.

The government’s goal of keeping the deficit at 5% is viewed as unrealistic by the Court of Auditors, which fears a further deterioration of public finances.

Debt-Interest Costs Are Soaring

A particularly troubling development is the rapid increase in debt-servicing costs. As debt accumulates and interest rates rise in financial markets, the amount spent on interest payments has grown dramatically.

In the current state budget, debt-servicing expenses have become the government’s single largest expenditure category, surpassing spending on the national education system (excluding pension obligations).

Paradoxically, this situation coincides with a significant increase in taxation. Taxes rose by €38 billion across 2025 and 2026 as part of efforts to limit further deficit growth. Yet France already has the highest overall tax burden in Europe when taxes and social contributions are combined.

This creates both political and economic tensions: higher taxes have not been sufficient to slow the growth of public debt, raising questions about the effectiveness of current fiscal measures.

Structural Challenges Extend Beyond Short-Term Solutions

France’s current trajectory highlights a troubling economic reality: structural public spending is growing faster than tax revenues, creating a persistent deficit that is difficult to eliminate.

Programs such as social welfare, pensions, healthcare, and public investment involve long-term commitments, while tax revenues tend to fluctuate with economic conditions.

This divergence between economic growth and debt growth raises a fundamental question for France’s public finances. If GDP expands by only 1% to 2% annually while debt continues to grow by 3% to 4% per year, the debt-to-GDP ratio will inevitably continue rising unless major policy changes are implemented.

French voters heading to the polls in 2027 will likely face a difficult choice between maintaining current levels of public services and restoring fiscal sustainability.

Breaking the Debt Spiral

To reverse the trend, experts and institutions such as the Court of Auditors recommend a combination of measures: controlling the growth of public spending, improving the efficiency of existing expenditures, broadening the tax base without increasing marginal tax rates, and accelerating economic growth to boost revenues.

As the eurozone’s second-largest economy after Germany, France possesses significant economic resources. However, meaningful structural reforms will require political consensus and a willingness to accept difficult compromises.

In the short term, the government must demonstrate that its deficit-reduction commitments are credible. In the medium term, comprehensive reforms of public spending—particularly in pensions and healthcare—appear unavoidable. Over the long term, only sustained economic growth combined with spending discipline will be capable of reversing the debt dynamics that have characterized France for decades.

L’article France: Public Debt Surges Past €3.5 Trillion, Raising Serious Concerns est apparu en premier sur FrenchDailyNews.

  •  
❌