Governor Yaron urges next coalition to cut debt and pursue growth reforms to fund security needs; bank raises forecasts but warns overseas production distorts domestic picture
Ahead of election, former central bank deputy governor Zvi Eckstein says outgoing government's decisions have impacted country's growth, with economy at risk unless changes are made
The federal government just closed fiscal year 2026 with a deficit of nearly $2 trillion, according to figures the Congressional Budget Office (CBO) released last Thursday. Only the two pandemic years of 2020 and 2021 were worse. Today, though, there is no recession and no emergency. These enormous budget deficits are the new normal.
The usual response to a deficit warning is that the government just needs more money. It doesn't. Thanks to the remarkable strength of the private sector, federal revenue rose by 3 percent, to more than $5.4 trillion, over the fiscal year. But spending rose by 6 percent, reaching $7.4 trillion.
Some will blame the Supreme Court for striking down most of President Donald Trump's tariffs and forcing the government to issue refunds. But even if Washington had kept the $130 billion in illegal levies, it would cover less than one-tenth of the gap. Tariffs were never a serious revenue source at our insanely high level of spending.
Look at where the money went. Spending on the three main entitlement programs—Social Security, Medicare and Medicaid—grew by 7 percent. That's faster than total spending growth. Defense grew by 5 percent. Interest on the debt rose by 11 percent, exceeding $1.1 trillion. That last figure is the bill for every earlier year of borrowing—years when Washington was sending clear signals that it isn't serious about fiscal responsibility.
If you want to see where such irresponsibility can lead, look at France. The country that big spenders from Paul Krugman to Sen. Bernie Sanders (I–Vt.) have cited as proof that big government is viable and full of upsides is now on the brink of a serious crisis. France's debt equals 120 percent of its gross domestic product (GDP), and interest payments are rising quickly. Slow growth and social unrest aren't helping.
The U.S., of course, has some advantages that France doesn't, largely because we're a country of innovators with a private sector unmatched at creating wealth. Nonetheless, debt that is swelling out of control should still worry us. First, the same anti-wealth and anti-growth forces that brought France to where it is now are gaining popularity here. Second, we too will see debt reach 120 percent of GDP in a few years, and our interest payments are already consuming an alarming share of resources.
A wise Congress would put us on safer footing if only because debt raises interest rates for everyone, from homebuyers to small businesses. This operates as a drag on growth, and hence on wages. In other words, controlling debt should be part of an affordability agenda in the same way as streamlining regulation.
When legislators decide to take affordability seriously, I recommend looking at a September Advancing American Freedom (AAF) report on this topic. Its section on fiscal restraint offers a useful menu of reforms, including targeting the programs that most drive the debt.
Start with Social Security. Under current law, benefits will be cut by roughly 20 percent when the program's trust fund runs dry in the early 2030s. Nobody believes Congress will actually let that happen, but we'd better hope its answer isn't to double down by borrowing the difference between payroll taxes and benefits.
Nor are tax increases an option. The payroll tax meant to fund entitlements is now 12.4 percent of wages. It began at 2 percent when Social Security was first rolled out. It is also the most burdensome tax for many Americans. Enough already. The fixes AAF fellow Rachel Greszler proposes are worth considering: Index the retirement age to life expectancy, use an accurate inflation measure for cost-of-living adjustments, and move gradually toward a flat universal benefit that protects lower-income retirees while ending Social Security's de facto welfare for the wealthiest.
Next is Medicare. More than 40 percent of its financing already comes from general revenue rather than from payroll taxes. The report recommends converting the program to premium support, giving beneficiaries a fixed contribution to spend on traditional Medicare or on competing private plans. It would also raise the eligibility age to 67, matching Social Security, and trim subsidies for well-off seniors. That's a start.
As for Medicaid, the problem is one of pricing. And yet competition based on price—the best cost-control tool—has never been seriously tried. Washington covers 90 percent of the cost of states' expanded Medicaid programs for adults. A state can buy a dollar of spending with just a dime of its own money. Changing the states' incentives would be key here. Implementing risk-adjusted per-capita caps, through which the federal government would give states a fixed amount per enrollee, would do just that. States would pay for their own inefficiencies or would be able to use every dollar they save by becoming more efficient.
The same logic supports returning more welfare programs to states, starting with the federal share of the Supplemental Nutrition Assistance Program. State governments have to balance their budgets in some form.
None of these reforms are painless. But the alternatives will prove far more painful. The U.S. will either continue paying a slow, unlegislated tax called inflation or face a fast, ugly fiscal crisis when bond buyers stop giving Washington the benefit of the doubt.
Russia suffered vastly more casualties than Ukraine in September, a senior NATO military official told Bloomberg. Ukraine’s General Staff put the month’s Russian toll only slightly lower.
September’s toll lands on a recruitment system that was already falling short. Ukraine’s military intelligence (HUR) estimated that Russian losses outran new contracts in June and July, when monthly losses ran lower. In August, Ukrainian President Volodymyr Zelenskyy, citing military intelligence, warned that Russia is preparing a mass call-up after its parliamentary elections. That vote ended on 20 September.
Where the numbers come from
Russian casualties passed 50,000 in September, up to 28,000 of them killed, the official said. Ukraine’s losses over the same month came to about 5,000, according to the official, who spoke on condition of anonymity. Russia does not release casualty figures, Bloomberg noted. In late August, Pavlo Palisa, deputy head of Ukraine’s Presidential Office, put Russia’s July losses at 43,000 killed and wounded. Bloomberg could not confirm his figures.
To push forward, Russia keeps feeding troops into “kill zones,” the official said. These are stretches of ground saturated with armed drones, mines, and artillery fire. Maksym, call sign Rumyn, is a deputy company commander in the 46th Airmobile Brigade’s drone battalion. In April, he said the zone once ran 3–5 km deep and is now several times larger.
Explore further
Ukraine suffered 10 times fewer casualties than Russia in Vivaldi counteroffensive, veteran says. Ukraine’s innovations in drone and ground robot tactics are changing frontline warfare
Rising stakes for Moscow
Russia’s defense spending is expected to near $199 billion this year, Bloomberg reported, citing two sources close to the government. That is about 40% above the plan the government set in late 2025.
Russian President Vladimir Putin would struggle to wind down the invasion without a political cost, Martin Jäger said last week. He heads Germany’s Federal Intelligence Service (BND).
An analysis published on Wednesday by ABC News estimated that companies backed financially by Donald Trump Jr. and Eric Trump have so far scored more than $6 billion in contracts from the US Department of Defense. As ABC documented, many of the investments into the defense firms come through 1789 Capital, a venture capital firm […]
More than 50 Russian companies could default on their bonds this year, the most since 2009, a rating-agency analyst told Russian newspaper Izvestia, which reported it on 6 October.
Russia's wartime economy is straining under high interest rates, and the budget is too: the 2026 deficit has nearly doubled from the earlier forecast to a record $88 billion, with more deficits planned for the next three years as Moscow raises taxes to fund the war and plans its biggest defense budget since the full-scale invasion began.
A default is a situation in which a company cannot make promised interest payments to investors on time or repay borrowed money. If a payment is not made by the agreed deadline, the company becomes delinquent, which under certain conditions is recognized as a default.
So far this year, 20 companies have defaulted for the first time, compared with 24 in all of 2025, said Mikhail Nikonov of the Expert RA rating agency. Most of the companies that missed payments are small issuers of high-yield bonds, Izvestia reported.
In 2026, Russian companies have missed payments totaling 41 billion rubles (about $490 million), compared with 34 billion rubles (about $410 million) the previous year, according to investment bank Sinara.
Russia faces a new wave of corporate defaults
By the end of 2026, the number of Russian companies unable to service their ruble-denominated debt on time could reach 40–50, the highest level since 2010, said Pavel Zholobov, junior managing director at the NRA rating agency.
The number of bond defaults in 2026 has already reached its highest level in a decade, Zholobov said. Similar figures were recorded in the mid-2010s: in 2014, 35 companies missed payments; in 2015, 52 did so; and in 2016, there were 44 issuers. This occurred in part after Western sanctions were imposed on Russia over its annexation of Crimea and its war in Donbas, as well as amid a halving of oil prices and a sharp weakening of the ruble.
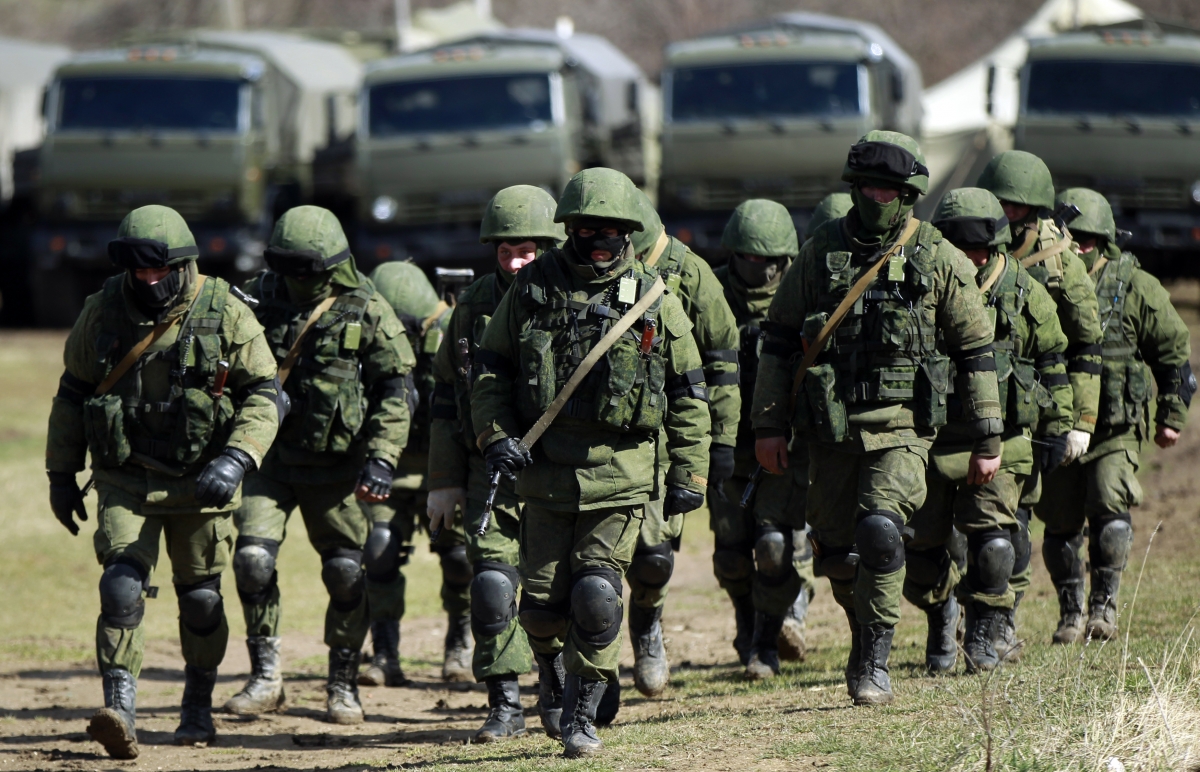
So-called "little green men" (the Russian occupation troops comprised special forces who removed insignia, wear face masks to prevent identification and call themselves a "Crimean self-defense force") surround a Ukrainian military base in Perevalne, Crimea, during the Russian annexation of the peninsula in February-March 2014.
There were more defaults only in 2009. At the time, amid the fallout from the global financial crisis, more than 100 issuers faced payment problems, while the volume of distressed debt reached nearly 200 billion rubles, Zholobov noted.
High interest rates put pressure on companies
This time, the main reason for companies' difficulties in making bond payments has been the prolonged period of high interest rates, which has continued since 2023. Companies are raising financing at high interest rates but are unable to refinance their debt on more favorable terms, explained Ekaterina Sidorova, head of the Foreign Exchange, Commodities and Debt Markets Department at SberCIB Investment Research.
At the same time, the situation does not yet resemble a systemic debt crisis: defaults are primarily being recorded among companies with low credit ratings and high debt burdens, Sidorova said.
If a company fails to repay bond debt, it is given 10 business days to meet its obligations. If it fails to do so, the company may offer investors a restructuring—for example, by postponing payments in exchange for a higher interest rate.
The number of defaults will remain high in 2027, Sidorova believes.
High interest rates were a response to accelerating inflation in Russia. Domestic demand was outpacing production, Russia's Central Bank said in October 2023. Sanctions over the war and rising defense spending had also hit the economy and the ruble, which had lost about 25% against the dollar that year. The bank raised its key rate from 7.5% in the first half of 2023 to 15% by the fall.
Ukraine targets Russia's oil industry to weaken its war economy
Ukraine is also seeking to weaken Russia's economy as part of efforts to reduce its ability to finance the war. In particular, Defense Minister Yevhenii Khmara said strikes on oil refineries are aimed at "bleeding the Russian war machine" and destroying its military and economic potential. According to the ministry, the attacks have knocked out more than 51% of Russia's oil refining capacity.
In the first half of July, Russian oil refineries processed about 3.9 million barrels of oil per day—the lowest level since March 2005. Due to the production cuts, Moscow was also forced to restrict fuel exports.
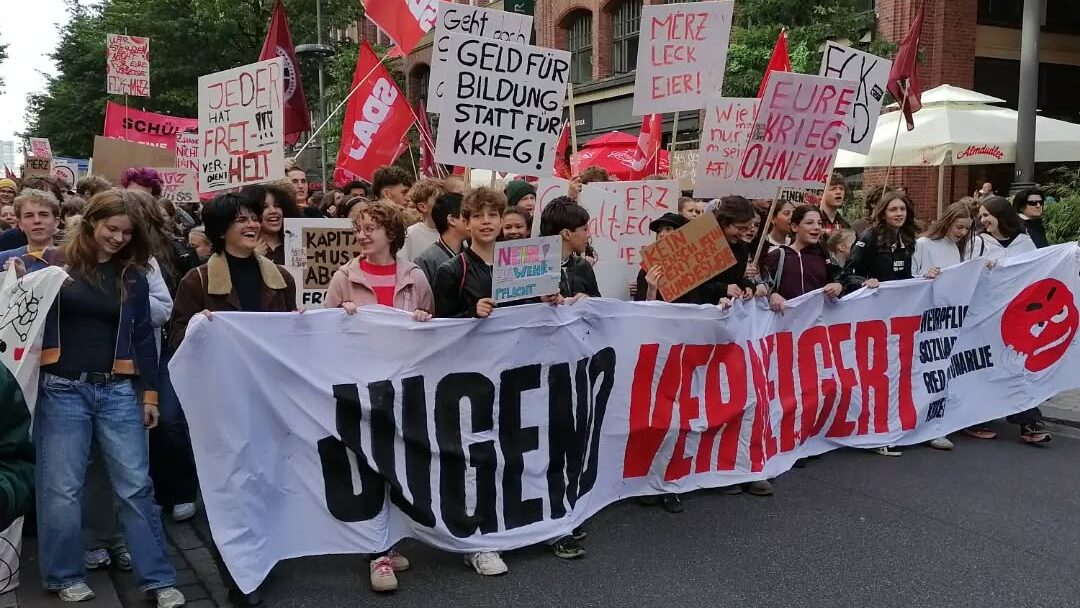
Thousands of students across Germany were once again on strike against conscription and militarization on Friday, September 25. Actions took place in at least 100 localities as young people demanded a sharp turn from the government’s chosen path.
“We don’t want to be forced into military service and we don’t want to go to war,” the students wrote in declaration after their last strike in May.
This is the fourth time students have exchanged classrooms for streets since the end of 2025. The mobilization has strengthened in resistance to the Merz administration’s plans to build the “strongest conventional army in Europe” – including by drawing more people into the Bundeswehr, the German armed forces.
While authorities insist military recruitment remains voluntary, students have warned of a clear tendency toward outright conscription. Local strike committees and activists also emphasized the widespread repression ahead of actions. This included scheduling of exams on strike days and locking-in students on school grounds, they pointed out.
Billions for the Bundeswehr, cuts for schools and youth services
Over recent months, the government has sent thousands of questionnaires to map voluntary interest in joining the armed forces. According to German media, the response has been underwhelming: tens of thousands of students have disclaimed no interest whatsoever. Not even a multi-million-euro budget allocated to promoting the army has been able to shake this opinion.
“They sell us war service as an ‘adventure’ while we know that what awaits us is coertion, humiliation, sexism, right-wing extremism, and racism,” the student declaration adds.
Instead of taking the message seriously, authorities recently advanced the implementation of medical checks among their targeted population, drawing further frustration from students.
“We don’t want compulsory questionnaires, fines, draft physical examinations, conscription assessment centres across the country, nor planned integration of the Federal Volunteer Service into military service,” they wrote. “These are means to prepare the reintroduction of the draft and thus another war originating from Germany.”
“In case of conscription, we’ll be trained as cannon fodder, forced into the trenches,” students added. “War costs us our lives, while corporations like Rheinmetall make record profits.”
Students on strike have expressed solidarity with other ongoing struggles against militarization and budget cuts. They stated they would join peace demonstrations planned for early October in Berlin and Stuttgart, as well as a trade union-backed mobilization against budget cuts on Saturday, September 26.
Their decision reflects the widespread understanding that youth and education services are among those impacted by this round of austerity. According to junge Welt, the federal ministry responsible for education will face close to €1 billion in cuts – while €140 billion will be made available for so-called defense in 2027.
“Every tank, every rocket we pay for with dilapidated schools and social cuts,” students remarked.

 Login