❌

Reading view

Peter Pan Tariffs for Companies That Never Grow Up
A green tinted background of U.S. paper money with a businessman standing on it who has a shadow that looks like Peter Pan | Illustration: Patrick Bryk/Dreamstime./Midjourney

Of all the arguments for protectionism, the infant industry argument probably has the strongest theoretical appeal. By protecting a new industry from its more developed foreign competition, the story goes, tariffs give domestic producers the time to grow, learn, and become efficient enough to stand on their own. Domestic consumers feel the short-term pains of higher prices, but they enjoy the long-term gains of job growth and lower prices as the new industry blossoms.

It's no secret that tariffs have driven significant price increases over the last year and a half. A study from the New York Federal Reserve finds that tariffs "contributed 2.9 percentage points to goods price inflation" and that without tariffs those prices would have slightly declined. Tariff defenders, looking for a new reason to claim these higher prices are only temporary, have reimagined the infant industry argument. Now it's being used to support trade barriers in industries that are over a century old, but the promise is exactly the same: Domestic firms need the protection so they can compete, innovate, and cut costs until prices come back down even further than they were before the tariffs.

Michael Brendan Dougherty recently made such an argument in National Review, arguing that "tariffs can, over time, bring prices below where they started." When economist Don Boudreaux called the argument "bizarre," Dougherty replied that critics had failed to acknowledge the dynamic process by which markets respond to tariffs "by adapting and cutting costs." Although he is light on specific details, he posits that the changed incentives of a "paradigm shift" in tariff policy will spur domestic competition, leading to the theorized price reduction. Of course, firms would still respond to the dynamic processes of domestic competition without a tariff wall, but the point stands.

From there, the reworked infant industry argument becomes the standard version advanced more than two centuries ago by Alexander Hamilton and his disciple Friedrich List. When Hamilton made this claim in 1791, his argument may have seemed suitable for a new nation seeking to firm up its economy and security against established European powers.

Others at the time pointed out that special interest groups—a manifestation of the "violence of faction" so thoroughly dissected in the Federalist Papers—had already begun to coalesce around the fledgling iron industry in Pennsylvania, clamoring for protective tariffs. Two years earlier, James Madison had warned about a "premature policy of stimulating manufactures" driving tariffs too high. In the end, Hamilton recommended and Congress enacted a far more moderate tariff schedule than his theoretical musings portended. American iron manufacturers received a consolation prize of a higher tariff on their competitors than the rate for most general imports. Hamiltonians have been touting the infant industry argument ever since.

Nearly 250 years later, those same infants apparently have yet to advance into adulthood. Steel, the direct successor to the founding-era iron manufacturers, remains a singular focus of President Donald Trump's protectionist tariff policies, just as it was under former President Joe Biden. And former President George W. Bush before him. Indeed, steel has been a recurring beneficiary of protectionism for most of America's existence.

This extended period of protectionist infancy suggests that the argument needs a new name. We propose the "Peter Pan industry argument" for companies that never grow up because tariffs make sure they never have to.

The question tariff advocates rarely ask is: Why do some American producers have higher costs than foreign rivals even in the face of lower-cost foreign competition? The answer comes down to specific rules and choices within particular firms and industries. Tariffs, and protectionism in general, address none of these. No industry illustrates this like steel, but it is far from the only one.

In 1947, United Steelworkers won a contract provision known as Section 2-B. Among other things, this barred mill managers from changing established work practices unless new technology required it. Steel companies tried to get rid of this in 1959, finding it difficult (given union incentives) to establish that technology required change. In response, 500,000 steelworkers went on strike for 116 days. This strike sent buyers abroad, causing 1959 to be the first year the U.S. imported more steel than it exported. One of the then-new technologies that was delayed was basic oxygen furnaces, which could produce steel far faster and cheaper than the open-hearth furnaces that were so common. In 1965, only about 17 percent of steel made in the U.S. was made using the basic oxygen furnace. Japan produced 55 percent of its steel with this faster, more efficient method.

Change finally came from a steel customer. Vulcraft, a maker of steel joists, grew tired of paying Big Steel's prices and waiting for Big Steel's deliveries. In 1969, free from steel unions and preconceived notions, the company looked for new steel-producing technologies and found the answer in the electric arc furnaces that had been adopted in much of the world throughout the 1950s and '60s. Vulcraft's parent company later renamed itself Nucor, and minimills like the ones it pioneered now make most of America's steel.

So the modern steel industry was built by a frustrated steel buyer who found a way around protected companies. In other words, the U.S. steel industry has lagged behind the technologies found around the world.

We could go on, but the broad point here is that the "relatively higher domestic production costs that made the tariff 'necessary' in the first place," as one critic put it, are often the result of preventing competition in the first place. It's odd to suggest that further preventing competition through tariffs will somehow alleviate the ills of already-prevented competition.

Tariff advocates fail to acknowledge that the ability to import steel also comes with the benefit of access to cheaper steel for steel-using industries, such as manufacturing. A 50 percent tariff on steel further closes the release valve that imported steel offers. Buyers of steel are then left to purchase more of the more expensive domestic steel. Because new steel mills take years to bring online, this causes delays and longer delivery times for manufacturers.

We don't have to wonder what happens when a country lowers its tariffs on materials used by manufacturers. India did this in the '90s, and researchers found that newly available inputs accounted for 31 percent of the new products that Indian manufacturers introduced. And what happens when the U.S. imposes tariffs on steel? Downstream U.S. firms become less competitive. This is why American businesses clamor for exemptions to tariffs, especially for tariffs on materials like steel.

Perhaps all this could be forgiven if tariffs advanced national security concerns, as tariff advocates assert. They point out that an adversarial nation could cut off supplies of critical materials during wartime and cripple America's ability to defend itself. Unfortunately, tariffs fail there too.

First, this conflates production with access. While domestic production does ensure domestic access, access can be secured without production. In the case of steel, the Commerce Department reports that in 2025, the U.S. imported steel from 79 countries, with Canada being our top foreign supplier. The top 10 sources of steel are responsible for 77.8 percent of America's steel imports. None of those countries were considered adversaries—at least not until the tariff crusades pushed these friends away. What's more, according to the American Iron and Steel Institute, only 23 percent of finished steel in the U.S. was imported in 2024. Far from being exposed to foreign states' whims, American access to steel is incredibly resilient.

Second, this view ignores the positive effects of trade and globalization on national security. The Center for Strategic & International Studies finds that increased trade between countries reduces the likelihood that they'll go to war against one another. Globalization helps ensure that domestic access continues unabated should war break out, thanks to the diversity of trading partners.

When Hamilton made the infant industry argument, he at least assured us that the industry would at some point advance to adulthood and stand on its own. Steel, like so many other Peter Pan industries, has proven Madison right. These industries have refused to grow up, and it's time to stop pretending that tariffs will fix that.

The post Peter Pan Tariffs for Companies That Never Grow Up appeared first on Reason Magazine.
  •  

Saudi oil boss issues global supply warning

RT | October 22, 2026

The US-Israeli war on Iran has caused an “unprecedented” shock to global energy markets, removing some 3 billion barrels of oil supply, Saudi Aramco CEO Amin Nasser has warned.

The war launched in February effectively shut the Strait of Hormuz, a crucial oil and LNG artery, sending crude prices up roughly 50%. Despite Gulf exports recovering to a reported 80% of pre-war levels, renewed attacks on vessels have kept markets on edge, with Brent hitting a five-month high above $112 this week. Houthi attacks on Saudi energy infrastructure and shipping have compounded the crisis, threatening another vital trade chokepoint, the Red Sea’s Bab el-Mandeb Strait.

In an interview with Al Arabiya Business aired on Thursday, Nasser said the nearly eight-month crisis had deprived global markets of an estimated 3 billion barrels of oil.

“The impact of this crisis on energy markets is unprecedented,” he said. “We have lost around 3 billion barrels since it began. And bear in mind that the Gulf accounts for roughly 20% of global oil demand.”

The figure is equivalent to nearly a month of global oil consumption and reflects cumulative supply losses caused by disrupted shipping, reduced production and logistical bottlenecks.

With global oil inventories already below their five-year average when the war erupted, prices could have soared past $200 a barrel, Nasser warned. He credited emergency reserve releases, China’s sharp cut in seaborne oil imports and Saudi Aramco’s East-West pipeline, which bypasses Hormuz, with averting an even more severe price shock.

Nasser warned, however, that even an end to the crisis could bring fresh pressure on oil markets, as recovering consumption and a rush to replenish depleted reserves will likely fuel another demand surge.

“Once things return to normal, we expect additional demand of around 3 million barrels per day – about 2 million from consumption growth and another 1 million just to replenish the reserves countries have drawn down during the crisis,” he said, noting that the added demand could keep markets under strain long after shipping routes reopen.
Fresh escalation fears

Meanwhile, fears of another escalation are growing as US-Iran talks remain deadlocked. Reports on Wednesday claimed Washington was quietly pulling troops from bases in Jordan, Qatar and Kuwait, evacuating some diplomats and their families from Saudi Arabia and preparing similar withdrawals elsewhere. Similar precautions were taken ahead of the US-Israeli strikes on Iran on February 28.

The moves follow US President Donald Trump’s rejection last month of Tehran’s proposal to reopen Hormuz in exchange for lifting the US blockade of Iranian ports, easing oil export restrictions, unfreezing Iranian assets and ending regional hostilities, including Israeli operations in Gaza and Lebanon.

Washington and Israel have since reportedly discussed another major offensive, potentially soon after the November 3 US midterms. Israeli Prime Minister Benjamin Netanyahu has also openly threatened fresh strikes on Iran, even without US backing.

  •  

Kicking the Ladder: How the Modern Monetary Order Unlearned Its Own History. Part 2

Part I traced a system built on the advice of four economists; even know their theories are not theology. The next half-century is a case study in what happens when that advice – however flawed – is abandoned, and in what happens to the few countries that never got the memo. Part II: Dismantling the […]
  •  

Riyadh Says Its Oil System Is Intact. The Numbers Say Otherwise.

By Larry C. Johnson | SONAR21 | October 22, 2026 

Earlier this month, Aramco’s chief executive, Amin Nasser, assured the markets that “our system is intact” and that Saudi Arabia could restore its full 12 million barrels a day of capacity within days. It is a comforting message, and Washington, European capitals and oil traders have every reason to want to believe it. It is not true.

Karl Miller has just completed a 37-slide operating assessment of Saudi Arabia’s energy system, covering everything from the oil fields to the fuel depots, as of October 20. I have read it closely. It is the most careful accounting of this damage I have seen, and it is careful in a way that should worry anyone counting on Saudi oil this winter. Miller does not count Houthi boasts, social-media videos or plumes of smoke as damage. He separates confirmed hits from claims, and he refuses to add up the design capacity of every facility that was struck as if it were all offline at once. Even with all of that discipline, the picture is grim.

A quarter of Saudi production is gone

Start with the headline number. In February, before the war, Saudi Arabia produced about 10.88 million barrels of crude a day. In September it was still producing 2.51 million barrels a day less, a drop of 23 percent. In August the shortfall was 4.64 million barrels a day, when output sank to about 6.24 million. From March through September, the Kingdom produced more than 800 million fewer barrels than it would have at its February rate. That is roughly eight days of total world oil consumption that never came out of the ground.

Aramco’s own books say the same thing. In the company’s reported figures, its liquids production fell from 10.56 million barrels a day in the first quarter to 7.57 million in the second, a 28 percent collapse in a single quarter. Natural gas and ethane fell nearly 6 percent. A company whose system was intact does not report numbers like that.

Exports followed production down. In one consistent tracking series, Saudi crude exports fell from 7.27 million barrels a day in February to 3.70 million in August, a 49 percent drop. They recovered to 5.62 million in September, but that is still 23 percent below the pre-war level.

The damage runs through the whole chain

The reason the recovery keeps stalling is that the damage is not in one place. It runs from the wellhead to the gas station.

At the front end, the Abqaiq complex, the plant that conditions most of Saudi Arabia’s light crude before it can be shipped or refined, sustained physical damage in July. In March, some 2 to 2.5 million barrels a day were curtailed across the offshore Safaniya, Marjan, Zuluf and Abu Safa fields. In April, Khurais and Manifa each lost 300,000 barrels a day.

In the middle, five of the Kingdom’s major refineries have been damaged or shut down. Ras Tanura, at 550,000 barrels a day the largest domestic refinery, burned and was shut in March. SATORP in Jubail lost three units in April, restarted at half capacity and was still running at only about 70 percent in May. SAMREF in Yanbu was hit in March. The Riyadh refinery caught fire on October 3. Jazan, a 400,000-barrel-a-day plant designed to turn out 250,000 barrels a day of ultra-low-sulfur diesel, shut down on July 27 after its power plant and tank farm were hit, and Ansar Allah attacks in August and September disrupted every attempt to restart it. Satellite imagery now shows tank damage at Petro Rabigh as well. The Juaymah gas-liquids plant, which feeds Saudi Arabia’s LPG exports, has suffered fires.

At the back end, the system for storing and moving fuel is being picked apart. Imagery of the Abha bulk plant from September 13 shows six tanks apparently destroyed and eight more damaged. A depot near Riyadh’s airport burned on September 19. Jazan’s tank clusters have been hit repeatedly.

And the East-West Pipeline, Saudi Arabia’s only way to move crude to the Red Sea and around a closed Strait of Hormuz, has been hit again and again. In April, 700,000 barrels a day of pumping capacity was knocked out. In September, repeated attacks took out three pumping stations and halted the line until a low-rate restart on September 22. On October 4 and 5, another pumping station near Khurais was reported badly damaged. The energy minister now says the line is running at 5.8 million barrels a day, against a rated 7 million. Even Miller notes that no one outside Aramco is metering the actual flow.

Why repairs don’t stick

Miller’s most important insight is that this is a system, and systems fail at their weakest link. Jazan is the clearest example. Fixing the crude units does no good if the gasification and power plant that run the refinery is still damaged, and fixing the power plant does no good if there are no tanks to put the diesel in. A refinery can be “restarted” on paper and still produce nothing useful. The same logic runs upstream. An oil field with every well intact still has to shut in if the processing plant or pumping station downstream of it is broken.

Every time Aramco gets one link repaired, another one gets hit. That is why restart announcements keep failing to show up in the production numbers.

Saudi Arabia is running out of fuel to sell

The most alarming numbers in Miller’s report are about refined products. By July, the latest month with complete data, Saudi refinery output was down 534,000 barrels a day from February, nearly 18 percent. Diesel output fell 21 percent. Diesel exports fell 47 percent, from 848,000 barrels a day to 446,000. Gasoline exports fell 40 percent.

The Saudis have been covering the gap by draining their tanks. Diesel stocks fell from 25.6 million barrels in February to 16.6 million in July, down 35 percent. Gasoline stocks fell by the same proportion. The world’s largest oil exporter more than doubled its imports of fuel oil, and it is burning more than twice as much crude directly in its power plants as it did in February. Some of that is the summer air-conditioning load, but it is not the behavior of a country with fuel to spare.

Lower stocks mean less cushion for the next attack. And there will be a next attack.

The trap Riyadh is in

Miller’s report spells out one more danger that I have not seen discussed anywhere else. If Saudi Arabia’s export outlets close, its oil has nowhere to go but its own refineries, its own power plants and its storage tanks. In July, domestic refineries and direct burning absorbed about 3.04 million barrels a day. Once the storage is full, that is roughly the ceiling on what Saudi Arabia could keep producing. Close Ras Tanura and Yanbu at the same time, and the Kingdom would have to shut in most of its oil fields. That is exactly the scenario Ansar Allah’s campaign against the pipeline, the Red Sea and the Gulf terminals is built to produce.

Why this matters to everyone else

The rest of the world is already living with the consequences. Saudi diesel exports are down by about 400,000 barrels a day, at the same moment Hormuz is restricted and Russian refineries are under drone attack. The International Energy Agency says the global diesel shortage will last well into 2027. Brent is above $100. Europe, which depends on imported diesel, is already rioting over the cost of living, and winter has not started.

Miller makes no claim that every barrel of lost output was blown up by a Houthi missile, and he is careful to say so. Some of the decline reflects shipping, security and commercial decisions. But the point is that it doesn’t matter to a trucker in Lyon or a farmer in Lombardy whether a barrel was lost to a missile, a closed sea lane or a refinery that has no power. It is gone either way.

So when Aramco says its system is intact, ask what the production figures, the export figures and the fuel stocks say. They say Saudi Arabia is producing a quarter less oil than it did in February, exporting half as much diesel, and drawing down its reserves to keep the lights on. Any new American or Israeli campaign against Iran will land on a Saudi energy system that has no slack left to absorb it.


Video interviews

  •  

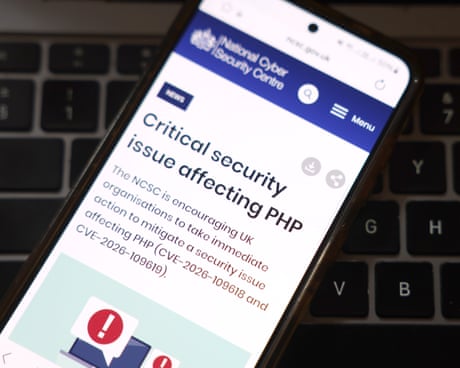
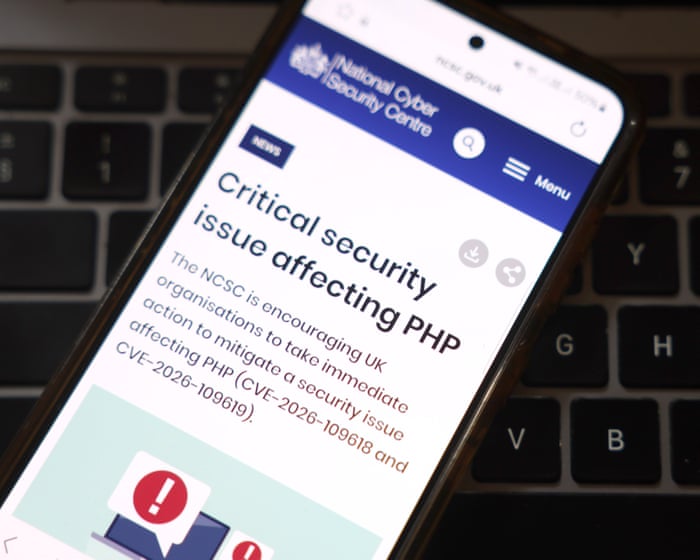
‘No indications’ PHP code flaw has led to government systems being hacked, cyber security official says – as it happened

Some 32 government services are offline while work is carried out to address potential cybersecurity issues, a minister has said

The Office for National Statistics has also published a report on the gender pay gap. It says:

The gender pay gap for full-time employees has continued to decline in the UK. It was 6.8% in April 2026, down from 7.2% in April 2025. This compares with 9.4% a decade ago and 16.4% 25 years ago.

Secondly, I asked Healey whether he sees the banks as making excessive profits, which would be the coherent justification for him to increase the surcharge on bank profits – as he is expected to do in the Budget next week.

He said: “You know the banks are the engine of investment in this country. The banks are doing well at the moment and that is good to see.

Continue reading...

© Photograph: Neil Hall/EPA

© Photograph: Neil Hall/EPA

© Photograph: Neil Hall/EPA

  •  

French borrowing costs overtake US amid budget turmoil

France’s bond market hit by another bout of selling as country recovers from weekend protests

French borrowing costs continued to rise on Thursday, as investors fret that France’s government is struggling to pass a federal budget after public protests gripped the country.

France’s bond market was hit with another bout of selling, with the difference between French and German 10-year borrowing costs – a metric for the risk premium attached to French debt – rising to its highest level in almost 15 years.

Continue reading...

© Photograph: Telmo Pinto/NurPhoto/Shutterstock

© Photograph: Telmo Pinto/NurPhoto/Shutterstock

© Photograph: Telmo Pinto/NurPhoto/Shutterstock

  •  
❌