China proposes export controls on solar-manufacturing technologies


America's interminable war with Iran has killed thousands, disrupted commerce that flows through the Strait of Hormuz, and raised prices on the home front.
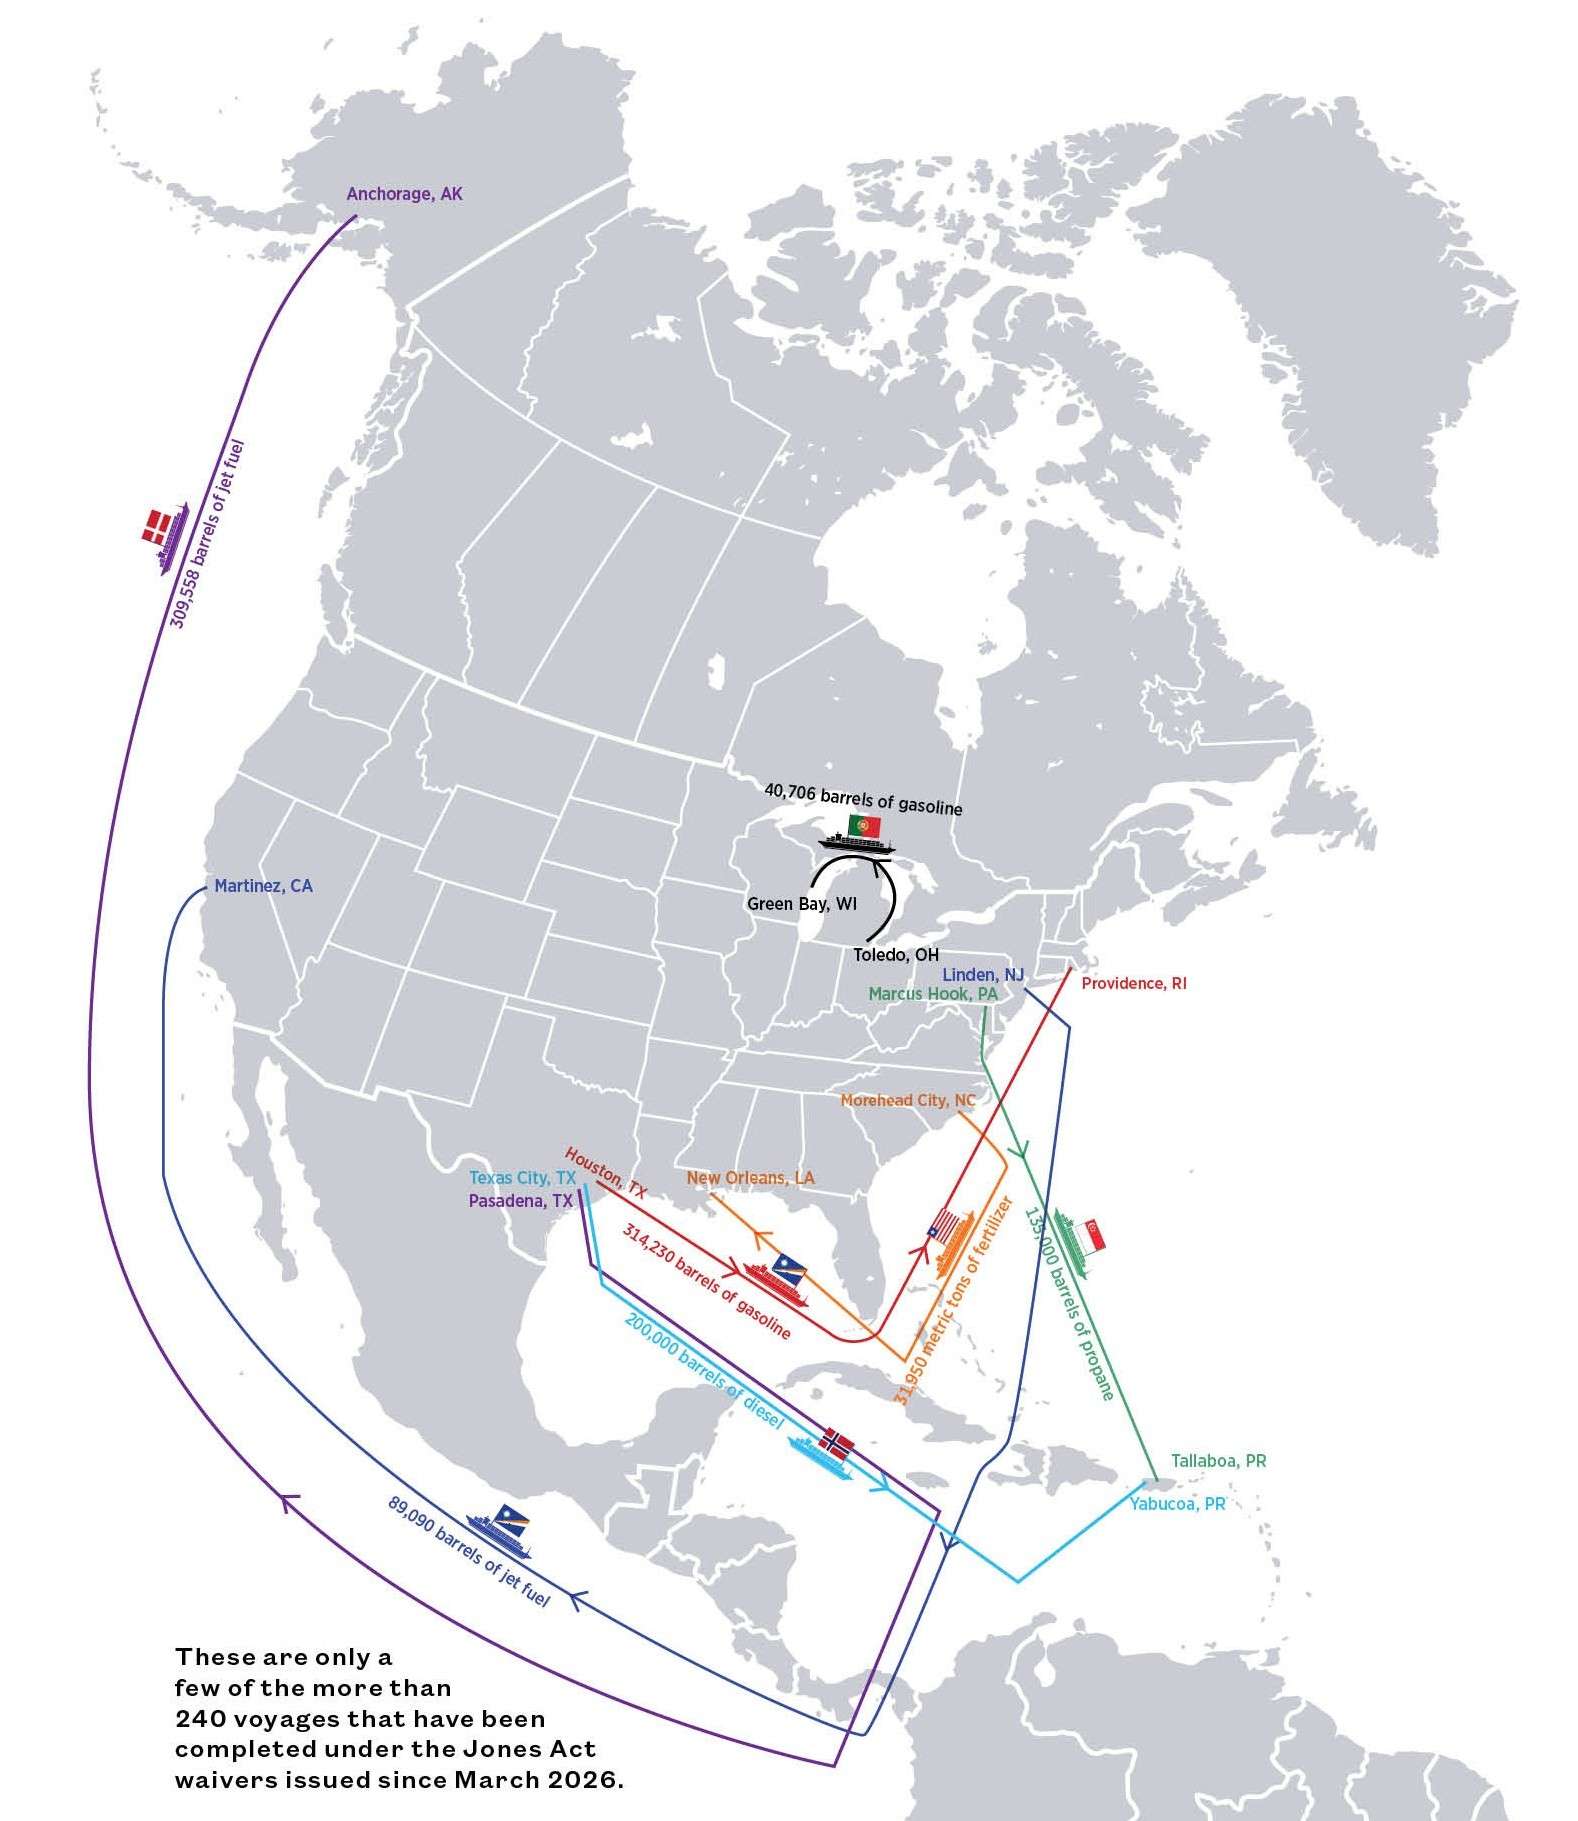
But there may be one silver lining. In an attempt to lower gas prices that spiked because of the war, the Trump administration has repeatedly issued waivers of the Jones Act, a century-old law that requires all goods moved between American ports to be carried on American-built, American-crewed ships.
With the law (temporarily) not being enforced, commerce has exploded.
Just look at how much propane has been shipped from the mainland United States to Puerto Rico, says Colin Grabow, a trade policy analyst at the Cato Institute and perhaps the nation's foremost advocate for abolishing the Jones Act.

Since March, when the first waiver was issued, Puerto Rico has imported more than 800,000 barrels of propane from the mainland. That's more than twice the amount of American propane shipped to Puerto Rico in the last 22 years combined.
America is one of the world's leading producers and exporters of propane, but the lack of Jones Act–compliant ships capable of carrying gas means that it has been nearly impossible to ship propane from the mainland to outlying parts of the country. In the past, Puerto Rico has imported gas from Nigeria, Chile, and elsewhere because those deliveries don't have to comply with the Jones Act.
For years, libertarians have argued that the Jones Act unfairly impoverishes American consumers and businesses that want to buy and sell things within the same country in order to artificially inflate the price of moving those things across water. Waiving the law seems to have proven that point: There are plenty of ships capable of moving gas and oil around the country as long as the government gets out of the way.
"The instant the Jones Act no longer applied to energy shipments, mainland propane displaced foreign imports, suggesting it had been the cheapest option all along," says Grabow.
Puerto Rico is hardly the only winner.
The Jones Act waivers are offering a glimpse into a world where the law doesn't exist. From March through mid-August, there had been 210 voyages completed that otherwise would have been deemed unlawful without the waivers, according to an analysis of Maritime Administration data by the Institute for Energy Research.
It's a world where American oil and natural gas can be more easily shipped from the Gulf Coast to New England, which had previously been importing energy from Russia and Europe. Another big winner is California, which had been importing gasoline from as far away as the Bahamas because it was nearly impossible to legally ship gas from Texas or Alaska to the West Coast.
President Donald Trump reupped the Jones Act waiver in mid-May. Another extension, issued in August, will last for 90 days but applies only to ships carrying energy products such as gas and oil. Before that waiver expires in November, lawmakers ought to kill the Jones Act permanently.
There is some irony in the fact that one of Trump's most successful policy maneuvers has paused a protectionist law that limited commerce, when so much else of his economic policy has been focused on erecting barriers to trade. It's also amusing that it was a war in the Middle East—something Trump pledged to avoid—that triggered this change.
Still, the proof is in the shipping. The free traders were right all along.
The post Trump's War With Iran Pushed Him To Waive a Century-Old Shipping Law. Commerce Boomed. appeared first on Reason Magazine.


Beijing warns against ‘discriminatory’ step after France drops opposition to British role in Made in Europe package
No 10 has left the door open to imposing tariffs on Chinese-made electric vehicles as part of the Made in Europe package, prompting a warning from Beijing that such a move would be “discriminatory”.
Downing Street said on Friday that it would “welcome the objective to have the UK included in the Industrial Accelerator Act” after France dropped its opposition to Britain joining the scheme.
Continue reading...
© Photograph: Nick Carey/Reuters

© Photograph: Nick Carey/Reuters

© Photograph: Nick Carey/Reuters
By Marco CARNELOS
Join us on Telegram
, X
, and VK
.
Contact us: info@strategic-culture.su
Record debt, a paralysed trade-dispute architecture and the normalisation of sovereign-asset seizure as a policy tool means fragility is baked into the global economic system
Since 2022, a steady drumbeat of forecasts has warned that cascading military and political upheavals – war in Ukraine, conflict in the Middle East, an accelerating tariff war, the weaponisation of sanctions and the disruption of energy supplies – would eventually overwhelm the world economy’s capacity to absorb shocks.
The most destructive of those scenarios have not materialised, or at least not yet.
As the IMF’s managing director Kristalina Georgieva stated last year, while previewing the fund’s World Economic Outlook, the global economy “has generally withstood significant strains from various shocks”.
Although that resilience is real, on closer inspection, it is a more fragile and more contested achievement than it first appears.
The adaptive mechanisms behind this resilience are visible and measurable. Trade has rerouted rather than collapsed. Energy corridors have diversified. And reserve managers have spent the past three years quietly re-engineering the architecture of the international monetary system.
According to the World Gold Council’s 2026 Central Bank Gold Reserves survey – which drew responses from 76 institutions, its highest participation in nine years – 89 percent of central banks expect global gold holdings to keep rising over the next year, with a record share planning to add to their own reserves.
The result: gold has overtaken US Treasuries as the largest single component of global central bank reserves for the first time since the mid-1990s.
Mother of all ticking bombs
Analysts tracking the shift link it directly to a single event: reserve managers were unsettled by the seizure of the Central Bank of Russia’s reserves at the start of the Ukraine war by Washington and have since been actively reducing the dollar share of their portfolios.
This is a clear example that the economic system is not breaking under political pressure, it is adapting to it – flexibly, and crucially, without severing the interconnections that make global trade and finance function at all.
In other words, central banks accumulating gold are not exiting the system; they are just hedging within it.
But adaptability has a cost, and that cost is compounding.
Global debt – government, household, corporate and financial combined – surpassed $365 trillion in the first half of 2026, according to the Institute of International Finance’s Global Debt Monitor, the sixth consecutive quarterly record.
Emerging-market debt alone rose by $6.5 trillion in the same period, breaking past $110 trillion. Georgieva has been blunt about the trajectory: speaking at the IMF and World Bank annual meetings, she warned that global public debt is projected to reach 110 percent of the world’s GDP by 2029.
There is an evident reluctance to address what is not a crisis in any single country’s balance sheet, but a structural drift that every major economy appears aware of and none is prepared to correct unilaterally.
Debt of this scale narrows the fiscal space available to absorb the next shock, military or otherwise, which is precisely what makes today’s resilience difficult to extrapolate into tomorrow’s.
In this context, there is also the mother of all ticking bombs, a nuclear one: the $40 trillion US federal debt which US Secretary of Treasury Scott Bessent is desperately trying to reign in.
The third strand, the onslaught of punitive political measures targeting market principles, is best illustrated by the fate of Russia’s frozen central bank reserves. Roughly $300bn in Russian sovereign assets have been immobilised globally since 2022, with some €210bn ($235bn) held within the European Union.
Erosion of neutrality
Rather than remaining in legal limbo, these reserves have become the financial engine of a specific policy outcome: the EU’s proposed €140bn ($157bn) “reparations loan” to Ukraine, structured so that Ukraine would repay it only once Russia itself pays war damages – effectively converting a sanctions freeze into a grant.
Russia’s central bank has responded by suing the Brussels-based depository Euroclear, which holds the bulk of the assets, calling the manoeuvre illegal.
Whatever one’s view of the underlying conflict, the precedent is the point economists increasingly raise: the first large-scale use of frozen sovereign reserves as collateral for a geopolitical objective changes the calculus for every reserve-holding state watching from outside the western bloc.
It is one more data pointing to the reinforcing of the gold-accumulation trend described above – and a vivid example of how political tools aimed at a single adversary can erode the perceived neutrality of the system itself.
A parallel erosion is under way in trade governance. The WTO’s Appellate Body (the one supposed to settle trade dispute among countries) has been non-functional since December 2019, after the United States blocked the appointment of new judges and talks on reviving or replacing it remain stuck.
More than 30 appeals currently sit unresolved, and the workaround mechanism created to fill the gap – the Multi-Party Interim Appeal Arbitration Arrangement – has resolved only a single case. The institution designed to prevent trade disputes from becoming purely a function of relative power has been quietly sidelined for seven years.
It is then worth wondering – in such a situation – if the Global West and Global Rest see the same picture here.
The evidence suggests convergence on diagnosis but real divergence on meaning. Both recognise that debt is unsustainable and that institutions are strained. But where western policymakers tend to treat sanctions, frozen assets and trade paralysis as defensive responses to external aggression.
Voices from the Global Rest increasingly read the same tools as confirmation that the system was never as neutral as advertised.
India’s External Affairs Minister S Jaishankar captured this gap memorably in 2022, telling European interlocutors that Europe needed to “grow out of the mindset” that its problems are everyone’s problems while the reverse does not hold.
Selective status
This is something many Global Rest governments had been thinking but not saying aloud: that the postwar order’s claim to universality was always, in practice, more selective than it appeared.
The more honest and outspoken western leader to recognise such an unfair situation, to use an understatement, was Canadian Prime Minister Mark Carney earlier this year in Davos.
None of this means the system is about to fracture. The world economy has proven more elastic than feared, absorbing shocks that a decade ago might have triggered genuine crisis. But elasticity and durability are not the same thing.
The real test of this sort of “economy of resistance” is not whether it survives the next military-political storm – it plainly has, repeatedly.
It is whether record debt, a paralysed trade-dispute architecture, and the normalisation of sovereign-asset seizures as a policy tool are quietly converting what is in effect a short-term adaptability into long-term fragility, especially at a moment when the Global Rest and Global West can no longer agree on what the system is actually for.
Original article: www.middleeasteye.net
Shevaun Haviland argues PM is right to revisit Labour’s EU red lines as current trading relationship is bad for business
Repairing the economic damage of Brexit should be the top priority for Andy Burnham as he reconsiders Labour’s red lines on EU membership, the head of one of Britain’s leading business groups has said.
Shevaun Haviland, the director general of the British Chambers of Commerce (BCC), said she welcomed the prime minister reopening the Brexit battle lines despite the uncertainty it could create, arguing that the UK’s current trading relationship with the EU was bad for business.
Continue reading...
© Photograph: Toby Melville/Reuters

© Photograph: Toby Melville/Reuters

© Photograph: Toby Melville/Reuters

© Tierney L. Cross/The New York Times
The EU is preparing to curb Chinese imports of chemicals and industrial machinery, following a successful deal with Beijing that capped hybrid car exports to the bloc.
The European Commission “showed openness” to proposing safeguards, referring to an emergency brake on imports that can cover entire sectors, an EU diplomat told EUobserver on Thursday (15 October).
And there was “broad support” for the idea among member states for the commission to proceed, the diplomat said.
Last week, trade commissioner Maroš Šefčovič agreed with Beijing to cap imports of Chinese hybrid cars at 350,000 next year, which was less than half the amount expected this year.
He called the deal a “blueprint” for other sectors, a view which was publicly echoed by EU Commission president Ursula von der Leyen, also on Thursday.
Under World Trade Organization (WTO) and EU rules, anti-dumping and anti-subsidy cases require Brussels to prove that Chinese firms sell at unfairly low prices or receive subsidies.
Safeguards do not need evidence under WTO rules, which allows them to be used as an emergency measure.
And the commission only has to show that a surge in imports is seriously harming European producers.
“We like the idea, chemicals, machinery where there’s still a lot of Chinese overproduction needs to be managed,” said another EU diplomat.
The instrument had its limits: Safeguards have to apply to all countries, not just China, and can last no more than eight years.
The EU rarely uses WTO safeguards, but did so on steel, also aimed at China, which expired in June, after reaching the eight-year limit, and which have since been replaced by a separate EU steel regime.
And the Centre for European Reform, a prominent think-tank in Brussels, previously suggested exempting the EU’s 76 free-trade partners from safeguards so that the measures fell mainly on China.
It was a legal moot point in the WTO if that was OK, but the EU has done something similar before.
Norway, Iceland, Liechtenstein, and 10 other countries were left out of the steel safeguard, but using this tool to address Chinese imports was still seen as a temporary solution.
Before the end of the year, the EU commission aims to present diversification tools to reduce reliance on Chinese goods, as well as a mechanism to compensate companies hit by Chinese countermeasures.
And the package would include an instrument to shut Chinese companies out of the EU market if need be, in a measure first proposed in a Franco-German paper last week.
President Donald Trump promised that his tariffs would usher in a "golden age" by prioritizing the interests of American workers.
Those workers, however, are now turning against Trump's tariffs.
Support for the Trump administration's tariff policies has fallen by 25 percentage points among blue-collar workers over the past year, according to new polling data from Echelon Insights and the Economic Innovation Group (EIG).
A poll conducted by the two groups in August 2025 found that blue-collar workers supported the tariffs by a narrow margin. Now, that same segment of the population has turned decisively against Trump's tariffs: 58 percent oppose them, compared to just 36 percent who support them.

Overall, support for the tariffs has declined from about 43 percent last year to only 34 percent. Opposition to the tariffs has grown from 50 percent to 59 percent. Elsewhere in the same survey, 68 percent of respondents said the tariffs have made the cost of living higher.
It's not hard to figure out why people have turned against the tariffs: They have contributed to rising prices across the economy.
The annualized inflation rate ticked upward to 3.7 percent in September, according to new data from the Bureau of Labor Statistics (BLS). More BLS data released Thursday morning shows that the producer price index, which often operates as a precursor to inflation, is up 6.3 percent over the past year.
America's war with Iran has been a major factor in rising inflation, but the tariffs have played a significant role as well. In a study released last week, the New York Federal Reserve concluded that consumer prices would have declined slightly over the past year if not for the economic effects of the tariffs.
The tariffs have become so unpopular that not even partisanship can save them. "Among GOP-voting workers, only 3 percent select tariffs as their top priority," note Jordan McGillis and John Lettieri, policy experts from the EIG, in their write-up of the poll.
Other parts of Trump's economic agenda are not faring much better. The Trump administration has bought or seized shares of more than 30 private businesses over the past two years—ranging from major firms such as U.S. Steel to small mining companies with few customers. "The federal government's state corporatism is unprecedented," reports the Cato Institute in a new analysis of those deals.
Large majorities of workers across both major parties and all generations said they opposed the federal government taking equity stakes in American companies in the Echelon/EIG poll.

In short: This economic populism sure isn't very popular.
All of this is likely to be a major factor in next month's midterm elections. Regardless of how that shakes out, however, there are lessons to be drawn from this poll for both sides of the political divide.
For conservatives, these polling data should end the tariff experiment. It has proven economically damaging, and it is no longer a political winner (if it ever was).
Remember, the idea to hike tariffs and start trade wars with all of America's biggest trading partners was not some grand plan backed by careful study and thoughtful analysis. It sprung, half-baked, from the head of one man. Yes, there have been various attempts to support, in a post hoc way, Trump's desire for tariffs. All of that can, and should, be easily discarded. There is no reason to allow a lame duck president to continue to set such a politically and economically destructive path for the country.
Undoing the tariffs might also put a meaningful dent in rising prices. That should be a no-brainer after the midterms, no matter which party controls Congress.
On the left, this poll should be a reminder that Americans do not look favorably on the mixing of government and business. Democrats should promise to unwind the "equity stakes" that the federal government has taken under Trump's watch. Heading toward the 2028 presidential cycle, Democrats might want to borrow some old Republican talking points about how government shouldn't be picking winners and losers—they may find that message is still quite popular.
Yes, it's probably right to be skeptical that those things will happen. Trump's efforts to centralize economic power in the executive branch are likely to outlive his presidency—that's how these things always seem to go.
But there is a glimmer of hope here. Americans are soundly rejecting the Trump administration's big government policies.
The post Even Blue-Collar Workers Have Turned Against Trump's Unpopular Tariffs appeared first on Reason Magazine.
Europe’s trade deficit with China reached a record $34.8bn [€31bn] in September, as EU leaders meet in Brussels on Thursday (15 October) to discuss Europe’s competitiveness agenda and what they call “macroeconomic imbalances” — a euphemism to avoid mentioning China by name.
EU heads of state and government are expected to give a mandate to the EU Commission to propose a set of trade defence measures and tools to reduce the EU’s reliance on Chinese industry, based on a new Franco-German blueprint, as a united front spreads across the bloc.
There was a move towards a “surprising unitary position” on Beijing among member states, said an EU diplomat, ahead of a two-day summit in Brussels which began on Thursday (15 October).
A joint letter and policy paper submitted by French president Emmanuel Macron and German chancellor Friedrich Merz to commission president Ursula von der Leyen last week was viewed by many EU diplomats as marking a decisive shift towards a more consolidated EU stance on trade relations with China.
“For a long time, there were significant differences between these two countries on how to deal with China, how to address the economic situation,” parliament president Roberta Metsola told reporters on Thursday.
The diplomat added that the commission’s trade diversification package, designed to reduce the bloc’s reliance on Chinese industrial inputs and curb Chinese exports, will be presented by the end of the year and will be based on the Franco-German paper.
But the commission, for its part, has downplayed the prospect of rapid progress to EU-Chinese trade statistics. “It’s an issue which is not going to be solved in a couple of months,” said one official.
This article continues, but the full version is available only to EUobserver.com subscribers. Visit account.euobserver.com/membership
When a president starts with a predetermined policy and then goes looking for a statutory pretext to justify it, he is building on shaky ground. President Donald Trump illustrated that point once again in July, when he announced a third round of broad tariffs after his first two attempts ran into legal trouble.
Shortly after taking office in 2025, Trump claimed to have discovered a previously unnoticed delegation of extensive tariff authority in the International Emergency Economic Powers Act (IEEPA), a 1977 law that does not mention import taxes and had never been used to impose them. That claim was rejected by every court that considered it.
Last February, the Supreme Court ruled that IEEPA does not authorize tariffs at all. But Trump had a backup plan: Hours after that decision, he announced another sweeping set of tariffs, this time relying on Section 122 of the Trade Act of 1974.
That provision allows tariffs in response to "fundamental international payments problems" caused by "serious United States balance-of-payments deficits." In May, the U.S. Court of International Trade (CIT) ruled that the new tariffs were illegal because Trump had failed to "identify balance-of-payments deficits within the meaning of Section 122."
Although that decision was stayed pending appeal, Trump's Section 122 tariffs, which were subject to a 150-day statutory limit, expired on July 24. Trump then switched to Plan C, invoking Section 301 of the Trade Act, which authorizes tariffs in response to a foreign "act, policy, or practice" that is "unreasonable or discriminatory" and "burdens or restricts" U.S. commerce.
Trump's Section 301 tariffs supposedly targeted countries that had failed to "impose and effectively enforce a prohibition on the importation of goods produced with forced labor." The alleged offenders included 86 economies that accounted for nearly all U.S. imports.
In separate complaints, the Liberty Justice Center (LJC) and the law firm Akin Gump, which had played leading roles in challenging Trump's prior tariffs, immediately asked the CIT to block the new import taxes. By and large, they noted, the government had failed to explain how the targeted countries had fallen short, how their alleged failures burdened U.S. commerce, or why the new tariffs could be expected to ameliorate the problem they were supposed to address.
The LJC argued that the forced-labor issue was "simply a pretext" for reinstating Trump's "invalidated global tariff regime." It added that Trump's reading of Section 301, like his interpretation of IEEPA, would violate the "major questions" doctrine, which requires clear congressional authorization for policies of "vast economic and political significance."
This was Trump's "third attempt" to "impose essentially the same set of sweeping global tariffs," Akin Gump's lawyers wrote. "The third time's not the charm."
The post Trump Keeps Coming Up With Legally Dubious Tariff Justifications appeared first on Reason Magazine.
Exclusive: Douglas Alexander, on trade delegation to India, talks up economic benefits of joint trading arrangements with Europe
Britain will benefit from much closer trading relations with the EU even if that means giving up its ability to negotiate free trade agreements, the Scotland secretary has said.
Douglas Alexander helped negotiate deals with India and the US when he was a trade minister under Keir Starmer.
Continue reading...
© Photograph: X/Douglas Alexander

© Photograph: X/Douglas Alexander

© Photograph: X/Douglas Alexander
Ola Källenius says it will ‘weaken the industry on both sides’ ahead of act intended to counter non-EU competition
Locking the UK out of the EU’s flagship industrial “Made in Europe” legislation would amount to a “deliberate choice” by EU leaders to “hurt” the car industry across the bloc, the head of Mercedes-Benz has said.
Speaking in his capacity as president of the European Automobile Manufacturers’ Association (ACEA), Ola Källenius said such a move would “weaken the industry on both sides”.
Continue reading...
© Photograph: Christoph Steitz/Reuters

© Photograph: Christoph Steitz/Reuters

© Photograph: Christoph Steitz/Reuters
Belgium’s foreign minister has called on the EU to deepen its economic, trade, and defence ties with Turkey, amid concerns from Ankara that it risks being shut out of the bloc’s new rules on industrial supply chains and multi-billion euro defence procurement scheme.
Speaking at a Turkey-EU business forum in Brussels on Tuesday (13 October), Belgian foreign minister Maxime Pévot said that European manufacturers were increasingly looking for reliable partners closer to home as they seek to reduce their reliance on Chinese inputs.
“We should make values of its proximity, particularly in sectors where Europe needs to reduce strategic dependencies,” he added.
“Our economic relationship should no longer be limited to buying and selling goods. We should also be developing, producing, and investing together,” he said.
For his part, following talks with Ankara’s trade minister, Ömer Bolat, EU trade commissioner Maroš Šefčovič told reporters that the two sides had agreed on reforms to Turkey’s import control system to make the system easier for EU exporters to use and a mutual recognition pact on trusted traders.
This article continues, but the full version is available only to EUobserver.com subscribers. Visit account.euobserver.com/membership
He Lifeng conveyed the message to Emmanuel Bonne during a meeting held Tuesday at the Great Hall of the People on Wednesday. Both discussed bilateral cooperation and trade relations between Beijing and Brussels, Xinhua reported.
The official also highlighted the possibilities of expanding economic cooperation with France and expressed Beijing’s willingness to implement the consensus reached by the presidents of both countries.
RELATED: Trade escalation: Trump imposes 100% tariff on imports from China U.S.
Bonne, for his part, conveyed Paris’s readiness to continue promoting positive results in trade and investment consultations between China and the EU.
The French adviser had already defended last Friday, during a meeting with Chinese Foreign Minister Wang Yi, that Europe does not want a trade war with China nor seeks economic decoupling, according to a statement from the Chinese Foreign Ministry.
“Europe’s development needs China,” Bonne said at that meeting, according to the version released by the Chinese Foreign Ministry.
EU-CN trade needs real rebalancing. With Minister Wang Wentao we've reached a shared understanding to:⁰🔹halve HEV, PHEV exports⁰🔹improve access to China's market⁰🔹further ease rare earths export licensing.
— Maroš Šefčovič🇪🇺 (@MarosSefcovic) October 9, 2026
A first step. I welcome the genuine engagement. We reconvene by Jan. pic.twitter.com/SiKiZYLC8N
The contacts come after the agreement reached last week between Beijing and Brussels, which contemplates limiting Chinese exports of hybrid vehicles to the EU bloc, facilitating European access to rare earths and reducing tariffs on certain European products.
Drawing on dozens of interviews with intelligence and police officers across two continents, a Guardian investigation reveals the murderous cost of our insatiable appetite for cocaine
Read more: Latin American organised crime ‘may operate in 16 European countries’
Explainer: What is state capture and why does it matter?
As abductions go, few have been more brazen. Alan Jalloh was with two friends outside Goodies supermarket, frantic as usual with late afternoon shoppers. Rush hour in downtown Freetown, Sierra Leone’s capital, was under way with familiar gusto.
A black Toyota Rav4 forced its way through the Peninsula highway traffic. Witnesses describe burly white men leaping out, yanking on balaclavas. Jalloh, 40, seemed to freeze. As did his two friends, one a famous Freetown footballer. All three were dragged into the waiting SUV. None of them have been seen since.
Continue reading...
© Composite: Guardian Design

© Composite: Guardian Design

© Composite: Guardian Design
BRICS Pay non è una valuta né una rete di regolamento: è interoperabilità. E a Nuova Delhi i leader si sono limitati a “prenderne atto”.
Cosa è e cosa non è
Alla vigilia del diciottesimo vertice BRICS, ospitato al Bharat Mandapam di Nuova Delhi il 12 e 13 settembre 2026, una parte della stampa specializzata dava per imminente il debutto di BRICS Pay. Le guide al vertice indicavano proprio la capitale indiana come sede del pieno dispiegamento del sistema, con la Reserve Bank of India incaricata del coordinamento tecnico. Il testo approvato dai leader racconta un’altra storia. La Dichiarazione di Nuova Delhi, 140 paragrafi adottati per consenso, si limita a «prendere atto» del lavoro svolto dalla BRICS Payment Task Force sull’interoperabilità dei canali di pagamento e di messaggistica e sulle discussioni relative al regolamento in valute locali, precisando che ciò avviene nel rispetto delle priorità nazionali e nella consapevolezza che non esiste una soluzione valida per tutti. La proposta indiana di collegare le valute digitali delle banche centrali, su cui Nuova Delhi aveva investito una parte consistente del capitale politico della propria presidenza, nel documento non compare.
La distanza tra attese e risultato non va letta come un incidente diplomatico. Riflette due condizioni strutturali che la pubblicistica sulla de-dollarizzazione tende a sottovalutare. La prima è che i Paesi BRICS, presi uno per uno, hanno ancora buone ragioni per regolare in dollari una parte rilevante dei propri scambi. La seconda è che un sistema di pagamento comune non è un problema di ingegneria finanziaria. È un atto di governo condiviso, che richiede regole vincolanti, un’istanza di arbitrato e la disponibilità a fidarsi delle banche centrali altrui. A Nuova Delhi nessuna di queste condizioni era sul tavolo.
Il nome induce in errore. BRICS Pay non è una moneta e non è, almeno nella configurazione discussa finora, un circuito di regolamento. È un livello di interoperabilità pensato per mettere in comunicazione sistemi nazionali già esistenti: il russo SPFS, nato dopo le sanzioni del 2014; il cinese CIPS, operativo dal 2015; l’indiano UPI e il brasiliano Pix, costruiti per i pagamenti domestici istantanei e solo in seguito proiettati all’estero. Il progetto ha preso forma durante la presidenza russa del 2024, nel quadro della BRICS Cross-Border Payments Initiative accolta a Kazan, un’iniziativa che la stessa dichiarazione di quel vertice qualificava come volontaria e non vincolante.
Per capire dove si colloca il progetto conviene distinguere tre piani che il dibattito pubblico confonde di continuo. Il primo è la messaggistica, cioè la trasmissione standardizzata degli ordini di pagamento tra istituzioni finanziarie: è il terreno di SWIFT, ed è qui che BRICS Pay si propone come alternativa. Il secondo è il regolamento, il trasferimento effettivo di valore tra conti presso banche centrali o banche corrispondenti, con tutto ciò che comporta in termini di liquidità, rischio di controparte e gestione dei saldi. Il terzo è l’unità di conto, la moneta in cui i contratti sono denominati. Un’alternativa a SWIFT agisce soltanto sul primo piano. Se un esportatore indiano fattura in dollari e la banca russa regola in dollari presso un corrispondente, aver trasmesso il messaggio su un canale non occidentale cambia ben poco.
L’interoperabilità ha però un vantaggio politico evidente, ed è la ragione per cui è diventata la formula di compromesso del gruppo: consente a ciascun Paese di conservare la propria moneta e il proprio sistema finanziario. Una moneta comune imporrebbe rinunce di tutt’altra portata, dalle regole di emissione e di cambio alla gestione dei Paesi strutturalmente in avanzo o in disavanzo. Non a caso Sudhakar Dalela, segretario per le relazioni economiche del ministero degli Esteri indiano, ha ribadito durante il vertice che una valuta BRICS non è in discussione, aggiungendo la prudente clausola «per ora».
La storia del dossier è la storia di un lessico che avanza di millimetri. Nel 2010, a Brasília, i quattro Paesi fondatori si impegnavano a studiare la fattibilità di una cooperazione monetaria e di accordi di regolamento in valuta locale. A Ufa, nel 2015, si riconosceva il potenziale delle valute nazionali; a Xiamen, due anni dopo, si parlava di swap valutari e di investimenti diretti in moneta locale. Dal 2019 l’attenzione si è spostata sulle infrastrutture di pagamento, con l’avvio dei lavori della Payment Task Force. Johannesburg, nel 2023, ha evocato per la prima volta l’interconnessione dei sistemi di pagamento transfrontalieri; Kazan ha lanciato l’iniziativa volontaria; Rio, nel 2025, ha accolto un rapporto tecnico sul sistema di pagamenti transfrontalieri BRICS che a oltre un anno di distanza non è stato reso pubblico. Sedici anni dopo Brasília, Nuova Delhi «prende atto». La successione dei verbi (studiare, riconoscere, accogliere, prendere atto) è già un indicatore: in un organismo che decide per consenso, il grado di impegno reale si legge nella grammatica dei comunicati.
L’ambizione indiana e il prezzo del consenso
L’India aveva fatto dei pagamenti transfrontalieri uno dei pilastri della propria presidenza. A gennaio la Reserve Bank of India aveva proposto di collegare le valute digitali di banca centrale dei Paesi membri per facilitare commercio e turismo; ad agosto il governatore Sanjay Malhotra confermava che erano in corso discussioni sul collegamento dei sistemi di pagamento veloce e delle CBDC; alla vigilia del vertice il ministro del Commercio Piyush Goyal rilanciava l’invito a regolare gli scambi in moneta locale. Già il 10 settembre, tuttavia, Reuters riferiva di ostacoli politici e tecnici in grado di limitare i progressi, e ne indicava due in particolare: l’interruzione dei rapporti finanziari tra Emirati Arabi Uniti e Iran e la riluttanza della stessa India ad approfondire la connettività finanziaria con la Cina senza una fiducia reciproca più solida.
Il secondo ostacolo merita attenzione, perché rovescia un’immagine corrente. Il freno più robusto a un’integrazione dei pagamenti BRICS non viene da Washington, ma dal Paese che presiedeva il vertice. Nuova Delhi vuole infrastrutture che rendano più semplice il commercio in rupie e più economiche le rimesse della sua diaspora. Non vuole che queste infrastrutture passino per nodi cinesi, né che il loro effetto netto sia un’espansione dello yuan in Asia meridionale. L’incontro tra Narendra Modi e Xi Jinping a margine del vertice ha segnato un disgelo prudente, ma il disavanzo commerciale indiano verso la Cina, raddoppiato nell’arco di un decennio, resta una frattura che nessun comunicato può ricomporre.
C’è poi l’effetto dell’allargamento. Con undici membri e dieci Paesi partner, il gruppo comprende oggi Stati che nella guerra del 2026 si sono trovati su fronti opposti. A maggio la riunione dei ministri degli Esteri, sempre a Nuova Delhi, si era chiusa senza un comunicato congiunto, costringendo la presidenza indiana a una dichiarazione a titolo proprio. L’unanimità di settembre è stata ottenuta abbassando la soglia degli impegni. La dichiarazione critica dazi e sanzioni unilaterali senza nominare gli Stati Uniti e, sul dossier finanziario, rinvia a un lavoro tecnico di cui non fissa né scadenze né obiettivi. Ajay Srivastava, fondatore del Global Trade Research Initiative, ha osservato che il testo non prevede alcuna azione concreta e che, in assenza di un piano coordinato, il commercio in valute locali potrà crescere solo gradualmente, senza raggiungere volumi significativi.
Va segnalato, per scrupolo di metodo, che alcune testate hanno presentato il vertice come il momento del «lancio» di BRICS Pay. Il testo della dichiarazione, così come riportato dalle fonti che lo hanno esaminato nel dettaglio, non autorizza questa lettura. La confusione tra annuncio e realizzazione è uno dei tratti ricorrenti della comunicazione sul tema, e contribuisce a gonfiare aspettative che poi ricadono sulla credibilità del gruppo.
Le buone ragioni del dollaro
Le statistiche disponibili spiegano meglio di qualsiasi dichiarazione perché la de-dollarizzazione resti, per ora, più un tema di dibattito che una tendenza misurabile. Secondo l’ultima indagine triennale della Banca dei regolamenti internazionali, nell’aprile 2025 il dollaro compariva in circa l’89% delle transazioni valutarie mondiali, una quota in lieve aumento rispetto al 2022, mentre lo yuan si fermava all’8,5%. Sul versante delle riserve, i dati del Fondo monetario internazionale indicano per il primo trimestre del 2026 una quota del dollaro pari al 57,13%, contro l’1,99% della valuta cinese. La tendenza di lungo periodo è di erosione: intorno al 1999 il dollaro superava il 70% delle riserve allocate. Ma la diversificazione si disperde su una costellazione di valute minori, la cui quota residua è più che raddoppiata dal 2021, e non si concentra sulle monete dei Paesi BRICS.
La ragione non è la sudditanza, è il calcolo. Il dollaro offre ciò che nessuna alternativa offre ancora: mercati profondi e liquidi, strumenti di copertura a basso costo, un enorme stock di debito denominato nella stessa valuta e la possibilità di convertire in qualsiasi momento il ricavato di una transazione in un attivo considerato sicuro. Barry Eichengreen ha descritto questi vantaggi in termini di effetti di rete: una moneta è utile in proporzione al numero di soggetti che già la usano, e ciò rende costosa qualunque transizione tentata da un solo attore o da un piccolo gruppo. Per un importatore brasiliano o un esportatore indonesiano pagare in dollari significa pagare nella moneta che la controparte accetta senza trattare.
Scendendo al livello dei singoli membri, il quadro si fa ancora più netto. L’India ha dichiarato a più riprese di non avere interesse a indebolire il dollaro: nel dicembre 2024 il ministro degli Esteri Subrahmanyam Jaishankar ricordava che gli Stati Uniti sono il primo partner commerciale del Paese, e nell’estate 2025 il portavoce del ministero ribadiva che la de-dollarizzazione non rientra nell’agenda finanziaria indiana. Emirati Arabi Uniti e Arabia Saudita mantengono le proprie valute ancorate al dollaro e fondano la propria sicurezza su un rapporto con Washington che nessun circuito di pagamento alternativo potrebbe compensare. Riyadh, del resto, continua a stare nel gruppo in una posizione ambigua: la presidenza indiana la elencava tra gli undici membri, ma a Nuova Delhi la delegazione saudita si è presentata con lo status di Paese invitato. Egitto ed Etiopia, che negli ultimi anni hanno negoziato programmi con il Fondo monetario e portano un debito estero in valuta forte, non possono permettersi di complicare il rapporto con i propri creditori. Il Brasile di Lula ha rilanciato più volte l’idea di una moneta commerciale comune, ma il suo sistema di punta, Pix, rimane un successo domestico.
Restano la Russia e l’Iran, per i quali l’uscita dal dollaro non è una scelta ma una necessità imposta dalle sanzioni, e la Cina, che ha un interesse reale all’internazionalizzazione dello yuan ma lo persegue attraverso infrastrutture proprie, a cominciare da CIPS, e senza rinunciare ai controlli sui capitali che limitano l’attrattiva della sua moneta come riserva. Anche per chi ha le motivazioni più forti, tuttavia, il regolamento in valute locali ha mostrato limiti precisi. L’esperienza russo-indiana è istruttiva. Il forte aumento delle importazioni indiane di petrolio russo dopo il 2022 ha lasciato Mosca con ingenti saldi in rupie difficili da impiegare, un problema che lo stesso Sergej Lavrov ammise pubblicamente nel maggio 2023. Quando gli scambi sono squilibrati, la moneta del Paese in disavanzo si accumula presso il Paese in avanzo, e il dollaro torna a essere la via d’uscita più semplice.
A questi incentivi si somma il costo esplicito di una rottura. Donald Trump ha minacciato dazi del 100% contro i Paesi BRICS che sostenessero una moneta alternativa al dollaro e, dopo il vertice di Rio del 2025, un dazio aggiuntivo del 10% per chi si allineasse alle politiche del gruppo da lui definite antiamericane. Alla vigilia di Nuova Delhi l’economista di Natixis Alicia García-Herrero prevedeva che i leader avrebbero discusso di pagamenti transfrontalieri senza tentare di sostituire il dollaro. È andata esattamente così.
Una scelta politica
Si arriva così al punto centrale. Un sistema di pagamento non è un’infrastruttura neutrale. Susan Strange collocava la struttura finanziaria, cioè il controllo sul credito e sui canali attraverso cui circola, tra le quattro fonti del potere strutturale nell’economia politica internazionale. Gli Stati che controllano i nodi centrali delle reti economiche globali, di cui SWIFT è l’esempio canonico, possano trasformarli in strumenti di coercizione, sfruttandone sia la funzione di osservatorio sia la capacità di esclusione. È proprio questa esperienza, culminata nell’esclusione delle principali banche russe da SWIFT nel 2022, ad aver dato slancio politico al progetto BRICS.
La stessa lezione, però, vale all’interno del gruppo. Chi costruisce una rete alternativa deve stabilire dove si trovano i nodi, chi ne gestisce i dati, quale diritto regola le controversie, chi fornisce liquidità nei momenti di tensione e come si compensano i saldi tra economie in avanzo e in disavanzo. Ognuna di queste decisioni redistribuisce potere. Per l’India un sistema imperniato su CIPS significherebbe sostituire una dipendenza da Washington con una dipendenza da Pechino, cioè da un rivale con cui condivide una frontiera contesa. Per gli Emirati collegarsi a un circuito in cui transita l’Iran vorrebbe dire esporsi al rischio di sanzioni secondarie, proprio mentre i due Paesi escono da una guerra vissuta su fronti opposti. Il problema non è la tecnologia: le componenti nazionali esistono e funzionano. Manca un accordo su chi governa l’insieme.
La storia monetaria del Novecento offre due riferimenti utili. Il primo è la proposta keynesiana di una International Clearing Union, presentata dal Tesoro britannico nel 1943, che affrontava esattamente il nodo degli squilibri persistenti imponendo oneri simmetrici ai Paesi in avanzo e a quelli in disavanzo. Un BRICS Pay che volesse andare oltre la messaggistica avrebbe bisogno di un meccanismo analogo di compensazione multilaterale, e dunque di regole capaci di vincolare anche la Cina, principale creditore commerciale del gruppo. Il secondo riferimento è la tesi di Charles Kindleberger sulla stabilità del sistema internazionale come bene pubblico, che richiede un attore disposto a sostenerne i costi. Nell’ordine del dollaro quel ruolo è svolto, con tutti gli abusi che ne derivano, dagli Stati Uniti. Nel partenariato BRICS l’unico candidato plausibile è la Cina, e gli altri membri non intendono riconoscerle quella funzione. Qui sta il dilemma costitutivo di un ordine monetario multipolare: moltiplica i poli, ma lascia vacante il posto di chi garantisce il sistema.
A ciò si aggiunge la fragilità istituzionale. Il gruppo opera senza un segretariato permanente, con presidenze annuali a rotazione che affidano la continuità dei dossier tecnici alla volontà del Paese di turno. L’allargamento ha accresciuto l’eterogeneità degli interessi senza dotare il partenariato di strumenti decisionali più robusti. Un sistema di pagamento unificato richiederebbe un trattato, o almeno un accordo vincolante di governance, mentre l’iniziativa sui pagamenti transfrontalieri è, per esplicita scelta dei firmatari, volontaria e non vincolante. Finché questa asimmetria tra ambizione e forma giuridica non sarà sciolta, BRICS Pay resterà ciò che è oggi: un marchio politico sovrapposto a un insieme di corridoi bilaterali. La stabilità del partenariato non è dunque una condizione accessoria del progetto. Ne è il presupposto.
Verso la presidenza cinese del 2027
Con il passaggio della presidenza alla Cina per il 2027, l’orizzonte di valutazione più utile è quello dei prossimi diciotto-ventiquattro mesi. Le valutazioni che seguono poggiano su evidenze di qualità moderata, costituite in larga parte dai testi ufficiali e dalla stampa economica internazionale.
Lo scenario che considero altamente probabile è quello di un mosaico bilaterale. Crescono i corridoi già avviati, come quelli tra India ed Emirati e tra India e Russia, mentre l’architettura comune resta allo stadio di studio. Il commercio in valute locali aumenta in termini assoluti, ma la quota del dollaro negli scambi intra-BRICS si riduce solo in misura marginale.
Uno scenario alternativo, cui attribuisco una probabilità moderata, prevede che la presidenza cinese usi il 2027 per promuovere un nucleo a geometria variabile, costruito attorno a CIPS e SPFS, con l’adesione di Russia, Iran e di alcuni Paesi partner. Il marchio BRICS Pay verrebbe formalmente attivato, ma per una parte soltanto del gruppo e con ogni probabilità senza l’India. Sarebbe un risultato politicamente spendibile per Pechino e Mosca, ma renderebbe esplicita la frattura che oggi il linguaggio delle dichiarazioni riesce ancora a coprire.
L’entrata in funzione, entro il 2028, di un sistema unificato e operativo per tutti i membri resta invece altamente improbabile.
Gli indicatori da seguire sono pochi e concreti: la pubblicazione del rapporto tecnico accolto a Rio; l’eventuale firma di un accordo vincolante sulla governance dei pagamenti; la creazione di un meccanismo multilaterale di compensazione o di linee di swap dedicate, magari affidate alla Nuova Banca di Sviluppo; la posizione indiana su un collegamento con CIPS; la formalizzazione, o il definitivo abbandono, della membership saudita. Un comunicato che parli di «lancio» senza alcuno di questi elementi andrà letto per ciò che è, un annuncio.
Il multipolarismo ha finora prodotto soprattutto una pluralità di opzioni nazionali, utili a ciascun Paese per ridurre l’esposizione alle sanzioni e per negoziare da posizioni migliori con Washington. Trasformare queste opzioni in un sistema richiede un partenariato che riconosca un interesse comune più forte delle rivalità interne. Quel partenariato è ancora in evoluzione, e BRICS Pay ne seguirà i tempi, non il contrario.