❌

Reading view

The Federal Government Collected $5.4 Trillion. It Still Can't Pay Its Bills.
U.S. Capitol in red as money falls around it | Illustration: Nikolai Sorokin/Songquan Deng/Dreamstime

The federal government just closed fiscal year 2026 with a deficit of nearly $2 trillion, according to figures the Congressional Budget Office (CBO) released last Thursday. Only the two pandemic years of 2020 and 2021 were worse. Today, though, there is no recession and no emergency. These enormous budget deficits are the new normal.

The usual response to a deficit warning is that the government just needs more money. It doesn't. Thanks to the remarkable strength of the private sector, federal revenue rose by 3 percent, to more than $5.4 trillion, over the fiscal year. But spending rose by 6 percent, reaching $7.4 trillion.

Some will blame the Supreme Court for striking down most of President Donald Trump's tariffs and forcing the government to issue refunds. But even if Washington had kept the $130 billion in illegal levies, it would cover less than one-tenth of the gap. Tariffs were never a serious revenue source at our insanely high level of spending.

Look at where the money went. Spending on the three main entitlement programs—Social Security, Medicare and Medicaid—grew by 7 percent. That's faster than total spending growth. Defense grew by 5 percent. Interest on the debt rose by 11 percent, exceeding $1.1 trillion. That last figure is the bill for every earlier year of borrowing—years when Washington was sending clear signals that it isn't serious about fiscal responsibility.

If you want to see where such irresponsibility can lead, look at France. The country that big spenders from Paul Krugman to Sen. Bernie Sanders (I–Vt.) have cited as proof that big government is viable and full of upsides is now on the brink of a serious crisis. France's debt equals 120 percent of its gross domestic product (GDP), and interest payments are rising quickly. Slow growth and social unrest aren't helping.

The U.S., of course, has some advantages that France doesn't, largely because we're a country of innovators with a private sector unmatched at creating wealth. Nonetheless, debt that is swelling out of control should still worry us. First, the same anti-wealth and anti-growth forces that brought France to where it is now are gaining popularity here. Second, we too will see debt reach 120 percent of GDP in a few years, and our interest payments are already consuming an alarming share of resources.

A wise Congress would put us on safer footing if only because debt raises interest rates for everyone, from homebuyers to small businesses. This operates as a drag on growth, and hence on wages. In other words, controlling debt should be part of an affordability agenda in the same way as streamlining regulation.

When legislators decide to take affordability seriously, I recommend looking at a September Advancing American Freedom (AAF) report on this topic. Its section on fiscal restraint offers a useful menu of reforms, including targeting the programs that most drive the debt.

Start with Social Security. Under current law, benefits will be cut by roughly 20 percent when the program's trust fund runs dry in the early 2030s. Nobody believes Congress will actually let that happen, but we'd better hope its answer isn't to double down by borrowing the difference between payroll taxes and benefits.

Nor are tax increases an option. The payroll tax meant to fund entitlements is now 12.4 percent of wages. It began at 2 percent when Social Security was first rolled out. It is also the most burdensome tax for many Americans. Enough already. The fixes AAF fellow Rachel Greszler proposes are worth considering: Index the retirement age to life expectancy, use an accurate inflation measure for cost-of-living adjustments, and move gradually toward a flat universal benefit that protects lower-income retirees while ending Social Security's de facto welfare for the wealthiest.

Next is Medicare. More than 40 percent of its financing already comes from general revenue rather than from payroll taxes. The report recommends converting the program to premium support, giving beneficiaries a fixed contribution to spend on traditional Medicare or on competing private plans. It would also raise the eligibility age to 67, matching Social Security, and trim subsidies for well-off seniors. That's a start.

As for Medicaid, the problem is one of pricing. And yet competition based on price—the best cost-control tool—has never been seriously tried. Washington covers 90 percent of the cost of states' expanded Medicaid programs for adults. A state can buy a dollar of spending with just a dime of its own money. Changing the states' incentives would be key here. Implementing risk-adjusted per-capita caps, through which the federal government would give states a fixed amount per enrollee, would do just that. States would pay for their own inefficiencies or would be able to use every dollar they save by becoming more efficient.

The same logic supports returning more welfare programs to states, starting with the federal share of the Supplemental Nutrition Assistance Program. State governments have to balance their budgets in some form.

None of these reforms are painless. But the alternatives will prove far more painful. The U.S. will either continue paying a slow, unlegislated tax called inflation or face a fast, ugly fiscal crisis when bond buyers stop giving Washington the benefit of the doubt.

COPYRIGHT 2026 CREATORS.COM

The post The Federal Government Collected $5.4 Trillion. It Still Can't Pay Its Bills. appeared first on Reason Magazine.
  •  

Ukraine’s war budget has $52 billion hole, and army needs $45 billion more on top

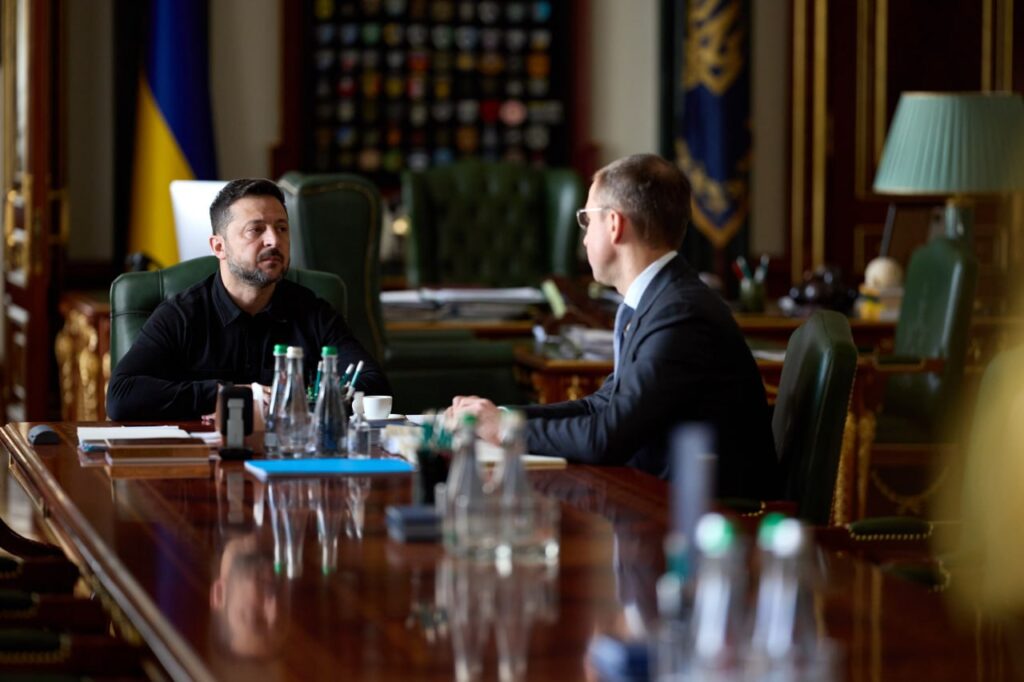
zelenskyy with koretskyi

Ukraine is seeking fresh funding for 2027 and says it is ready to deliver the reforms. Prime Minister Serhii Koretskyi says Ukraine’s external budget financing need for 2027 exceeds $52 billion, with more than $32.6 billion still to be raised.

That money underwrites the basics of a country at war: the army, pensions, hospitals, and support for business, he notes. Defense and security alone will take almost 44 percent of GDP in the 2027 budget, and the gap comes as Russia keeps hammering the infrastructure that generates Ukraine’s own revenue.

“The defense capability of the country, the payment of pensions, the support of hospitals and business depend on these funds,” Koretskyi says.

The hole Russia keeps digging faster than Kyiv can fill it

Russia’s strikes widen the gap even as Kyiv tries to close it. Russia systematically attacks critical infrastructure, business, production and civilian sites, and the destruction and halted enterprises will leave tax revenues about $1.5 billion below forecast by the end of the year, he warns.

For instance, output of Ukraine's steel industry, one of the pillars of its wartime economy, fell 57.3% in August due to Russian strikes. This sector is Ukraine's second-largest foreign-currency earner, employing more than 70,000 people directly and another 250,000 in related industries, and paying close to $1 billion a year in taxes.

Beyond the budget itself, the off-budget needs of Ukraine’s Defense Forces for 2027 are estimated at $45 billion, or about 40 billion euros, a figure that sits on top of the $52 billion budget requirement, he says.

The reforms Kyiv must deliver to unlock the money

The money hinges on reforms Ukraine still has to deliver. In the next few days, the government is to approve all the decisions needed to continue financing.

“Ukraine continues to work on fulfilling its part of the commitments. This week, the government is expected to approve all the necessary decisions to ensure continued funding,” the Ukrainian prime minister says.

Meanwhile, the Parliament plans to consider the bills required under the support programs of the IMF, the World Bank and the EU.

  •  

Leaders eye deep EU budget cuts, while long-term joint borrowing becomes the new normal

Last Saturday, the Irish presidency of the EU proposed cutting nearly €160bn from the EU’s next seven-year budget against the European Commission’s proposal, a bid to bring the wealthiest, frugal member states on board. The deepest cuts fall on competitiveness (€75bn), external action (almost €38bn) and the EU’s administration costs (€10bn).

What the plan leaves alone is the borrowing.

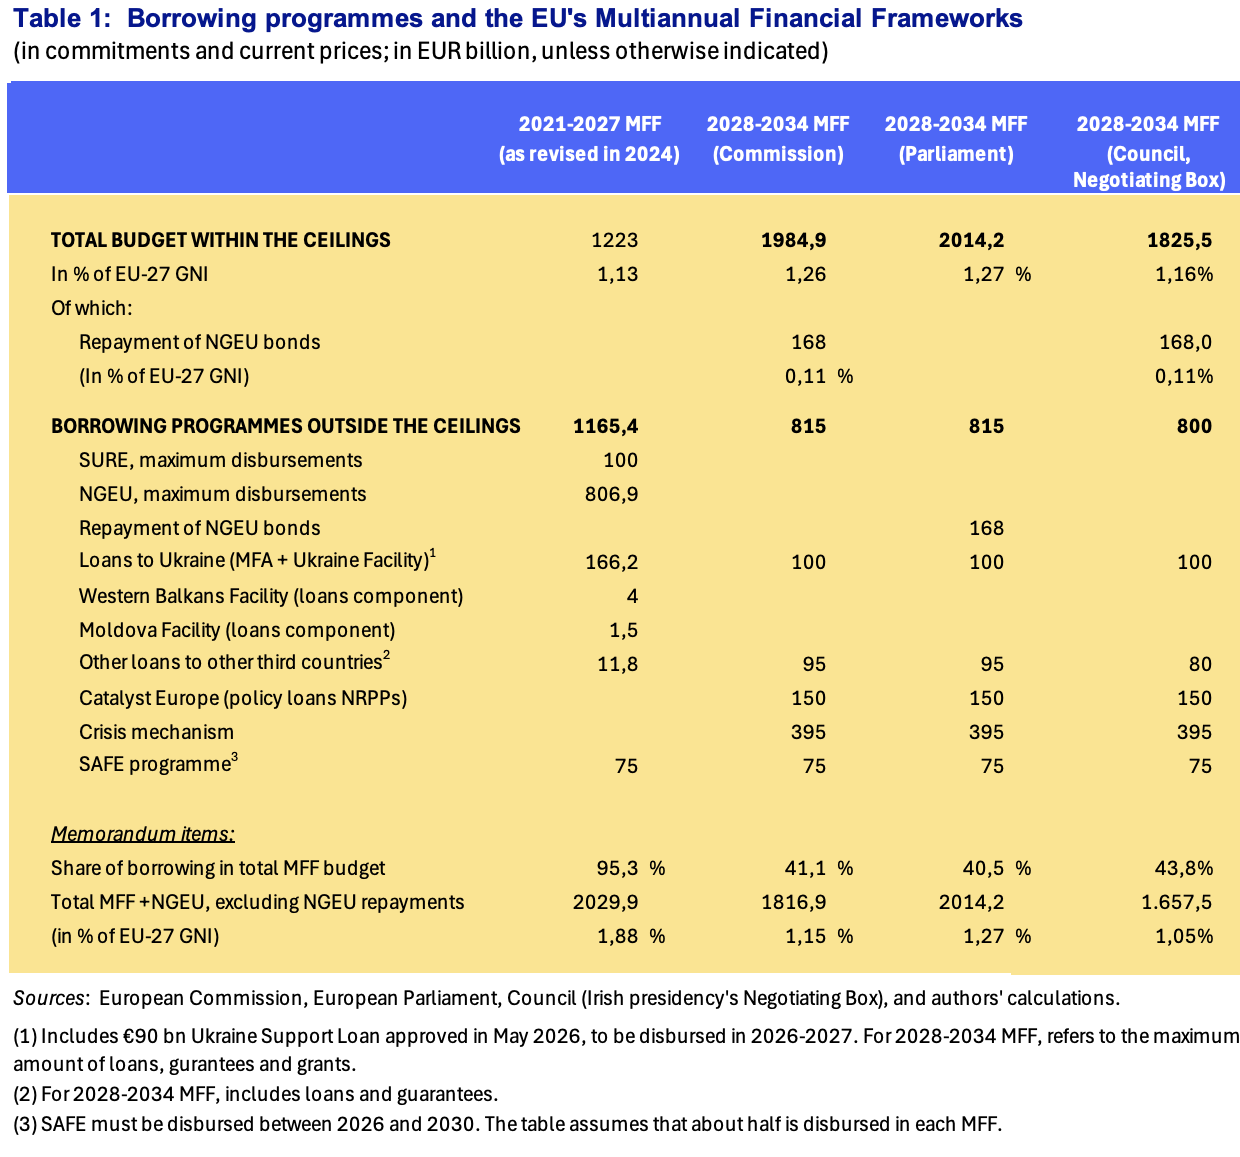
The Irish text, known in Brussels as the negobox, keeps all three of the commission’s borrowing programmes that sit outside the budget’s normal limits: Catalyst Europe, a €150bn lending facility; a crisis mechanism of up to €395bn for major unforeseen shocks; and support for Ukraine of up to €100bn.

Add loans for defence and lending to other non-EU countries and, by our estimates, joint borrowing could still equal around 44 per cent of the new budget, about €800bn at current prices, up from 41 per cent under the Commission’s proposal. The budget shrinks, but the borrowing hardly changes. 

Ireland’s proposed budget is too small for Europe’s mounting common challenges, and its borrowing approach is too ad hoc and risky. 

Excluding the distorting effects of NextGenerationEU (NGEU), the Covid recovery fund, the Commission’s budget proposal is already far smaller than the headline figures suggest, and Ireland’s proposal would make it smaller still.

That matters because, as the Draghi report argued, Europe’s shared challenges such as Ukraine, rearmament and competitiveness require European public goods because no single member state captures their full benefits.

A budget worth just over one percent of the EU’s gross national income (GNI) is a poor match for that responsibility.

By comparison, total government expenditure across EU countries comes to close to half of their combined GNI. Keeping most fiscal capacity at national level, while expecting such a modest EU budget to finance increasingly vital continental priorities, is a bad use of public resources. 

A stronger common budget needs more of its own revenue, at least what the Commission proposes in its Own Resources Decision, which Parliament broadly supports and which would raise nearly €60bn extra a year.

The Irish plan’s acceptance of five new resources is encouraging. But it has to survive the negotiations, and the details of the final reform will decide whether it means anything.

The Council’s approach to common borrowing remains haphazard, lacking a permanent framework and relying on crisis-driven compromises. Governments may not like it, but a more European approach is coming, and the €800bn is likely to grow.

Support for Kyiv, to be provided outside budget ceilings via the Ukraine Reserve and policy loans, is capped at €100bn for the whole period. This is already looking tight given the accelerating rate of disbursements to Ukraine seen in recent years.

And a successor to SAFE, the EU’s defence loan scheme, is widely expected, since €150bn has proved far from enough for Europe’s rearmament.

France has just shown what it costs to borrow alone. Its yields recently hit a 24-year high, and the state now pays more to borrow than some major French companies. Sharing the effort through the common budget, including prudent joint borrowing, would help spread that risk.

Yet Europe has no clear, sustainable plan for borrowing. To date, EU governments have reluctantly signed up to each new borrowing instrument and called it an exception.

European borrowing capacity has been assembled one crisis at a time, starting with the euro area crisis and accelerating since the pandemic.

NGEU was accepted by fiscally cautious states as a one-off decision to deal with the Covid-19 emergency. Then the war in Ukraine and the need to fund rearmament produced new exceptions.

This year, EU governments used enhanced cooperation, a procedure that lets a subset of member states go ahead without the rest, to approve the €90bn Ukraine Support Loan, the EU’s largest foreign loan ever.

For defence, they reached for Article 122, the treaties’ emergency clause, to set up SAFE. Parliament, which felt sidelined, decided to sue the Council before the European Court of Justice.

There is a catch though.

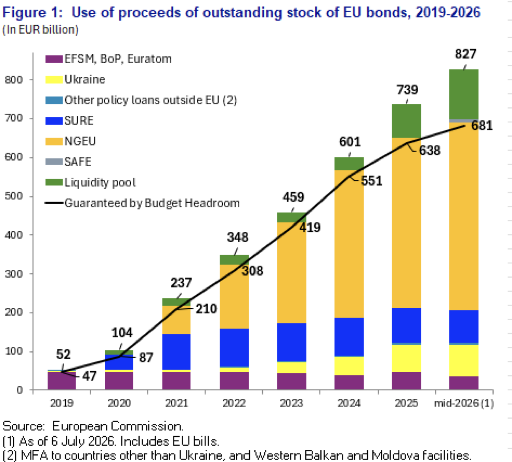
These exceptional programmes are guaranteed by the so-called budget headroom, the margin between the EU’s revenue ceiling and the spending limits in the seven-year budget, rather than by money set aside in advance.

In barely five years, headroom-backed exposure has climbed to €681bn (see Figure 1), 82 percent of all EU debt.

The European Court of Auditors has warned that if a Ukraine loan guaranteed this way goes bad, future EU budgets, and the national contributions that fund them, would have to cover the loss.

Frugals vs Friends of Cohesion

EU capitals remain divided over the new budget and over joint borrowing. Net contributors, sometimes referred to as the Frugal Six, want deep cuts in the commission’s proposal, argue that new common borrowing is not the solution and have misgivings about the creation of new own resources.

By contrast, a group of sixteen southern and eastern countries, that call themselves the “Friends of Cohesion”, are much more open to joint borrowing and back an approach closer to the Commission and Parliament on the budget and own resources.

Ireland’s plan largely reflects the influence of the frugal countries, yet one diplomat has already dismissed it as “not even close to a landing zone.”

Europe needs an ambitious budget, backed by at least the Commission’s proposed new own resources, so it relies less on national contributions based on GNI. Joint borrowing should become a permanent, predictable part of it, with safeguards.

First, it should fund loans, not grants, as the Commission suggests. Second, riskier exposures, especially to non-EU countries, should be at least partly backed by money set aside in advance, as the Court of Auditors recommends.

Where it makes sense, the headroom guarantee could be topped up with national guarantees in proportion to each country’s size, as under SURE, and like-minded partners outside the EU could sometimes take part.

Stronger capital at institutions such as the EIB, or at any future defence-financing vehicle, would also let Europe borrow more together without putting its creditworthiness at risk.

Governments should also consider deferring repayment of the NGEU bonds, as the Draghi report suggested, especially if the own-resources reform falls short. It would protect priority spending when it is needed most.

Sustained joint borrowing brings a bonus: more common safe assets in euros, which strengthens the euro’s international role. The demand is already there.

Last month Piotr Serafin, the EU’s budget commissioner, flew to Seoul and Tokyo to meet investors. Asian buyers’ share of EU bond syndications has risen from 5 per cent to 9 per cent in the second half of 2025.

Wobbles in US bond markets, which partly reflect doubts about America’s fiscal health, its reliability as a partner and the dollar’s safe-haven status, give the euro an opening.

But it can only take it if EU governments put their own fiscal houses in order.

Ongoing tensions in the French bond market provide a clear warning. Putting France’s finances on a sustainable path would do more than reassure markets about the euro. It would restore French debt as a safe euro asset.

EU leaders meet on Thursday and Friday in Brussels. Whatever they discuss (and later decide) on the budget, Europe should keep borrowing together, and in large amounts.

The task now is to give that borrowing a coherent plan: a permanent framework, money set aside in advance and safeguards that cautious capitals can accept.

  •  

European Regions Warn Brussels That New EU Budget Could Concentrate Wealth and Power in National Capitals

European regional and local leaders have warned that the EU’s next long-term budget risks transferring control over investment programmes to national governments, potentially increasing economic disparities and reducing the ability of poorer regions to shape their own development.

The warning was delivered in Brussels on 12 October by Kata Tüttő, President of the European Committee of the Regions, during the opening of the European Week of Regions and Cities.

Her intervention comes as EU leaders prepare to negotiate the 2028–2034 budget, with disagreements over agricultural funding, regional development, defence, industrial competitiveness and the distribution of financial responsibilities among member states.

The Committee of the Regions warned that greater centralisation could concentrate economic opportunities in already prosperous areas while limiting other territories’ capacity to attract investment and develop essential infrastructure.

The concern goes beyond money allocated to regional development. It addresses who controls spending decisions and whether local authorities retain a meaningful role in determining how European funds are used.

Regional governments resist centralisation

EU cohesion policy has traditionally sought to reduce disparities between richer and poorer regions through investment in transport, infrastructure, education, business development and public services. While national governments administer considerable funds, regional and local authorities are frequently involved in identifying priorities and delivering projects.

The Committee argues that restructuring which concentrates decision-making at national level could weaken this arrangement. National governments may favour country-wide industrial or infrastructure programmes, while regional authorities identify specific problems arising from local conditions.

A national infrastructure strategy could prioritise major transport routes and industrial centres. Regional administrations might instead emphasise connecting smaller communities, maintaining local services or developing specialised economic activities.

The dispute concerns whether the next EU budget will maintain flexibility for regional priorities. In Belgium, Germany, Spain and Italy, regional institutions possess important responsibilities across economic development, education and infrastructure. Changes to EU spending governance could alter established relations between European, national and regional institutions.

The budget negotiations intensify the dispute

Ireland’s rotating Council presidency has proposed reducing the Commission’s original seven-year budget plans by approximately €141 billion while largely protecting agriculture and cohesion compared with other expenditure categories.

The proposed financial framework would nevertheless remain substantially larger than the current budget. The distribution of resources remains contentious, and an overall cut does not necessarily translate into the same reduction for every region.

Effects will depend on allocation formulas, national spending plans and programme governance. Meanwhile, European institutions face demands for stronger investment in defence production, digital infrastructure, competitiveness and support for Ukraine while maintaining agricultural and regional commitments.

Economic disparities remain a European problem

The Committee presented its seventh annual assessment of Europe’s regions and cities during the European Week of Regions and Cities, held in Brussels from 12 to 14 October.

The assessment examines competitiveness, resilience, public services, democratic governance and financial conditions. Regional disparities remain a significant feature of the EU economy despite decades of common investment programmes.

Large metropolitan areas often benefit from concentrations of universities, research institutions, advanced industries and capital. Less densely populated territories may struggle with demographic decline, shortages of skilled workers and the cost of maintaining infrastructure.

These differences can reinforce themselves over time. Businesses invest where suitable workers, transport networks and customers are already concentrated. Younger workers moving towards metropolitan economies may further reduce the economic prospects of communities they leave behind.

Defence spending creates new pressures

The increase in European defence expenditure introduces another dimension. Regions containing defence manufacturers, engineering firms, research institutions and military installations could benefit substantially from new spending, while others may receive little direct economic advantage.

If industrial investment concentrates in already advanced manufacturing centres, geographical disparities could widen. Conversely, procurement programmes and infrastructure investment could bring opportunities to weaker regional economies with suitable facilities and labour.

A question of political authority

The Committee of the Regions has limited formal authority over the EU’s long-term budget. National governments will negotiate the framework, and the European Parliament must consent to the final agreement.

Regional leaders are seeking to influence those negotiations before political compromises are established. Their central argument is that aggregate European economic growth alone does not capture the distribution of investment, employment and public services across the Union.

The approaching European Council negotiations will indicate whether governments intend to preserve regional influence over EU spending or concentrate greater authority over investment decisions at national level.

  •  

EU Budget Battle Deepens as €141 Billion in Proposed Cuts Threatens Defence and Competitiveness Funding

European Union governments are entering a critical round of budget negotiations after the Irish presidency of the Council proposed cutting €141 billion from the European Commission’s long-term spending plans, exposing deep disagreements over how the bloc intends to finance its expanding responsibilities.

The revised proposal, circulated ahead of the European Council meeting scheduled for 15–16 October, would reduce the planned 2028–2034 financial framework by approximately eight per cent to around €1.6 trillion, calculated in constant prices.

Despite the reduction, the proposed budget remains approximately 30 per cent larger than the current seven-year framework. Germany, Sweden, the Netherlands and other governments concerned about national contributions have nevertheless argued that further restraint is necessary.

The compromise, detailed in negotiations over the EU’s next financial framework, reduces proposed spending across several areas while largely protecting the Union’s established agricultural and regional development programmes. The distribution of those cuts is becoming as contentious as the overall size of the budget.

Europe’s new priorities face the deepest reductions

Under the Irish proposal, agricultural and regional development allocations would decline by approximately three per cent compared with the Commission’s initial plans. By contrast, funding intended for competitiveness and security would be reduced by around 13 per cent, while external action and development cooperation face cuts of approximately 17 per cent.

The difference raises questions about whether the next EU budget can support the strategic ambitions repeatedly endorsed by European leaders.

The Commission has presented industrial competitiveness, technological development, defence readiness and economic resilience as central priorities for the remainder of the decade. Yet these sectors would absorb proportionately larger reductions under the revised framework than agricultural and cohesion programmes.

The consequences could extend to investments in advanced technologies, European industrial supply chains, research programmes and cross-border defence cooperation. They could also constrain the Union’s capacity to fund external partnerships and development initiatives.

The debate is particularly sensitive because the EU’s responsibilities have changed considerably since the previous budget was negotiated. Russia’s invasion of Ukraine has increased defence requirements, while competition with China and the United States has intensified demands for industrial investment.

Germany and the net contributors demand restraint

The central disagreement concerns how much additional expenditure European governments are willing to finance through the common budget. Germany and other major net contributors face domestic fiscal constraints, rising borrowing costs and demands to increase national defence spending.

For these governments, accepting a substantially larger EU budget would add to financial commitments already being made through national budgets.

The Irish compromise therefore faces opposition from two directions. Some governments consider the reductions insufficient, while others fear that the remaining cuts will weaken programmes essential to their national economies.

Traditional recipients of agricultural and regional funding have an interest in protecting established expenditure. Governments seeking stronger European investment in defence, innovation and industrial competitiveness have different priorities.

The European Parliament is another obstacle. Its consent will be required before the final financial framework can enter into force, giving MEPs considerable leverage in negotiations with national governments.

New EU revenues remain controversial

The proposal also envisages approximately €55 billion in additional annual financing through new or revised EU revenue sources, including customs revenues, emissions-related income and corporate contributions.

The Commission’s framework for the next long-term budget reflects a broader debate over the extent to which the Union should develop independent financing mechanisms rather than rely predominantly on national contributions.

Such mechanisms would potentially give Brussels a more predictable revenue base. However, they also raise questions about fiscal sovereignty, the distribution of costs among member states and the political accountability of European taxation.

National governments remain reluctant to surrender substantial authority over revenue collection, particularly when proposed resources could impose costs on domestic industries or consumers.

Ukraine, enlargement and Europe’s strategic ambitions

The negotiations will influence the Union’s ability to respond to future enlargement. Ukraine and several Western Balkan countries are pursuing accession, but the financial implications of bringing additional members into the Union remain substantial.

Existing arrangements for agricultural subsidies and regional development assistance would require reconsideration if large new beneficiaries entered the budgetary system.

At the same time, the EU faces pressure to support Ukraine financially and strengthen defence production without depending indefinitely on extraordinary borrowing or ad hoc national contributions. These responsibilities cannot be addressed simply by preserving the structure of earlier budgets.

European Council President António Costa will seek to narrow the divisions among the 27 leaders, but agreement on the financial framework requires unanimity. Any government can withhold its consent if it considers the final distribution of costs unacceptable.

The forthcoming summit is therefore likely to establish the parameters of further negotiations rather than eliminate the underlying disagreements. The immediate political question is whether member states can reconcile their commitment to greater European strategic capacity with their reluctance to finance it collectively.

  •  

MEPs don’t have to meekly accept an EU budget deal, but will they go to war over €141bn in cuts?

Getting co-decision powers on the budget, finally enshrined in the Lisbon Treaty after more than a decade of inter-institutional battles, was one of the European Parliament’s big wins. 

The challenge facing MEPs in the coming months is whether they are really going to use those powers on the 2028-34 budget. 

The early signs are that they are spoiling for a fight. The Irish government’s compromise proposal tabled on Saturday (10 October) – an 8 percent cut worth €141bn to the European Commission’s spending plan – isn’t exactly butchery. 

But it does display a startling lack of ambition, in particular on the raft of ‘own resources’ proposed by MEPs to make the budget process less vulnerable to member states wanting to reduce or at least freeze their annual contributions  

This time round, MEPs have proposed a digital services levy, an online gambling levy, and a levy on crypto-asset capital gains.

Put together the parliament reckons that these new taxes could bring an additional €30bn to the EU’s budget, on top of the €57.4bn that the EU commission believes can be raised from other levies, such as the emissions trading scheme and the carbon border levy. 

This article continues, but the full version is available only to EUobserver.com subscribers. Visit account.euobserver.com/membership

  •  

EU Leaders Face Confrontation Over Energy Prices, Ukraine and Russia at October Summit

European Union leaders will meet in Brussels on 15–16 October under pressure to address surging energy costs, Russian hybrid attacks, continued support for Ukraine and the bloc’s next long-term budget. The summit comes as economic pressures expose growing differences between national governments.

European Union leaders are preparing for a two-day summit in Brussels dominated by the economic consequences of the Middle East conflict, Russia’s continuing war against Ukraine and mounting pressure on governments to reconcile defence commitments with deteriorating public finances.

The European Council meeting on 15–16 October will bring together the leaders of the 27 member states to consider immediate measures addressing high energy prices alongside longer-term decisions on competitiveness, enlargement, migration and the EU’s budget for 2028–2034.

European Council President António Costa has placed economic competitiveness and energy costs at the centre of the discussions, reflecting concerns that the disruption of global oil and gas markets is threatening the bloc’s industrial recovery.

The meeting also takes place against the background of renewed disputes over national spending limits, with Italy and Greece seeking greater freedom to finance energy relief and France facing increasing pressure over the credibility of its budget.

Energy crisis puts fiscal rules under pressure

The Middle East conflict has created a renewed energy shock for European economies, raising transport and industrial costs while pushing inflation higher.

The disruption of shipping through the Strait of Hormuz has also affected global oil supplies, exposing Europe’s continuing dependence on internationally traded fossil fuels despite efforts to diversify imports following Russia’s invasion of Ukraine.

European leaders are expected to consider targeted and temporary support measures for households and businesses, as well as longer-term policies intended to reduce energy dependence.

The political disagreement concerns how those measures should be financed.

The European Commission has resisted requests from Italy and Greece for further exemptions from the EU’s fiscal framework. Both governments argue that extraordinary energy costs require additional budgetary flexibility.

Brussels maintains that existing provisions already permit exceptional expenditure within defined limits.

The disagreement is particularly difficult for indebted governments that must simultaneously finance military expansion, maintain public services and protect their economies from energy inflation.

France’s position has added urgency to the debate. Its borrowing costs have increased sharply as investors question whether the government can adopt a credible budget ahead of the 2027 presidential election.

A summit agreement on emergency energy assistance would therefore have to accommodate substantially different national fiscal circumstances.

Ukraine and the changing transatlantic relationship

Support for Ukraine remains a central item on the summit agenda as Russia continues attacks against Ukrainian cities, energy infrastructure and industrial facilities.

EU leaders are expected to review military and financial assistance, the implementation of sanctions against Moscow and the resilience of Ukraine’s economy.

The discussions take place amid renewed uncertainty surrounding American weapons deliveries.

Washington’s reported threats to suspend supplies under the NATO-backed PURL procurement arrangement have raised further questions about Europe’s dependence on the United States for advanced military equipment.

European governments have increased defence expenditure and committed additional support to Ukraine, but replacing American capabilities remains difficult, particularly in air defence, precision-guided weapons and certain intelligence systems.

The summit is unlikely to resolve those industrial limitations, but the broader question of Europe’s ability to sustain Ukrainian defence over several years will influence discussions.

Member states must also consider how increased defence expenditure will be financed alongside other demands on national budgets.

Russian hybrid operations move higher on the agenda

The EU’s published summit agenda includes Russian-linked hybrid attacks within Europe.

The issue has gained prominence as European governments investigate sabotage, cyber operations, information interference and threats against infrastructure and defence-related industries.

Recent warnings concerning possible Russian assassination operations targeting European defence executives and employees of companies supplying Ukraine illustrate the changing nature of the security threat.

Such activities place additional demands on national intelligence services, police forces and European institutions responsible for cross-border cooperation.

The EU has strengthened its sanctions instruments against hybrid activities, but enforcement remains dependent on coordination between national authorities.

Any further measures would need to address intelligence sharing, protection of critical infrastructure and the relationship between internal security and the Union’s wider Russia policy.

A larger EU with a contested budget

Enlargement will form another important part of the discussions following the Commission’s proposals for preparing a wider Union.

Brussels has outlined possible institutional safeguards intended to prevent future members from undermining democratic standards or blocking common decisions.

Montenegro and Albania are advancing through their accession negotiations, while Ukraine and Moldova remain central to the EU’s geopolitical enlargement strategy.

The financial implications will become increasingly important as governments negotiate the next multiannual financial framework covering 2028–2034.

Existing members are already divided over how much the EU should spend, which programmes should receive priority and whether additional common resources should be raised.

Agricultural expenditure, cohesion funding, defence investment and support for Ukraine will compete for resources within the same budget negotiations.

The Commission argues that enlargement can be accommodated through targeted reforms, but securing agreement among member states will require decisions on future expenditure and the distribution of financial benefits.

Competitiveness and the single market

Leaders will also examine progress on the One Europe, One Market agenda, which aims to reduce barriers to economic activity within the EU and improve conditions for European businesses.

The initiative is intended to address structural weaknesses affecting investment, industrial development and the ability of European companies to compete internationally.

High energy prices have made those concerns more immediate, particularly for industries competing against producers in economies where electricity and fuel are cheaper.

The European Council will be asked to provide direction on measures planned for 2026 and 2027, but implementation will depend on subsequent legislation and decisions by member states.

The October meeting brings several unresolved European policy questions into the same negotiation: how to protect economic competitiveness, maintain fiscal credibility, finance defence, sustain Ukraine and prepare for enlargement.

The immediate test will be whether leaders can agree on a credible response to energy prices without reopening broader disputes over national budgets.

More difficult decisions concerning defence financing, institutional reform and the EU’s long-term expenditure commitments will extend well beyond the two-day summit.

  •  

France’s Debt Crisis Deepens as Eurozone Ministers Demand Credible Budget

France faces growing pressure from eurozone governments and financial markets to secure its 2027 budget as borrowing costs climb towards levels not seen for more than two decades, raising questions about Paris’s ability to restore control over its public finances.

France is coming under increasingly direct pressure from its eurozone partners to resolve the political dispute surrounding its 2027 budget, with European finance ministers warning that continued uncertainty threatens confidence in the country’s public finances.

The warning follows a sharp increase in French government borrowing costs. Yields on ten-year sovereign bonds have risen by nearly 80 basis points since September, reaching levels last recorded in 2002. Investors are demanding higher returns to finance a government whose debt continues to increase while its capacity to impose spending restraint remains constrained by parliamentary divisions.

At the Eurogroup’s October discussions, finance ministers and European Central Bank officials pressed Paris to demonstrate that it can adopt a credible budget and comply with its commitments under the EU’s fiscal framework.

France’s difficulties have implications beyond its domestic politics. As the eurozone’s second-largest economy, France occupies a position fundamentally different from smaller countries that experienced sovereign debt crises during the previous decade.

Borrowing costs expose political weakness

The French government expects to borrow approximately €340 billion in 2027, making continued access to financial markets at sustainable rates an essential element of its fiscal strategy.

That financing requirement reflects both the need to cover the annual deficit and to refinance existing debt as government securities mature.

France’s public debt is already approaching 120 per cent of gross domestic product. As EU Today previously reported, official projections indicated that the debt ratio could reach 121.7 per cent in 2027, up from 115.7 per cent at the end of 2025.

The latest increase in yields adds another complication. Higher interest costs do not affect the entire stock of debt immediately because much of it was issued at earlier rates. They do, however, increase the cost of new borrowing and refinancing, progressively reducing the money available for other government commitments.

France also faces a difficult political timetable. With the presidential election approaching in 2027, parties are reluctant to accept measures involving spending reductions, higher taxation or changes to public services.

Prime Minister Sébastien Lecornu’s government has been attempting to reduce the deficit from an estimated 5.4 per cent of GDP in 2026 towards five per cent. Even that objective remains substantially above the EU’s three per cent reference value.

Brussels has limited room to compromise

Economic Commissioner Valdis Dombrovskis has emphasised the importance of predictable fiscal policy and credible deficit reduction.

France is already subject to the EU’s excessive deficit procedure, under which member states must demonstrate progress towards agreed fiscal objectives.

The reformed European fiscal framework permits certain deviations from expenditure commitments in exceptional circumstances, but it does not provide an unrestricted exemption from debt sustainability requirements.

Paris therefore faces a double constraint. It must convince domestic political forces to support a budget while demonstrating to Brussels that its spending plans are sufficiently credible.

The danger is not necessarily an immediate financing crisis. France retains a large, diversified economy, deep financial markets and substantial tax-raising capacity.

The more immediate risk is that prolonged political deadlock produces progressively higher borrowing costs, making future fiscal adjustments more expensive.

Why the ECB cannot simply intervene

The European Central Bank has instruments designed to counter destabilising market conditions, but these are not intended to finance governments that are unwilling or unable to implement sustainable fiscal policies.

Bank of France Governor Emmanuel Moulin said on 7 October that France did not currently require ECB assistance. He argued that the solution lay in adopting a credible budget rather than expecting monetary intervention.

His position follows increasing speculation about whether the ECB could intervene if French bond yields continue rising.

Such intervention would raise difficult questions about the relationship between monetary policy and national fiscal responsibility. The ECB must consider financial stability across the entire eurozone, but it cannot remove the political obligations of individual governments.

France’s existing excessive deficit procedure also complicates its eligibility for certain forms of exceptional support.

The wider European consequences

France’s problems are developing at a particularly difficult moment for European public finances.

Governments are confronting higher defence commitments, expensive measures to protect households against energy inflation and demands for greater investment in industrial competitiveness.

Italy, another heavily indebted eurozone economy, is facing related pressures. The combination places additional importance on the credibility of the EU’s fiscal rules.

The political consequences within France are already visible. Marine Le Pen has presented a programme proposing €140 billion in spending reductions, while other parties have advanced sharply different approaches to taxation, debt and public expenditure.

Those competing programmes illustrate the difficulty of securing a parliamentary consensus capable of reassuring markets.

The approaching presidential election reduces the likelihood of a durable settlement before voters choose France’s next head of state.

Eurozone partners cannot resolve that impasse from Brussels or Frankfurt. They can insist on fiscal commitments and provide a framework for adjustment, but the political decisions remain with Paris.

France’s immediate challenge is to prevent its budget dispute from becoming a broader loss of confidence in the government’s capacity to manage its finances.

  •  

MEPs warn Irish EU budget plan is ‘short‑sighted’ and risks ‘historic failure’ as cuts of €141bn spare farm and cohesion funds

The Irish government has set the path for a showdown between MEPs and governments over the next seven year EU budget after proposing an 8 percent cut worth €141bn to the European Commission’s spending plan. 

Savings from the commission proposal have been found across all headings in the so-called ‘negotiating box’ for the 2028–2034 Multiannual Financial Framework (MFF). But farmers’ subsidies under the common agricultural policy and the bloc’s cohesion policy, which provides funding to the EU’s poorest regions, have been exempted from any cuts. 

That is a nod to a sustained lobbying effort by a group of seventeen EU countries, known as ‘Friends of Cohesion’. 

As expected, meanwhile, cuts totalling €38bn have been made from the ‘Global Europe’ heading, which covers foreign aid, while €75bn has been taken from the competitiveness fund and €10bn from the EU’s administrative costs. 

In a statement on Saturday (10 October), Ireland’s minister for Europe, Thomas Byrne, said that the €1.62 trillion spending plan was “intended to bridge the many differences between Member States. It brings us closer to resolving the critical questions our Union faces on how to balance both new priorities and core policies, whilst also reflecting the fiscal realities that all Member States face.” 

This article continues, but the full version is available only to EUobserver.com subscribers. Visit account.euobserver.com/membership

  •  

Government to deliver 2027 State Budget bill to parliament today

Portugal’s AD coalition government is set to table the draft State Budget bill for 2027 in Parliament this afternoon, two full days before the deadline. The information was provided in

The post Government to deliver 2027 State Budget bill to parliament today appeared first on Portugal Resident.

  •  

Cut the EU budget and we all lose

When certain governments discuss the EU’s next seven-year budget, their first reflex seems to be: what can we cut? That is the wrong question. The real question is not how much the EU budget costs, but how much an insufficient budget will cost us all.  

Economic benefits of EU membership are estimated to be two to six times the financial contribution of individual member states. For every euro we contribute to the EU budget, we can receive up to six euros in return.

That is the power of investing together: European investment delivers more than fragmented national spending. And it does so with a budget of just one percent of EU GNI, while national budgets can reach 50 percent.

The EU budget is not simply money transferred from national capitals to Brussels: it is an investment that creates value benefiting citizens through stronger economies, better infrastructure, food security, cutting-edge research, educational opportunities, regional development, and security.

Ultimately, all member states benefit from the added value created by the EU, making the concept of ‘net contributors’ obsolete.

Easing the pressure on national contributions is a legitimate objective, and it has a clear solution: an EU revenue reform. 

The European Parliament supports the basket approach of the European Commission on new own resources and its proposals. It also proposed three additional options capable of generating substantial revenue by 1 January 2028: a digital service levy on major platforms (€25.2bn per year), a levy on online gambling (€3.9bn per year) and a crypto-assets-based own resource (€3bn per year).

Our position is clear: large global companies that benefit most from Europe’s single market should contribute fairly to the EU budget that makes those benefits possible.

Cutting the EU budget may look like saving money. But if it means weaker competitiveness, less social investment and a less secure Europe, we save nothing and taxpayers foot the bill.

The European Union’s common budget has not grown in real terms for 40 years. On the contrary, its purchasing power has been steadily eroded due to high inflation. The current EU budget has lost around 10 percent of its purchasing power compared to when it was adopted in 2020. 

A more ambitious EU budget does not automatically mean that member states will have to contribute substantially more from their national budgets. When amounts are compared in constant prices and as a share of the size of the European economy – like with like – a more realistic picture emerges. 

In terms of spending capacity, and without counting repayment of the Covid-19 recovery fund (NextGenerationEU), the commission’s proposal for the 2028-2034 budget would be below the relative size of the current 2021-2027 MFF at the time of its adoption.

Even with parliament’s proposed increase for key EU programmes, member states’ contributions would still not substantially increase. 

Let us not forget: Europeans benefit considerably more than their countries’ headline contributions suggest. The single market is the clearest example. By removing barriers between 27 economies, it creates opportunities and delivers growth that no country could generate alone. 

By reducing the budget, the EU and its member states will have less capacity to deliver the economic and social benefits that citizens expect. We’ll have less cohesion, less competitiveness, a weaker agricultural sector, less global influence, reduced social investment and a much less secure Europe. And this also comes at a cost. A big one.

Instead of “what can we cut” we should be asking ourselves, “how can we finance a budget that delivers more for all”.  

If we genuinely want to use limited public resources efficiently, we must invest together. Economies of scale work for successful businesses, and they work for Europe.

Siegfried Mureşan (EPP, Romania) and Carla Tavares (S&D, Portugal) are the parliament’s co-rapporteurs on the EU budget, also known as the multiannual financial framework (MFF)

  •  

Russia starts pouring more into war after Putin judged Alaska talks with US would bring no “acceptable” deal to end fighting — Bloomberg

greece blocked gas ban france italy softened entry ban—now brussels tries 1600 companies helping russia's war · post russian soldiers military parade 9 2025 moscow russia kremlinru victory_day_parade_2025_at_red_square ukraine news

Russia is spending more on the war than at any point since it began. Russia's military funding is on track to hit a record this year after President Vladimir Putin added almost $60 billion to the outlays set in the budget, Bloomberg reports, citing people close to the government.

Defense spending is expected to approach about $199 billion by the end of 2026, roughly 40% above the plan Moscow announced in late 2025. That reverses the course of a year ago, when the Kremlin meant to slow military growth, narrow its deficit, and rebuild reserves drained by the war.

Alaska was the turning point

Putin ordered the shift late last year, after concluding that talks with the US in Alaska would not produce an acceptable deal to end the fighting, the report says.

By January, the Kremlin judged an agreement with Ukraine to be out of reach, and the government began accelerating advance payments to defense firms and raising other war-related spending.

"The government is finally budgeting for a prolonged war in Ukraine, but still understates its cost," Bloomberg Economics economist Ekaterina Vlasova said.

The deficit nearly doubles

Paying for the war has blown out the budget. The projected 2026 deficit has climbed to more than $81 billion, up from about $44 billion as first planned, and the government covered the extra spending through increased domestic borrowing and gold sales.

The budget plans years of war

The spending is not set to fall soon. Under the budget plans, Russia's military outlays reach about $200 billion in 2027, then ease to $194 billion in 2028 and about $191 billion in 2029, a signal that Moscow is planning for a long war.

Earlier, Euromaidan Press reported that Russia was raising 2027 defense spending by 27% to a record, even as its deficit widens and oil and gas revenues fall.

  •  

If it worked with Ukraine, why not also Iran? Green MEPs urge EU to tax oil super profits

Europe’s Green party has called on the European Commission to exercise the powers it previously used during the Ukraine war to tax the exceptional profits made by big oil and gas companies during the ongoing conflict in Iran. 

“There are models in Europe that we can use to tax these super profits,” German MEP Rasmus Andresen told a European Parliament debate in Strasbourg on Wednesday (7 October), in his call to crack down on Iran-crisis profiteering.

The Strasbourg debate came after Austria, Germany, Italy, Poland, Portugal, and Spain wrote to Ireland’s finance minister in August calling for an EU-wide framework to tax windfall profits.

Ireland holds the rotating EU presidency and can set agendas in the EU Council until the end of the year.

Several of those in the group of six EU states already put in place energy windfall taxes since this summer, ranging from 60 percent levies on excess fuel profits in Poland to 33 percent in Portugal.

Many other EU countries oppose introducing another tax at European level, which would require unanimity among all 27 member states to put in place.

But for his part, the Greens’ Andresen told MEPs in the hemicycle on Wednesday: “I don’t understand how despite the fact that there is this initiative from these six member states, that the commission is not taking action.”

Estimates from NGO Transport and Environment found that excess profits of €7.5bn were seen by eight oil companies alone in the first half of 2026 in Europe.

The figures were twice what they had made in the previous quarter. 

The EU had reacted to soaring energy prices after Russia’s full invasion of Ukraine in 2022 with a special “solidarity” tax on oil and gas firms, said groups on the Parliament’s left.

A commission assessment found that the measure raised €28bn in 2022-2023.

A senior official representing the Irish presidency, Thomas Byrne, said on Wednesday that windfall taxes “could be considered to respond to the concern related to the rising cost of living“.

But energy commissioner Dan Jørgensen poured cold water on appeals for EU-level action, saying “corporate taxation falls mainly in the realm of national competence” in legal terms.

Andresen’s fellow Green MEP, Marie Toussaint, said taxing Iran profits could be used “to pay for the energy transformation” in Europe, in the context of difficult talks on the EU’s next multi-annual European budget.

If they were not taxed, “how can they be exonerated from all responsibility in the rise of prices at the gas station?,” said the French vice-president of the Greens group.

This article continues, but the full version is available only to EUobserver.com subscribers. Visit account.euobserver.com/membership

  •  

Budget breakthrough: President welcomes PS-Government compromise

Portugal’s minority government has secured a clearer path to passing its next State Budget, after PS Socialists signalled they would allow the proposal through its first parliamentary vote — a

The post Budget breakthrough: President welcomes PS-Government compromise appeared first on Portugal Resident.

  •  

Le Pen Sets Out €140bn Spending-Cut Plan as French Debt Dominates 2027 Race

Marine Le Pen has set out plans to cut French public spending by €140 billion by 2032, reduce the deficit and impose a constitutional constraint on future borrowing, placing France’s deteriorating public finances at the centre of the campaign for the 2027 presidential election.

Marine Le Pen has presented a five-year fiscal programme under which a National Rally administration would seek €140 billion in net savings by 2032, restore France’s primary budget balance within 18 months and bring the headline deficit back below the European Union’s three per cent threshold by 2030.

The proposals, presented on Tuesday as Le Pen outlined the financial trajectory she would pursue during a presidential term, come as France faces rising borrowing costs and a public debt ratio approaching 120 per cent of GDP.

The scale of the problem was underlined on the same day by France’s Directorate-General of the Treasury. Its latest report on public debt projects the debt ratio at 119.3 per cent of GDP this year before rising to 121.7 per cent in 2027. Debt stood at 115.7 per cent at the end of 2025.

EU Today has already reported that French borrowing costs and concerns over the sustainability of the country’s finances have begun to weigh on the euro and widen the gap between French and German government bond yields.

Le Pen’s programme is therefore aimed not only at French voters but at financial markets increasingly focused on whether Paris can prevent debt from continuing to rise.

According to the proposals outlined on Tuesday, spending reductions would be concentrated heavily in the first three years of a Le Pen presidency. She would also seek to introduce what she calls a constitutional “golden rule”, requiring successive governments to reduce the budget deficit each year.

The measure would be put to a referendum and is intended to make deficit reduction binding beyond an individual government’s annual budget decisions.

Le Pen has also proposed reducing France’s public debt to around 112 per cent of GDP by 2032. That would reverse the trajectory currently expected by the French government, although the National Rally’s assumptions would depend on its ability to deliver the proposed savings and on economic growth during the next presidential term.

Among the most politically significant proposals is a plan to restrict France’s net contribution to the EU budget to €5 billion. The party argues that some European spending should instead be financed through harmonised taxes on products such as tobacco and alcohol.

Le Pen also expects substantial savings from tighter immigration controls and the introduction of the National Rally’s proposed “national preference” rules for access to parts of the welfare system. Her programme estimates that measures connected with immigration could eventually produce savings of as much as €29 billion annually.

Other elements include changes to pension policy, reductions in corporate and energy taxation, measures against VAT fraud, the abolition of more than 120 taxes and a reduction in the number of state agencies.

The programme marks an attempt by Le Pen to make fiscal policy a central part of a campaign that has until now been dominated largely by immigration, security and questions surrounding France’s political fragmentation.

The timing is significant. Prime Minister Sébastien Lecornu’s government has itself introduced a difficult fiscal consolidation programme. The 2027 budget presented by the Finance Ministry envisages €54 billion in measures to improve the public finances, including €43 billion contained directly in the state and social-security budgets.

The government expects the deficit to fall from 5.4 per cent of GDP in 2026 to five per cent next year. It forecasts growth of only 0.5 per cent this year before a recovery to one per cent in 2027.

The debt burden is becoming increasingly costly. Interest payments are expected to reach €91.2 billion in 2027, up from €79.2 billion this year, according to the Finance Ministry. By 2030, total public-sector interest costs are projected to reach 3.7 per cent of GDP.

That gives the presidential campaign an economic dimension that is difficult to separate from France’s relationship with Brussels. Paris remains subject to EU fiscal rules requiring a gradual reduction in its deficit, while any attempt to reduce the French contribution to the EU budget would require negotiations with the other member states.

Le Pen enters that debate from a strong electoral position. Recent polling examined by EU Today has placed her ahead in first-round scenarios for 2027, although the final field remains unsettled. EU Today reported in September that Le Pen was polling between 33 and 36 per cent depending on her opponents.

Her latest intervention shifts part of the campaign onto terrain traditionally associated with the centre-right: public spending, debt and the credibility of France’s finances.

With the government attempting to secure parliamentary support for its own austerity measures and French borrowing costs under closer scrutiny, the question of how the country pays for the state is now moving towards the centre of the contest to succeed Emmanuel Macron.

  •  

Von der Leyen joins MEPs in defence of EU’s €2 trillion spending plan ahead of summit

European Commission president Ursula von der Leyen has joined MEPs in urging the bloc’s governments not to gut the EU’s next seven-year budget, as talks on spending reach a critical phase. 

“I would like to caution against large cuts. It would risk cutting deep into critical priorities that we all together have agreed on,” von der Leyen told MEPs during a speech in Strasbourg on Tuesday (6 October), ahead of an EU summit on 15 October.

The commission has proposed a budget worth just under €2 trillion, equivalent to 1.26 percent of the EU’s gross national income, a small increase on the previous seven year spending plan. But the so-called ‘frugal’ group of countries, led by Germany, have demanded hefty cuts, complaining that they are contributing too much. 

“Having no new financial framework is by far the most financially advantageous solution for Germany,” chancellor Friedrich Merz said on Monday. 

But 17 EU countries from Southern and Eastern Europe signed a joint letter last week, demanding that farmers’ subsidies via the Common Agricultural Policy are maintained, as well as spending across the EU’s poorest regions, known as cohesion policy 

During a press conference on Tuesday, Siegfried Muresan, the Romanian centre-right MEP who is co-leading parliament’s negotiating team on the seven-year budget with Portuguese socialist and democrat Claudia Tavares, said that there was “still time” for the Irish presidency to avoid proposing “unjustified cuts” that “would make Europe weaker and severely undermine the institutional cooperation between parliament and council.” 

Though Muresan conceded that governments did not want to increase their national contributions, “there is a way out”, he said. 

This article continues, but the full version is available only to EUobserver.com subscribers. Visit account.euobserver.com/membership

  •  

Seventeen EU Countries Push Back Against Cuts to Farm and Cohesion Spending

Seventeen EU governments have joined forces to defend agricultural and regional funding in the bloc’s next seven-year budget, setting up a confrontation with Germany and five other countries demanding substantial reductions to the European Commission’s proposed €2 trillion spending plan.

Seventeen European Union countries have called for agriculture and cohesion funding to be protected from further cuts as negotiations over the bloc’s 2028–2034 budget enter a decisive phase.

In a letter dated 2 October to Irish Taoiseach Micheál Martin, whose government currently holds the rotating presidency of the Council of the EU, the countries said the overall financing of Cohesion Policy and the Common Agricultural Policy should be maintained in the next Multiannual Financial Framework.

The signatories are Bulgaria, Croatia, Cyprus, Czechia, Estonia, Greece, Hungary, Italy, Latvia, Lithuania, Malta, Poland, Portugal, Romania, Slovakia, Slovenia and Spain.

The initiative follows months of coordination by the so-called Friends of Cohesion. In an earlier joint position published by the Spanish government, members argued that cohesion, agriculture and fisheries remained central EU policies and called for new EU revenue sources to be “genuine, fair, simple and non-regressive”.

Italian Prime Minister Giorgia Meloni and Romanian President Nicușor Dan have been coordinating the group at leaders’ level. They are expected to convene another informal meeting alongside the European Council on 15–16 October. The two leaders previously brought the group together ahead of the June European Council as governments sought to coordinate their positions on the budget.

The intervention places the group in direct opposition to Germany, Denmark, the Netherlands, Austria, Finland and Sweden.

Those six governments have argued that the Commission’s near-€2 trillion proposal should be reduced by several hundred billion euros. In their joint statement on the 2028–2034 budget, they said national governments were already undertaking fiscal consolidation and that the EU budget could not be exempt from similar pressure. They called for reductions across all spending headings while giving greater weight to security, defence, competitiveness, migration and sovereignty.

EU Today previously reported on the growing pressure from net-contributor countries for deep reductions to the Commission proposal as negotiations moved towards the Irish presidency’s attempt to secure an agreement before the end of the year.

The Commission’s original proposal for the 2028–2034 Multiannual Financial Framework amounts to almost €2 trillion in current prices, equivalent to 1.26 per cent of the EU’s average gross national income over the seven-year period. It substantially restructures the budget, bringing agriculture, cohesion, fisheries, migration and internal security into national and regional partnership plans while allocating more money to competitiveness, research, defence and other emerging priorities.

Agriculture and regional development have consequently become two of the most sensitive parts of the negotiations.

The Council has already backed the principle of the new national and regional plans, but financial allocations remain unresolved. Its negotiating position specifically leaves the money to be settled as part of the overall MFF talks.

EU Today has followed the dispute since the Cyprus presidency produced a negotiating framework in June that proposed reducing the Commission’s plan by about €32.8bn. The disagreement has since widened as governments attempt to reconcile traditional spending on farmers and poorer regions with growing demands for defence, industrial competitiveness and security.

Revenue is another source of disagreement.

The Commission has proposed five new EU own resources, including revenue connected to the Emissions Trading System and Carbon Border Adjustment Mechanism, a contribution based on uncollected electronic waste, a tobacco excise resource and a contribution from large companies operating in the EU. The proposals are intended partly to reduce reliance on national contributions and help finance repayment of pandemic-era borrowing.

EU Today previously examined the dispute over new sources of EU revenue after leaders asked the Irish presidency to develop financing options alongside negotiations over expenditure.

The Friends of Cohesion have also called for a more gradual repayment schedule for NextGenerationEU borrowing and oppose retaining contribution rebates for wealthier member states. Under the Commission proposal, repayments of principal and interest would amount to a fixed €24bn annually between 2028 and 2034, or €168bn across the seven-year budget period.

Ireland now faces the task of narrowing the gap.

The Council’s timetable for the negotiations envisages the Irish presidency advancing the next negotiating framework ahead of the October European Council, with governments seeking a political agreement before the end of 2026. That would leave 2027 for adoption of the legislation required before the new budget takes effect on 1 January 2028.

An agreement among governments will require unanimity. The European Parliament must then give its consent, while the separate decision governing the EU’s own resources also requires unanimous approval by member states and ratification according to their national constitutional procedures.

With 17 governments now explicitly defending agriculture and cohesion spending and six major contributors demanding substantial reductions, the October summit will bring the central budget dispute directly before EU leaders.

  •  

French Public-Sector Strike Adds Pressure Ahead of 2027 Budget

French public-sector workers went on strike on Tuesday as demonstrations and school blockades spread across the country, two days before the government is due to present its 2027 budget.

Teachers, firefighters and health workers were among those taking part, with around 170 demonstrations planned nationally. High-school students also blockaded hundreds of schools, extending protests that began over teacher shortages, overcrowded classrooms and conditions in the education system.

The industrial action, accompanied by the traditional violence, places Prime Minister Sébastien Lecornu’s government under additional pressure before ministers present the draft finance and social-security budgets on Thursday, 1st October.

The French Education Ministry reported that 13.71 per cent of teachers participated in Tuesday’s strike across most of metropolitan France and Réunion. Participation reached 15.28 per cent among primary-school teachers and 12.74 per cent in secondary education.

Separate student action affected hundreds of secondary schools.

Protests were reported in Paris, Lille, Lyon, Nice and other cities. Some demonstrations involved clashes with police and damage outside schools, although much of Tuesday’s public-sector action proceeded without major disruption.

The dispute is centred partly on government spending plans.

Trade unions oppose a proposed freeze in the salary index used to calculate public-sector pay and argue that years of inflation have already reduced employees’ purchasing power. Firefighters have also demanded additional resources following the extensive wildfires that struck France during the summer.

The government is preparing its budget against a worsening fiscal background.

France’s public debt has climbed close to 120 per cent of gross domestic product, while the budget deficit remains well above the European Union’s 3 per cent ceiling.

EU Today reported earlier this month that French debt was heading towards 120 per cent of GDP, accompanied by an increase in the premium investors demand to hold French government bonds rather than German debt.

Higher interest rates are adding to the pressure. Debt-servicing costs have become one of the largest areas of central government spending, restricting the room available for tax reductions or additional expenditure.

The government has also reduced its 2026 economic growth forecast to 0.5 per cent.

Finance Minister Roland Lescure has acknowledged that France will miss its earlier deficit target, leaving the 2027 budget with the difficult task of demonstrating a credible path towards stabilising the public finances without provoking further political resistance.

The budget is due to be formally presented on Thursday. The Finance Ministry has confirmed that Lescure, Public Accounts Minister David Amiel, Labour Minister Jean-Pierre Farandou and Health Minister Stéphanie Rist will present the finance and social-security bills following the Council of Ministers.

The argument is taking place while EU fiscal surveillance is itself entering a more demanding phase.

Under the revised Stability and Growth Pact, member states are expected to follow agreed medium-term expenditure paths designed to bring deficits and debt onto sustainable trajectories.

EU Today recently examined how the EU’s fiscal rules face an enforcement test in October, when finance ministers and the European Commission return to national budget compliance. France is one of the countries where implementation will receive particularly close attention because of its debt level, persistent deficit and political difficulty in securing parliamentary agreement for spending reductions.

The domestic parliamentary arithmetic remains difficult. Lecornu’s government does not control an outright majority in the National Assembly, meaning the budget could become the subject of amendments, confidence votes or further negotiations with opposition parties.

The government has previously relied on Article 49.3 of the constitution to pass financial legislation without a conventional parliamentary vote, although use of the mechanism exposes a government to motions of no confidence.

Tuesday’s strikes add another layer to those negotiations. Trade unions have indicated that further action is possible if the budget contains measures they regard as unacceptable. The CGT has demanded changes to planned spending reductions and public-sector pay policy.

The precise scale of the government’s fiscal measures will become clearer on Thursday. For France, the budget will have to address three pressures simultaneously: deteriorating public finances, the EU’s fiscal framework and domestic opposition to further restraint.

  •  

France Wants Google Fines Used to Reduce EU Budget Contributions

France has called for money collected through European Union fines against Google to be used to reduce national contributions to the EU budget as governments negotiate the bloc’s next seven-year financial framework.

Europe Minister Benjamin Haddad said proceeds from penalties imposed on the US technology company should be treated as EU revenue and used to lower the sums governments must pay into the common budget.

The proposal comes as negotiations intensify over the 2028–34 Multiannual Financial Framework, for which the European Commission has proposed expenditure of almost €2 trillion.

Haddad referred to about €4.6 billion in revenue associated with Google penalties and interest.

The proposal is less radical in budgetary terms than it first appears because fines that become final already enter the EU budget as “other revenue”.

The Commission’s explanation of EU budget revenue states that gross national income-based contributions act as the balancing element of the budget after customs duties, VAT-based resources and other revenues — including fines on companies — are taken into account.

Higher income from definitive competition fines can therefore reduce the amount required from national governments.

France is pressing for that mechanism to be applied clearly to the Google proceeds at a time when governments are seeking ways to limit increases in their national payments.

Google has accumulated substantial EU penalties through both competition law and the Digital Markets Act.

In July, the European Commission fined Google €890 million under the Digital Markets Act in two separate decisions.

A €460 million penalty concerned the Commission’s finding that Google gave preferential treatment to its own services in search results. A further €430 million fine concerned restrictions affecting developers’ ability to direct users towards alternative purchasing channels outside Google Play.

Google has contested elements of the EU enforcement regime and has continued legal proceedings over Commission decisions.

EU Today has followed the dispute closely. In September, Google began changing European search results following the DMA enforcement action, while earlier Commission measures generated a wider dispute with Washington over European regulation of US technology groups.

The French budget proposal shifts the issue from regulation towards public finance.

EU governments are currently divided over the Commission’s proposed 2028–34 budget, which averages about 1.26 per cent of EU gross national income.

Germany, Denmark, Finland, the Netherlands and Austria are among governments seeking substantial reductions in the proposed spending level.

EU Today reported this month that five large net contributors were demanding cuts of several hundred billion euros from the Commission proposal.

France also faces a sharp increase in its projected contribution.

Against that background, governments are looking at both expenditure reductions and new revenue streams that could limit demands on national treasuries.

The wider negotiations cover possible EU “own resources” — revenue that flows directly or indirectly to the European budget rather than being provided through conventional national contributions.

Existing resources include customs duties, a VAT-based contribution, a plastics contribution and national payments calculated according to gross national income.

The Commission has also proposed additional sources linked to carbon pricing and other EU policies.

EU Today has previously examined how EU leaders are searching for new revenue sources for the €2 trillion budget while attempting to finance defence, competitiveness, migration, agriculture, cohesion programmes and support for Ukraine.

Company fines differ from permanent own resources because their size is unpredictable and depends on enforcement decisions and subsequent legal proceedings.

A large fine can provide a one-off boost to EU revenue, but it cannot readily finance recurring expenditure across a seven-year financial framework.

Definitive fines have nevertheless affected member-state contributions before. Commission budget amendments have explicitly incorporated competition penalties as additional revenue, reducing the amount that must be raised elsewhere.

France is now seeking to ensure that the Google proceeds are reflected directly in the sums demanded from national budgets.

The proposal comes before another round of negotiations over the Multiannual Financial Framework, where the size of the budget remains unresolved.

With agreement requiring unanimity among all 27 governments, even relatively small sources of additional revenue are becoming part of the bargaining over who ultimately pays for the EU’s expanding spending commitments.

  •  
❌