❌

Reading view

Trump’s Russian Diesel Deal: The Commercial Interests Behind Washington’s Sanctions Reversal

Donald Trump has presented his agreement with Vladimir Putin as a means of reducing American fuel prices. Yet the Treasury authorisation extends far beyond the announced diesel shipments, opening opportunities for international trade in Russian petroleum products as American investors negotiate the acquisition of Lukoil’s overseas assets.

President Donald Trump’s decision to reopen trade in Russian diesel has implications extending well beyond American fuel prices. The agreement, announced ahead of November’s congressional elections, coincides with negotiations over Russian energy assets and mounting American pressure on Ukraine to suspend attacks against Moscow’s oil infrastructure.

The US Treasury’s General Licence 135, issued on 9 October, authorises transactions involving Russian-origin diesel until 7 April 2027. Unlike Trump’s public announcement, which referred to specific quantities destined for the American market, the licence establishes no corresponding volume ceiling or restriction confining authorised trade to the United States.

Its provisions permit American businesses to participate in eligible international transactions involving Russian diesel, including associated financial and commercial services. Existing sanctions remain formally in force, but an important category of Russian petroleum trade has been reopened.

The arrangement potentially benefits not only Russian producers but also American commodity traders, financial institutions and intermediaries capable of purchasing Russian fuel and distributing it internationally.

Sanctions relief without removing sanctions

The legal mechanism offers Washington considerable flexibility. Rather than formally abandoning restrictions imposed over Russia’s invasion of Ukraine, the administration can authorise selected transactions while maintaining the broader sanctions framework.

Congress’s Lindsey O. Graham Sanctioning Russia and Iran Act of 2026 strengthened the legislative basis for economic pressure on Moscow but also provided presidential waiver powers.

General Licence 135 was issued under existing Treasury sanctions authorities, rather than necessarily through those waiver provisions. Nevertheless, the combined framework leaves the administration substantial discretion over the practical application of economic restrictions.

Washington can consequently maintain its declared sanctions policy while selectively restoring commercial relations with Russia. European governments, which have maintained extensive restrictions on Russian energy, have little influence over such unilateral American exemptions.

The Lukoil connection

The timing becomes more revealing when considered alongside negotiations over Lukoil’s international assets.

American investors have been exploring the acquisition of the Russian company’s overseas operations, including oilfields, refineries, storage facilities and retail distribution networks. The portfolio has been valued at approximately $20–22 billion.

Among the prospective investors is billionaire Todd Boehly, while discussions concerning Russian-American economic cooperation have involved Trump’s representatives Steve Witkoff and Jared Kushner.

An American-controlled acquisition of Lukoil’s international network could complement the commercial opportunities created by the diesel authorisation.

Russian petroleum products could potentially be purchased and marketed through American-controlled businesses, allowing Russian suppliers to retain export revenues while intermediaries earn profits from financing, distribution and resale.

No evidence establishes that General Licence 135 was specifically designed for the prospective Lukoil purchasers, or that Trump personally holds an interest in the proposed transactions. Nevertheless, the parallel negotiations suggest the possibility of an emerging commercial arrangement under which American intermediaries assume a greater role in Russian energy exports.

Ukraine and the conflict of interests

The consequences for Ukraine could be considerable.

Kyiv has expanded attacks against Russian refineries, fuel depots and petroleum infrastructure, seeking to reduce Moscow’s export earnings and disrupt supplies supporting its armed forces.

Trump has repeatedly criticised these strikes, linking them to higher international fuel prices. His administration now has an additional commercial reason to seek their suspension.

On 11 October, Trump announced an energy ceasefire between Russia and Ukraine, although President Volodymyr Zelenskyy indicated that Kyiv had not agreed to such an arrangement.

Ukraine has maintained that any suspension of attacks against Russian energy facilities must be matched by an end to Moscow’s strikes on Ukrainian power infrastructure.

An agreement protecting Russian refineries without equivalent Russian concessions would preserve an important source of Kremlin revenue while depriving Kyiv of military and economic leverage.

A separate accommodation with Moscow?

The immediate political advantage for Trump is apparent. Rising diesel prices have become a concern ahead of the 3 November midterm elections, particularly among farmers and transport businesses. Additional Russian supplies offer the administration an opportunity to demonstrate action on domestic fuel costs.

Yet the six-month Treasury authorisation extends considerably beyond the election, suggesting commercial objectives that cannot be explained exclusively by short-term electoral considerations.

The emerging pattern is one of bilateral economic engagement with Moscow proceeding independently of a settlement in Ukraine. Russian energy trade is being selectively reopened, American investors are pursuing Russian-owned assets, and Washington is seeking restrictions on Ukrainian operations against the infrastructure underpinning those commercial interests.

For European governments, this threatens the cohesion of the sanctions regime. Brussels may continue restricting Russian energy revenues while Washington authorises transactions that restore access to international markets.

The larger prospect is a system in which Russia retains export earnings, American intermediaries acquire profitable commercial positions, and sanctions become instruments of bilateral negotiation rather than coordinated Western pressure.

Trump’s diesel agreement may therefore represent the opening stage of a wider economic accommodation with Putin, negotiated while Russia continues its war against Ukraine and without any corresponding Russian commitment to withdraw from occupied territory.

  •  

Ukraine Strikes at Heart of Russia’s Oil Network as Samara Hub Comes Under Repeated Attack

Ukrainian forces have attacked one of Russia’s most important oil transport and blending facilities for the third time this month. The Samara hub handles crude from several major producing regions and plays a central role in preparing Russia’s Urals export blend, making it a target of considerably greater strategic significance than an ordinary oil depot.

Ukraine has intensified its campaign against Russia’s oil industry with another drone strike on the Samara linear production and dispatch station, a major facility in the pipeline network operated by state-controlled Transneft. The latest attack, during the night of 9–10 October, followed earlier strikes on 2 and 7 October, which Ukrainian military authorities say caused extensive damage to storage tanks and associated infrastructure.

The significance of Samara extends well beyond the destruction of stored oil. Situated near the settlement of Prosvet in Russia’s Samara region, the installation is a junction where crude oil arriving from Western Siberia, Tatarstan and the Volga-Urals producing regions is received, stored, blended and redistributed. Its role makes it an important link between Russian oil production, domestic refining and export markets.

According to the Ukrainian General Staff’s operational report, Samara is responsible for blending crude with different sulphur contents to produce Urals, Russia’s principal export grade. Ukraine’s military says the facility also contributes to supplying the Russian armed forces.

Why Samara matters to Russia’s oil exports

Unlike an oil refinery, where crude is processed into petrol, diesel and other fuels, the Samara installation performs a function earlier in the supply chain. It is one of the points where different grades of Russian crude are brought together to produce a commercially standardised export mixture.

Western Siberian crude generally has different characteristics from oil extracted in the Volga-Urals basin, including variations in sulphur content and density. Blending these streams is essential to maintaining the specifications of Urals crude, which is supplied to refineries and sold on international markets.

Samara’s importance also reflects the sheer scale of the infrastructure concentrated at the site. Ukrainian Special Operations Forces describe a facility where four major oil pipelines converge, supported by 71 storage tanks with a combined capacity exceeding 1.6 million cubic metres.

The site’s central role is not simply a Ukrainian assessment. Transneft-Privoĺga’s management previously described the Samara installation as having Europe’s largest oil storage tank farm and identified its blending station and associated pumping installations as part of a major modernisation programme.

Approximately 140 million tonnes of oil passes through the Samara complex annually. That figure would make the installation an important concentration point within the wider Russian pipeline system.

The consequences of sustained disruption could therefore extend beyond the immediate loss of storage capacity. Damage to blending operations, connecting pipelines or loading equipment could interfere with the movement of crude towards refineries and export routes. The precise effect would depend on the functioning of alternative facilities, available spare capacity and the speed of repairs.

Three attacks in nine days

The first strike, on 2 October, reportedly damaged 11 storage tanks with capacities of 20,000 cubic metres each, three larger tanks of 50,000 cubic metres, sections of pipeline and an automated loading station. The Security Service of Ukraine confirmed that its personnel had participated in the operation alongside other branches of the armed forces.

A further strike on 7 October destroyed four large storage tanks and caused a substantial fire, according to Ukraine’s General Staff. Ukrainian Special Operations Forces subsequently confirmed another attack on 10 October, although the damage from that operation remains under assessment. The reported destruction and damage have not been independently verified in full.

The repeated attacks indicate an effort to produce cumulative disruption rather than rely on a single operation to disable an extensive industrial complex.

This approach is consistent with Ukraine’s broader campaign against Russia’s refining industry. As EU Today examined in August, repeated strikes on processing facilities can create difficulties that extend beyond the immediate damage, particularly when specialist equipment requires lengthy repairs.

From refinery attacks to the wider oil network

The campaign against Samara represents a significant extension of that strategy. Refineries remain important targets because they produce the fuels required by Russia’s armed forces and domestic economy. Transport and blending facilities, however, determine whether crude reaches those refineries in the required quantities and specifications.

Continuous attacks are essential because much of the damage inflicted by drones is repairable. Individual installations may return to service within days or weeks, meaning the cumulative effect depends heavily on whether further disruption occurs before repairs and production have fully resumed.

Russia’s refining industry remains heavily dependent on specialist equipment and technologies historically supplied by Western manufacturers. Sanctions have restricted access to replacement components, while domestically manufactured equipment and Chinese alternatives are not always technically compatible with existing installations. These constraints complicate repairs, prolong shutdowns and limit Russia’s ability to restore damaged refining capacity.

Samara presents a somewhat different vulnerability. Its importance rests on the concentration of pipeline connections, storage and blending operations at one location. A sustained interruption could affect several parts of the oil supply chain simultaneously, although the available evidence does not yet establish that the wider network has suffered a prolonged shutdown.

Ukraine has already demonstrated its willingness to strike other logistical installations. A recent attack on the Volodarskaya petroleum-products station near Moscow targeted another important part of Russia’s fuel distribution system.

Implications for Russia’s war economy

Oil remains central to Russia’s export earnings and federal finances, while the availability of refined petroleum products influences military logistics, transport and industrial activity.

The immediate economic significance of the Samara attacks will depend on how much operational capacity has been lost, whether crude can be redirected through alternative infrastructure and how quickly Transneft can restore the damaged facilities.

There is an important distinction between destroying storage tanks and preventing oil from moving through a network. The former reduces available capacity; the latter can impose broader restrictions on production, refining and exports. Establishing the extent to which the latest strikes have achieved either effect will require further operational evidence.

Nevertheless, the decision to return repeatedly to Samara illustrates a development in Ukraine’s campaign against Russia’s energy sector. Rather than concentrating exclusively on the refineries that convert crude into fuel, Kyiv is also attacking infrastructure that connects oil production to its commercial and military end users.

For Moscow, the vulnerability of Samara is particularly consequential because the installation occupies a central position in the movement and preparation of Urals crude. Any sustained loss of its blending, storage or distribution functions would introduce additional pressure into an oil system already facing repeated attacks on its refineries and export infrastructure.

The latest operation therefore raises a question extending beyond the damage to one industrial site: whether Russia can maintain reliable oil flows when several interconnected stages of its energy supply chain are subjected to recurring disruption.

  •  

The Diesel Deal between Trump and Putin: Hope dies last

Trump’s declaration presents a very interesting media narrative and a potential end to ‘Project Ukraine’ that is worth taking a deeper dive into.

Join us on Telegram, X, and VK.

Contact us: info@strategic-culture.su

No one expected that Donald Trump, after a congratulatory birthday phone call to his Russian counterpart, would declare that Russian diesel fuel would prove to be the solution to America’s current fuel shortages. If the Trump presidency has yielded anything it is a lot of interesting headlines that seem to come out of nowhere, that can sadly, quite often, fade right back into the mist from whence they came. Sometimes Trump’s words can fill us with hope like this ‘Diesel Deal’, and others like his recent UN speech, where he threatened to potentially kill all Iranians, fill us with dread. This declaration by our enigmatic leader presents a very interesting media narrative and a potential end to ‘Project Ukraine’ that is worth taking a deeper dive into.

Trump has blamed Zelensky for the global energy shortages, especially those concerning diesel fuel. At the time, everyone thought this was just a cheap Twitter-style deflection from the failed war against Iran, which certainly caused a lot of fuel transport disruption. That is to say, the White House was projecting this crisis, that it allowed to happen, or actively caused, to be thrown onto the scapegoat Zelensky. However, this form of deflection or projection is no longer just words in a pre-election narrative, but has become action. Sanctions on Russian diesel have been lifted and the first shipment is already on its way as I write these words. Something tangible has occurred.

Zelensky was actually warned some six times to stop attacking Russian oil infrastructure. Blow up children in the Donbass and beyond ‘sure’, but attacking what the West wants from Russia more than anything is ‘totally unacceptable’. Zelensky, who as stated above was warned half-a-dozen times to back of strikes on oil/gas, upon hearing of Trump’s decision to purchase Russian diesel fuel did the following:

1) He quickly attacked Russian oil infrastructure again seemingly to spite the U.S. President

2) He immediately cut off peace talks in Miami with the Trump’s aides, the Kushner-Witkoff duo, which is yet another spitting in the face of Donald Trump.

The wildest thing of all is that the ‘narcissist’ Trump has already publically thanked President Putin twice for this deal. Appearing at a rally, Americans standing behind Trump wildly cheered in favor of the announcement of peace with Russia plus extra fuel for America. Russophobia is a hobby of the globalist bourgeoisie and Epstein Island, not American truckers and farmers.

It’s a great narrative, let’s hope it lasts

Trump has now put 100% of the blame for global energy/fuel problems directly onto Zelensky, and called him out personally for keeping the war going over the last two years. Thus, the narrative is forming into something like: If the war in Ukraine is the cause of the fuel shortages, and Zelensky is the cause of the war continuing, that means the U.S. can make a deal with Russia even if ‘they started it’, with the corollary that Zelensky logically needs to go as he is the source of the problem. But going even deeper into the narrative we can see the most interesting thing of all or as they like to say online ‘the quiet part’: Trump has essentially declared that Russian energy output is of vital strategic interest to the United States.

It is these kind of words that take the black pill out of my mouth and directly inject ‘hopium’ into my bloodstream. The idea of the American President declaring that NOT being at war with Russia is of vital strategic interest to the USA is something I have been dreaming of my entire adult life. This is exactly the logic that we need to finally and ultimately end the Cold War + Project for a New American Century mentality in politics and finally allow the USA to rebuild and invest into itself. This very well could be America’s mulitpolar awakening by using a logic trap similar to the other ones that have been used to do the exact opposite and keep the USA locked in eternal foreign wars of luxury for ‘national security’. This new logic trap could look something like this: “So you want war with Russia? That must mean you want to harm America, you dirty traitor! You’ll take the fuel from farmer Joe and our kids will starve, you monster! Russia being left alone to produce fuel is a national security interest of America, are you against our country’s national security? Do you want to weaken manly America for those gay Europeans?”.

But as we slam that hopium injection into our veins we have to remember that Donald Trump has said a lot of things, changed his mind many times, or was forced to change it, and perhaps isn’t quite the unilateral decider that he makes himself out to be on TV.

It takes two to tango, but one orange man to keep his word.

The transcripts from this now famous birthday phone chat look very different on the American and Russian sides, which is par for the course. Trump’s team tends to write discussed things as proven facts whereas the Russians are more noncommittal in their language. But the diesel sanctions are gone for now and the boats are moving, so this looks to be real… at least until the mid-term votes are cast.

The American side has since threatened to cut Zelensky off from intelligence sharing, which could be an instant deathblow to their military efforts as many experts believe that only U.S. intel has allowed them to survive this long. Without such targeting data they will be sent back to 20th century warfare instantly, and they would no longer be able to strike deep into Russia. RT wrote the following on this issue:

A Ukrainian official told Axios that Witkoff and Kushner threatened to cut off US intelligence sharing with Kiev if it continued to ignore Trump’s requests to halt strikes on Russian oil refineries, but the US official denied that any such threat had been made.

But here is where we have to hold our breath, for despite how nice this new narrative sounds, and how it is the perfect exit for the USA from its participation in Project Ukraine we should not forget the words of President Putin from some time ago when he talked about the true power of any U.S. President:

“So a person is elected — he comes with ideas… Then people with briefcases come visit him, well-dressed, in dark suits — kind of like mine.”

So the real question might be, will the Zionist Lobby, Epstein Elite, Three-Letter Organizations, Influential Billionaires, and all the other spooks on Capitol Hill actually let President Trump actually end this war? Will the POTUS be allowed to do this?

We should recall that after Zelensky acted disgracefully in the White House at the start of Trump’s second term everyone thought this conflict would be over. Trump the famous narcissist seemed visibly angry and offended on camera during their verbal spat. But the war went on. There was the Anchorage Summit, which had tons of hype and everyone thought then that the U.S. would pull support from Kiev. But it did not. Trump’s enemies including the Biden Clan are linked to massive corruption in Ukraine which has all been exposed. This would have been a great off ramp from the conflict, but Trump did not or could not take it. And in general, Trump’s rhetoric towards Zelensky and other European politicians has been overtly harsh and disrespectful. The man accused of being a ‘blowhard’ somehow always speaks quite politely behind the backs and to the faces of Putin and Xi.

Thus, although I want peace and mutually-respectful cooperation between the USA and Russia perhaps this deal will only last till the midterm elections, when all of a sudden Zelensky will go back to being “a bastard, but he’s our bastard”, and the conflict will go marching on. Perhaps this is our October Surprise from the Republican side of the aisle? And in December we can all be ‘surprised again’ when the war resumes full-force and thousands more Slavs die on the battlefield?

Now, Donald Trump with gritted teeth is slinging forth the idea that he thinks “it’s time for Ukraine to get a new President”. But after the votes are counted in America he may just go back to passively hating and tolerating Zelensky till the end of his term or till an Oreshnik finds the mark one day. We also cannot forget that the West has been lobbying for a major ceasefire from the Russians for a long time. Presumably this would be used to regroup, rest, rearm and then just go right back to fighting till the last Ukrainian. Now Trump wants elections in Kiev, which will probably demand a ceasefire to enact. But will he be pushing for a three-day ceasefire, or try to trick the Russians into agreeing to a month-long freeze or more?

One ‘good’ sign on this issue from a Russian standpoint is that there are now already calls for Zelensky to resign over this issue on Twitter/X coming from all sides even pro-Ukrainian ones:

“’Zelensky must resign’ – Ukrainian media. That was quick. Zelensky ignored Trump’s warnings not to attack Russian oil refineries SIX times. This morning, Zelensky has bombed another Russian oil refinery. Ukrainians are calling for Zelensky‘s resignation.

Former Ukrainian MP and Metinvest co-owner Vadym Novynskyi has called on Zelensky to resign and hand over all power to Ukraine’s Verkhovna Rada following the Trump-Putin agreements.”

We have to remember that Ukraine in 2026 is already a police state where any dissent means you could get thrown into a bus and taken to the front to die or vanish into a prison as a Russian ‘spy’. Thus, when important people gang up against Zelensky openly it is much more of a potent statement than Hollywood actors safely making Tik-Toks against Trump from their luxurious bedrooms.

The rest of the world won’t sit around and do nothing.

Some moronic ‘Putin sold out the BRICS’ counter-narrative is sure to arise from Kiev’s bot accounts soon. Obviously someone is going to say that the Kremlin threw their Iranian brothers to the Zio-lobby machine! But in actuality, it looks like the Iranians are going to just ship their oil through Russia and sell it as ‘Russian’ and everyone will be happy. The Caspian Sea will be even more busy in the near future. If sanctioned accomplished anything they really increased trade between Russia and Iran.

No one in Moscow is planning on selling out Tehran; they want America to join the Multipolar World while still saving face and reduce the global threat level of nuclear war which is vastly too high at present. Iran and China were surely consulted on this issue before any Diesel Deal was finalized.

The real danger of Trump calling for the removal of Zelensky comes from Europe, where certain factions, politicians and their financiers may take radical action in response. And Trump’s reaction to this response could be even more radical now. Would it be possible that NATO might greenlight the Baltics to just open up another front to ‘see what happens’? Will France finally go through on its threat and just deploy troops openly en masse to save the Napoleon in Green from political or potentially physical death? So far the EU has only threatened even more sanctions. If the previous 20+ packages of sanctions failed, I wonder what is left to actually sanction. Ursula is promising the biggest and most expansive sanctions packet for Monday, October 12th, but I doubt it will change anything. The only thing that would change the situation is if the EU did something really aggressive, drastic and stupid militarily.

What about the rest of the sanctions?

The Russian media has done a disservice to the public by writing that “Trump will lift sanctions” over-and-over again when the only sanctions being lifted are on diesel exports for half a year. All of the rest of the sanctions are still there. You still cannot fly directly from Moscow to New York, and money transfers via SWIFT are still mostly blocked. We have to remember that at least in theory sanctions are a form of punishment for crimes committed against, in this case, international law and the United States. So how can relations between the USA and Russian Federation truly be normalized when one still accuses the other of crimes it believes it did not even commit?

After Project Ukraine ends things could change rapidly, but there can be no true friendship until Washington trusts Aeroflot enough to let them land on U.S. territory. We cannot be both under a sanctions war and normalized at the same time. But this new Trump narrative, if he can stick with it to its logical conclusion, is the perfect off-ramp for America and the way we can finally end this war and go back to some sense of normalcy with the apocalypse pushed far off into the future beyond all of our lifespans.

  •  

Australia keeps Russian fuel out even as US opens its market: “We do not want Vladimir Putin to benefit from this war in Middle East”

The image shows the Sydney Opera House. Credit: UkrInform

Australia has no need to buy fuel from Russia, despite US President Donald Trump’s move to bring Russian diesel back to world markets. Climate Change and Energy Minister Chris Bowen says that imports from Russia will remain banned to ensure the country does not benefit from its invasion of Ukraine, Bloomberg reports.

Trump has agreed with Russia's President Vladimir Putin to release Russian diesel onto global markets, a move Ukraine says funds a war that has killed more than 80 Ukrainian civilians in two days.

“We don’t need or want Russian fuel in Australia. We do not want Vladimir Putin to benefit from this war in the Middle East. What the United States does is a matter for them, but we won’t be changing our approach,” Bowen said.

The deal Australia is turning down

Trump announced on 9 October a series of cargoes beginning this month totaling about 13.5 million barrels of Russian diesel. The release upends years of sanctions, as the White House looks for ways to tame soaring fuel prices before the US midterm elections.

Bowen draws a clear line between that approach and Australia’s. What the US does is its own affair, he stresses, but Canberra will maintain its arrangements with trading partners to keep Russian fuel out of the market.

Enough fuel to hold the line

Australia can hold out without Russian supply, Bowen argues. The country has 43 days’ worth of petrol, two days more than a week earlier, and 31 days’ worth of diesel, one day less, he notes.

He adds that Australia stays in close contact with domestic refiners to keep them running at full capacity. The stance lets Canberra wait out high prices rather than buy fuel that would send money to Moscow.

Australia’s fuel costs have stayed high since the war between the US and Iran disrupted shipping through the Strait of Hormuz, the route that normally carries about a fifth of the world’s oil and gas.

  •  

Giant Wind Turbines Risk Leaving Britain Blind to Russian Jets, Says MoD

A giant wind farm risks blinding radar used to track Russian jets and missiles, the Ministry of Defence has warned as it opposes Net Zero plans to build 23 turbines twice the height of Big Ben in Yorkshire.

The post Giant Wind Turbines Risk Leaving Britain Blind to Russian Jets, Says MoD appeared first on The Daily Sceptic.

  •  

Europe Faces Prolonged Diesel Price Pressure Despite Fall in Oil Prices

Brent crude retreated on Friday after President Donald Trump signalled a pause in further attacks on Iran, but European governments remain concerned about diesel supplies, refining capacity and the continuing disruption of shipping through the Strait of Hormuz.

European fuel markets remained under pressure on Friday, 9 October, despite a decline in international oil prices following comments by President Donald Trump suggesting that Washington would refrain from further military strikes against Iran before the November midterm elections.

Brent crude fell by $1.37 to $102.91 a barrel, while US West Texas Intermediate declined by $1.09 to $90.40. The retreat reflected expectations of renewed diplomatic negotiations with Tehran, although oil prices remained considerably higher than before the disruption of shipping through the Strait of Hormuz.

According to the latest oil-market developments, Iran is examining an American proposal that could allow the strategic waterway to reopen within a week. There is, however, no confirmed agreement on restoring maritime traffic.

For the European Union, the immediate concern extends beyond crude oil prices. A prolonged shortage of refined petroleum products, particularly diesel and aviation fuel, is threatening to increase costs across transport, agriculture, manufacturing and logistics.

Brussels Coordinates Emergency Measures

The European Commission has already established a closer system of coordination with member states and the International Energy Agency to address the pressure on fuel markets.

At an Energy Union Task Force meeting on 2 October, officials confirmed that European diesel supplies remained stable, although prices continued to reflect severe constraints in global markets.

The Commission’s assessment distinguished between the physical availability of fuel and the cost of obtaining it. European refineries have maintained high production levels, while importers have sought alternative suppliers to replace disrupted shipments from the Middle East.

A further assessment of European oil supplies published on 29 September found that refineries were operating close to maximum capacity and that stocks in the Amsterdam-Rotterdam-Antwerp trading hub remained below their five-year average.

Although emergency reserves remained available, officials warned that continuing disruption could place additional pressure on the market during autumn and winter.

The next scheduled meeting of the EU Oil Coordination Group is 15 October, although the Commission has indicated that it could convene an earlier meeting if conditions deteriorate.

G7 Plans Major Release of Emergency Stocks

The international response has moved beyond the coordination of existing reserves.

On 2 October, G7 leaders agreed to implement a coordinated release of 100 million barrels through the International Energy Agency framework over four months.

The agreement includes an accelerated release of diesel during the first 20 days, reflecting the difficulties facing markets for refined fuel.

The G7 also called for improved coordination of refinery maintenance schedules and higher utilisation rates where possible, to prevent temporary shutdowns from aggravating shortages.

These measures follow an earlier international commitment, announced in March, to make approximately 400 million barrels of oil available to the market.

Questions remain over how the October measures will be accounted for alongside the March commitments. During a Commission briefing on 7 October, officials said that the International Energy Agency would oversee the process and that Brussels would seek a coordinated European position.

The Commission did not provide figures showing how much oil individual EU countries had released.

European Transport and Industry Face Higher Costs

Diesel has become particularly important to the European response because it remains central to commercial road transport, agricultural machinery and parts of the industrial economy.

Even when crude oil prices fall, the price of diesel may remain elevated if refining capacity is constrained or supplies of finished products are insufficient.

European refiners cannot automatically compensate for shortages elsewhere. Their capacity depends on crude oil availability, technical configurations, maintenance schedules and the profitability of different refined products.

The situation also complicates efforts to contain inflation. Higher freight charges eventually affect the cost of food, construction materials and other goods transported across the European single market.

Member states are therefore considering how to protect vulnerable consumers without introducing measures that would distort fuel distribution or encourage additional consumption.

The Commission has not declared a general shortage of diesel within the EU, and the available evidence does not support suggestions that European fuel supplies are close to exhaustion.

Nevertheless, the current pressure demonstrates the limits of relying on emergency reserves when disruption affects both international shipping and the refining system.

Strait of Hormuz Remains Central

The prospect of diplomatic progress between Washington and Tehran provided some relief to markets on Friday.

However, the physical restoration of shipping through the Strait of Hormuz will depend on security conditions, commercial insurance arrangements and the willingness of shipping companies to resume normal operations.

Oil prices may respond immediately to political statements, but restoring established supply routes and rebuilding commercial confidence can take considerably longer.

For European governments, the forthcoming decisions will concern the management of emergency stocks, refinery production and the costs imposed on consumers and businesses.

Even if negotiations between the United States and Iran produce a temporary reduction in hostilities, the European diesel market will remain exposed until the disruption to international energy trade is substantially reduced.

  •  

Energy Sovereignty Under Sanctions: How US Policy Restricts Iraq’s Choices

How Iraq’s energy sovereignty can be measured and achieved? How do the geography and sanctions matter? What is the U.S.’ impact in this area? And who determines Iraq’s energy choices? Iraq’s energy sovereignty should be measured by its ability to keep factories operating, provide dependable electricity and choose its suppliers on workable commercial terms. Yet, […]
  •  

If it worked with Ukraine, why not also Iran? Green MEPs urge EU to tax oil super profits

Europe’s Green party has called on the European Commission to exercise the powers it previously used during the Ukraine war to tax the exceptional profits made by big oil and gas companies during the ongoing conflict in Iran. 

“There are models in Europe that we can use to tax these super profits,” German MEP Rasmus Andresen told a European Parliament debate in Strasbourg on Wednesday (7 October), in his call to crack down on Iran-crisis profiteering.

The Strasbourg debate came after Austria, Germany, Italy, Poland, Portugal, and Spain wrote to Ireland’s finance minister in August calling for an EU-wide framework to tax windfall profits.

Ireland holds the rotating EU presidency and can set agendas in the EU Council until the end of the year.

Several of those in the group of six EU states already put in place energy windfall taxes since this summer, ranging from 60 percent levies on excess fuel profits in Poland to 33 percent in Portugal.

Many other EU countries oppose introducing another tax at European level, which would require unanimity among all 27 member states to put in place.

But for his part, the Greens’ Andresen told MEPs in the hemicycle on Wednesday: “I don’t understand how despite the fact that there is this initiative from these six member states, that the commission is not taking action.”

Estimates from NGO Transport and Environment found that excess profits of €7.5bn were seen by eight oil companies alone in the first half of 2026 in Europe.

The figures were twice what they had made in the previous quarter. 

The EU had reacted to soaring energy prices after Russia’s full invasion of Ukraine in 2022 with a special “solidarity” tax on oil and gas firms, said groups on the Parliament’s left.

A commission assessment found that the measure raised €28bn in 2022-2023.

A senior official representing the Irish presidency, Thomas Byrne, said on Wednesday that windfall taxes “could be considered to respond to the concern related to the rising cost of living“.

But energy commissioner Dan Jørgensen poured cold water on appeals for EU-level action, saying “corporate taxation falls mainly in the realm of national competence” in legal terms.

Andresen’s fellow Green MEP, Marie Toussaint, said taxing Iran profits could be used “to pay for the energy transformation” in Europe, in the context of difficult talks on the EU’s next multi-annual European budget.

If they were not taxed, “how can they be exonerated from all responsibility in the rise of prices at the gas station?,” said the French vice-president of the Greens group.

This article continues, but the full version is available only to EUobserver.com subscribers. Visit account.euobserver.com/membership

  •  

L’Europe revient au charbon alors que les prix du gaz explosent

La crise énergétique européenne n’est pas terminée.

La crise énergétique européenne n’est pas terminée. Les prix du gaz restent obstinément élevés sur tout le continent alors que les Européens affrontent un long hiver.

En réponse à une crise énergétique découlant de la dépendance continue de l’Europe aux importations de gaz naturel liquéfié, sur fond de volatilité géopolitique mondiale persistante, les dirigeants européens poussent à diversifier le mix énergétique du bloc. Si cela signifie que l’Europe développe rapidement ses capacités en énergies renouvelables, cela marque aussi un retour significatif au combustible fossile le plus polluant du monde – le charbon.

Plus tôt cette année, lorsque les États-Unis et Israël ont lancé une offensive en Iran, provoquant ainsi la perturbation d’un cinquième des échanges mondiaux de pétrole et de gaz, l’Europe s’est réveillée pour réaliser qu’elle s’était laissée aller, en somnambule, à une nouvelle crise énergétique – sa troisième en seulement quatre ans. « Nous avions juré d’apprendre. Nous avions promis que les choses changeraient, mais nous voilà », a récemment déclaré un « diplomate européen très frustré », cité anonymement par la BBC.

« Au lieu de se concentrer sur des plans à long terme indispensables – sur la manière de rendre l’Europe plus compétitive dans ce monde de plus en plus instable, les premiers ministres et présidents [européens] sont maintenant pris de panique face aux prix [de l’énergie], inquiets des électeurs en colère et à la recherche de solutions à court terme », poursuit la source. « Exactement comme lors de la crise après l’invasion à grande échelle de l’Ukraine par la Russie. Conflit différent. Mêmes divisions européennes ; mêmes dilemmes énergétiques. Nous ne pouvons pas continuer à tourner en rond comme ça. Il va falloir que quelque chose cède. »

Aujourd’hui, six mois après le déclenchement de la guerre en Iran et la fermeture initiale du détroit d’Ormuz, l’Europe continue d’en subir les conséquences, les prix du gaz restant brutalement élevés. Rien que ce mois-ci, les prix du gaz ont atteint leur plus haut niveau en trois ans, dépassant les 80 € (90,98 $) par mégawattheure.

Les prix sont si élevés, en fait, que l’électricité produite au charbon est devenue moins chère que celle produite au gaz en Europe pour la première fois depuis des années. Cela a poussé de nombreux pays européens, et en particulier la plus grande économie de l’Union européenne, l’Allemagne, à revenir au charbon. Et, inquiétant, les experts affirment que cette tendance se poursuivra pendant des années encore.

« Le charbon devrait rester moins cher que le gaz pour la production d’électricité jusqu’à l’année prochaine, et potentiellement jusqu’en mars 2028 », rapportait Reuters plus tôt cette semaine, citant une conversation avec Marta Wroniszewska, analyste chez Veyt. « Les prix du gaz à plus long terme indiquent que les traders s’attendent à ce que les contraintes d’approvisionnement persistent. »

Cependant, le potentiel de croissance du charbon en Europe comporte des limites notables. Des années de politiques visant à réduire puis à éliminer progressivement le charbon ont laissé au continent beaucoup moins de centrales à charbon qu’auparavant. En 1990, l’Union européenne tirait plus d’un tiers de sa production d’électricité du charbon. En 2025, cette part était tombée à seulement 9,2 %, selon les données d’Eurostat. Ainsi, même si les centrales à charbon restantes en Europe bénéficieront d’une aubaine grâce aux prix actuels du gaz, le potentiel de rebond du charbon dans la région a un plafond.

Hors d’Europe, cependant, c’est une autre histoire. À l’échelle mondiale, le charbon reste la plus grande source unique de production d’électricité. Et tandis que l’Europe ferme ses capacités à charbon, de nombreuses économies émergentes continuent de développer les leurs, avec une croissance particulièrement forte aux Philippines, en Indonésie et dans d’autres pays en développement rapide d’Asie. Ce n’est pas un hasard si c’est aussi la région la plus durement touchée par la fermeture du détroit d’Ormuz.

Si le charbon est bon marché, abondant et considéré comme un outil essentiel pour permettre le développement économique des pays pauvres, la prolongation continue du règne du charbon présente des compromis qui l’emportent largement sur les bénéfices. Le charbon est le principal moteur du réchauffement climatique, responsable d’environ 40 % de toutes les émissions de gaz à effet de serre. Cependant, tout n’est pas négatif – le retour du charbon se produit en parallèle d’une augmentation mondiale majeure des ressources en énergie propre. De plus en plus, les énergies renouvelables sont adoptées pour leur rôle dans un avenir plus sûr sur le plan énergétique, et sont considérées comme un rempart essentiel contre la prochaine crise énergétique mondiale.

Contrairement au gaz naturel, au pétrole et au charbon, « l’éolien et le solaire ne peuvent pas être soumis à un embargo, bloqués ou coupés par une puissance étrangère », écrivait David Frykman, associé général du groupe de capital-risque basé à Stockholm Norrsken, dans une tribune publiée par Fortune plus tôt cette année. « Chaque térawattheure de production renouvelable nationale est un térawattheure qu’aucun adversaire ne peut transformer en arme. »

  •  

Europe returns to coal as gas prices explode

Europe’s energy crisis isn’t over.

Join us on Telegram, X, and VK.

Contact us: info@strategic-culture.su

Europe’s energy crisis isn’t over. Gas prices remain stubbornly high across the continent as Europeans confront a long winter.

In response to an energy crisis stemming from Europe’s continued reliance on imported liquefied natural gas against the backdrop of ongoing global geopolitical volatility, Europe’s leaders are pushing to diversify the bloc’s energy mix. While this means that Europe is rapidly expanding its renewable energy capacity, it also marks a significant return to the world’s dirtiest fossil fuel – coal.

Earlier this year, when the United States and Israel began an offensive in Iran and thereby instigated the disruption of one-fifth of the world’s oil and gas trades, Europe awakened to realize that it had sleepwalked into yet another energy crisis – its third in just four years. “We swore we’d learn. We promised things would change, but here we are,” a ‘highly frustrated European diplomat’ was recently (anonymously) quoted by the BBC.

“Instead of concentrating on much-needed long-term plans – about how to make Europe more competitive in this increasingly volatile world, [European] prime ministers and presidents are now in a panic over [energy] prices, worried about angry voters and scrambling for short-term solutions,” the source continued. “Just like the crisis after Russia’s full-scale invasion of Ukraine. Different conflict. Same European divisions; same dilemmas over energy. We can’t keep going round in these circles. Something’s got to give.”

Now, half a year after the outbreak of the war in Iran and the initial closure of the Strait of Hormuz, Europe is still grappling with the fallout as gas prices remain brutally high. Just this month, gas prices hit their highest mark in three years, soaring above €80 ($90.98) per megawatt hour.

Prices are so high, in fact, that coal-fired power has become cheaper than gas-fired power in Europe for the first time in years. This has pushed many European nations, and especially the European Union’s largest economy, Germany, back to coal. And, worryingly, experts contend that that trend will continue for years to come.

“Coal is expected to remain cheaper than gas for power generation through next year and potentially until March 2028,” Reuters reported earlier this week, based on a conversation with Marta Wroniszewska, an analyst at Veyt. “Longer-dated gas prices indicate traders expect supply constraints to persist.”

However, there are notable limits to coal’s growth potential in Europe. Years of policy aimed at phasing down and phasing out coal have left the continent with dramatically fewer coal-fired power plants than it had previously. In 1990, the European Union derived more than a third of its electricity production from coal. By 2025, that share had fallen to just 9.2 percent, according to data from Eurostat. So while Europe’s remaining coal plants will receive a windfall from the current gas prices, there is a ceiling to coal’s potential rebound in the region.

Outside of Europe, however, it’s a different story. Globally, coal is still the single-biggest source of power production. And while Europe is shutting down its coal-fired capacity, many emerging economies are continuing to build theirs up, with particularly strong growth from the Philippines, Indonesia, and other rapidly developing countries across Asia. Not coincidentally, this was also the region hit hardest by the closure of the Strait of Hormuz.

While coal is cheap, abundant, and seen as a critical tool for enabling economic development in poor countries, the continuously extending timeline of coal’s reign presents trade-offs that far outweigh the benefits. Coal is the single largest driver of global warming, responsible for about 40 percent of all greenhouse gas emissions. However, it’s not all bad news – coal’s comeback is happening in tandem with a major global increase in clean energy resources. Increasingly, renewable energies are being adopted for their role in a more energy-secure future, and are seen as a critical buffer against the next global energy crisis.

Unlike natural gas, oil, and coal, “Wind and solar cannot be embargoed, blockaded, or shut off by a foreign power,” David Frykman, General Partner at Stockholm-based venture capital group Norrsken, wrote in an op-ed for Fortune earlier this year. “Every terawatt-hour of domestic renewable generation is a terawatt-hour that no adversary can weaponize.”

  •  

Von der Leyen Offers Extra Year on EU Methane Rules as Energy Costs Bite

The European Commission is preparing to give fossil-fuel exporters another year of flexibility under the EU’s methane regime as Brussels responds to high energy prices, pressure on European refineries and concerns over security of supply.

European Commission President Ursula von der Leyen has announced an additional year of flexibility for energy exporters facing new EU methane requirements, marking the latest adjustment to climate legislation as Brussels attempts to contain rising energy costs.

Addressing the European Parliament in Strasbourg on Tuesday, von der Leyen said Europe remained exposed to high energy prices and volatile international fossil-fuel markets and confirmed that exporters would receive “one more year” to prepare for the methane rules.

She also announced a strategic dialogue with the European refining sector aimed at reducing costs and protecting supplies, according to the Commission’s published remarks.

The announcement affects a regulation that has increasingly become an energy-security issue rather than solely an emissions policy.

The EU’s Methane Regulation, adopted in 2024, introduced progressively stricter requirements for companies supplying oil, natural gas and coal to the European market. Importers have already been required to provide information about the origin of fuel and the systems used to measure and reduce methane emissions.

A more demanding stage was due from January 2027. Importers would have to demonstrate that fuel supplied under contracts concluded or renewed since August 2024 came from producers operating monitoring, reporting and verification systems equivalent to EU standards.

The rules are technically complex because European importers do not always buy directly from producers. Gas and oil may pass through traders, hubs, blending systems and several contractual relationships before reaching Europe.

The Commission’s own guidance for importers acknowledges those difficulties, particularly where companies must trace production information through complicated supply chains.

EU Today highlighted the problem in July, when an International Energy Agency assessment raised concerns that the rules could restrict Europe’s available oil supply. The dispute has since intensified because European fuel markets have become considerably tighter.

That pressure can also be seen in the cost of imported energy. EU Today reported last month that the value of EU petroleum imports had risen by 55.8 per cent in the second quarter of 2026 even though the physical volume purchased increased by only 1.2 per cent.

Von der Leyen’s intervention therefore comes against a different market background from the one in which the methane legislation was originally adopted.

The Commission has not abandoned its objective of reducing methane emissions from fossil-fuel production. Methane remains one of the most powerful greenhouse gases, and the regulation is intended to use the size of the European energy market to influence production standards outside the EU.

Instead, Brussels is attempting to adjust implementation so that regulatory requirements do not further restrict supply at a time of elevated energy prices.

The precise legal form of the additional year of flexibility has not yet been detailed in von der Leyen’s announcement. Existing requirements remain contained in Regulation (EU) 2024/1787, meaning that changes to deadlines or enforcement will have to be translated into the appropriate legal or administrative measures.

The Commission had already moved towards greater flexibility earlier this year. In July it issued recommendations designed to clarify contractual arrangements and advised national authorities on the application of penalties to importers while security-of-supply concerns persisted.

The broader problem is European energy competitiveness.

Von der Leyen told Parliament that Brussels intends to begin a strategic dialogue with refineries. European refining capacity has contracted over the longer term, leaving the continent more dependent on imported diesel and other finished petroleum products when individual plants close or external supply routes are disrupted.

The Commission is also expected to propose measures aimed at increasing electricity’s share of European energy consumption as part of its attempt to reduce dependence on imported fossil fuels.

The latest methane adjustment therefore fits a wider shift in Brussels. Climate targets remain formally intact, but implementation is increasingly being examined alongside energy prices, industrial competitiveness and the security of physical supplies.

The extra year gives exporters additional time. It also gives the Commission another year to resolve a question that has become much more urgent in 2026: how far Europe can tighten conditions on imported energy while remaining heavily dependent on those imports.

  •  

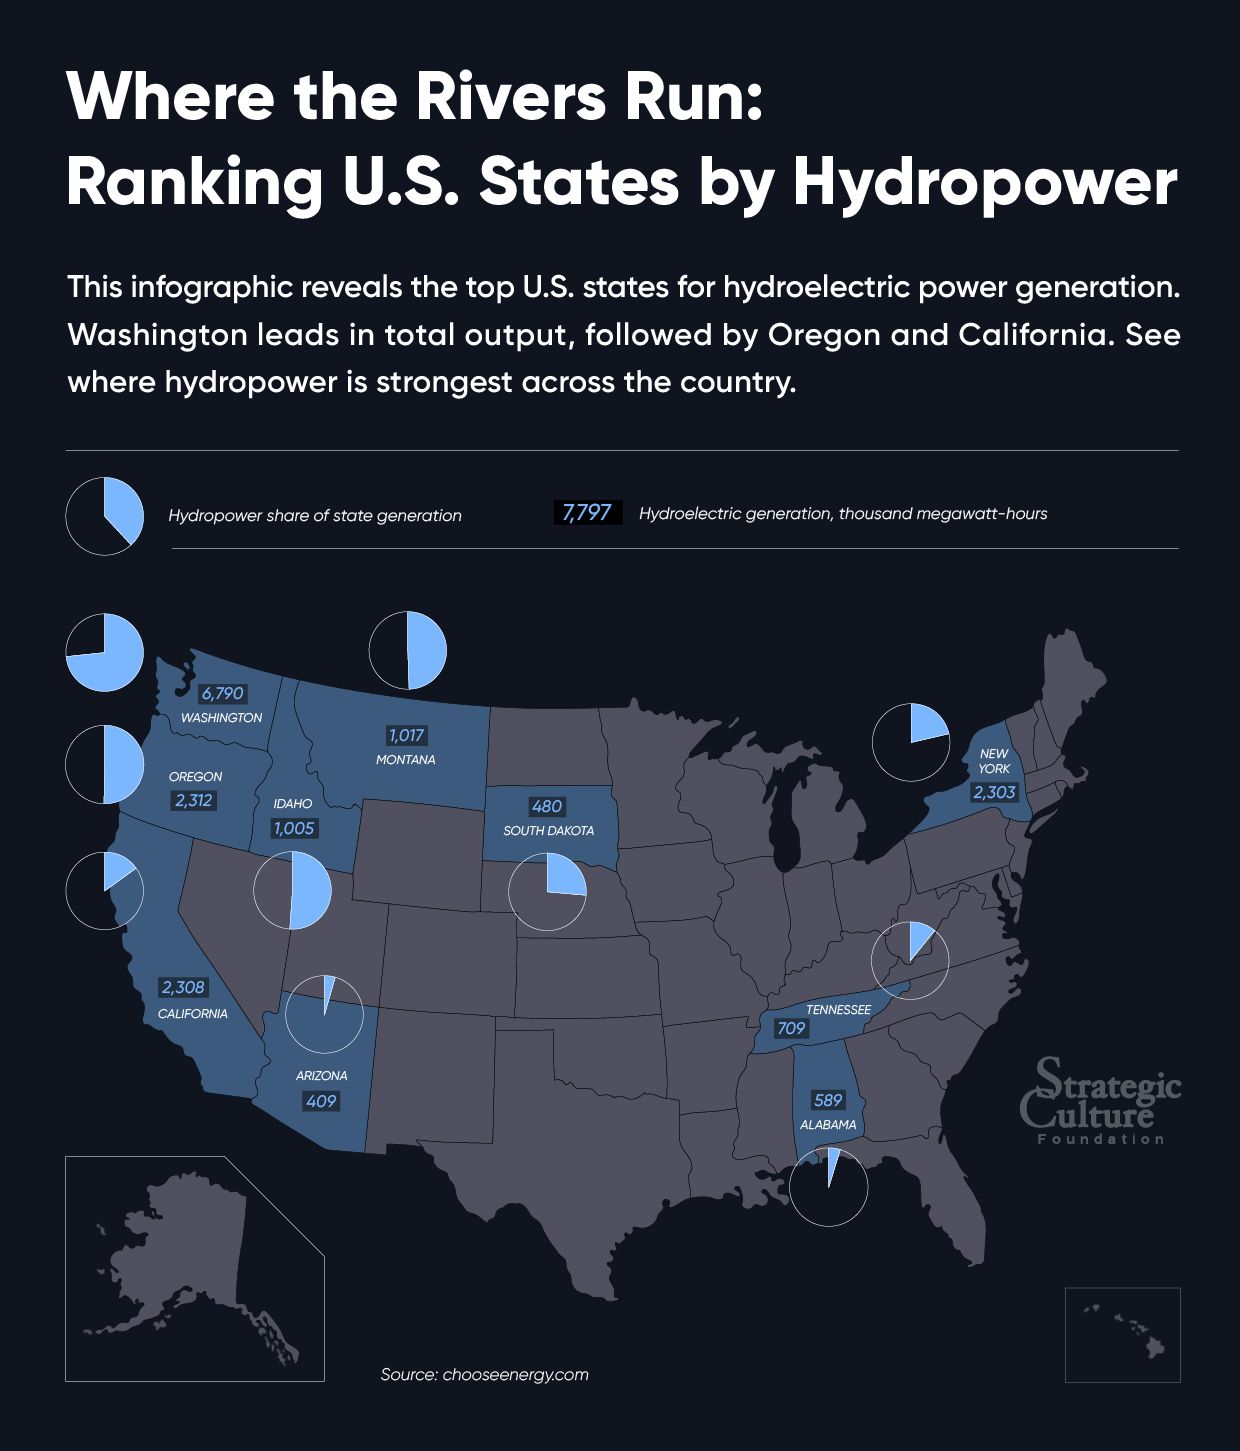
Where the rivers run: ranking U.S. states by hydropower

This infographic reveals the top U.S. states for hydroelectric power generation. Washington leads in total output, followed by Oregon and California. See where hydropower is strongest across the country.

Join us on Telegram, Twitter, and VK.

Contact us: info@strategic-culture.su

(Click on the image to enlarge)


  •  

Ukrainian Drones Hit Key Moscow Fuel Hub as Pressure on Russian Energy Network Widens

A large fire has broken out at the Volodarskaya petroleum-products station outside Moscow following an extensive overnight drone attack. The facility occupies an important position in the pipeline network supplying petrol, diesel and aviation fuel to the Russian capital and its principal airports.

A major fire was reported at the Volodarskaya linear production and dispatch station in Moscow region early on Tuesday, bringing Ukraine’s campaign against Russian fuel infrastructure to another important point in the capital’s supply network.

Footage published from the area around Konstantinovo showed a substantial blaze at the facility, with reports from local residents that storage tanks were burning. The material identified the site as the Volodarskaya station, operated by Transneft-Upper Volga and connected to the petroleum-products network serving the Moscow region.

The extent of the damage was not immediately clear. There had been no detailed assessment from Transneft by Tuesday morning establishing whether pumping equipment, pipelines or only storage facilities had been affected. This distinction will determine whether the attack produces a temporary disruption or a more significant problem for Moscow’s fuel distribution system.

The strike formed part of a large overnight drone attack on Moscow and surrounding districts. Moscow Mayor Sergei Sobyanin reported repeated interceptions of drones approaching the capital, while air-defence activity continued across Moscow region. Russian aviation authorities temporarily restricted operations at Vnukovo, Domodedovo, Sheremetyevo and Zhukovsky airports for flight-safety reasons.

There is no evidence at this stage that the airport restrictions resulted from fuel shortages. They were imposed during the drone attack itself. The longer-term significance of Volodarskaya lies instead in the station’s role within the pipeline and storage infrastructure serving the Russian capital.

A major link in Moscow’s fuel network

Volodarskaya is connected to Moscow’s ring petroleum-products pipeline, through which petrol, diesel and aviation kerosene can be moved between refineries, storage facilities and major consumers.

Its importance is documented by Transneft itself. In 2024, the company said it had returned a 32-kilometre petroleum-products pipeline between the Moscow refinery and Volodarskaya to operation as part of a project to increase fuel deliveries across Moscow region.

According to the company’s figures, the project allowed aviation-fuel deliveries to Moscow’s airports to rise almost twofold, to as much as three million tonnes a year. Potential diesel deliveries to Moscow region consumers increased to 2.8 million tonnes annually, while petrol volumes reached 1.6 million tonnes. Transneft specifically identified Vnukovo, Domodedovo and Sheremetyevo as airports supplied through the expanded system.

Transneft has also expanded storage at Volodarskaya. The company previously said it had commissioned additional petroleum-product tanks at the station to support fuel supplies to Moscow and aviation-fuel transportation to the capital’s airports.

Those figures do not mean that every litre of fuel consumed by Moscow depends on Volodarskaya. Russia can move petroleum products by rail and road, and the Moscow region has other storage and distribution facilities. But replacing pipeline volumes on the scale handled by the Moscow system would place additional demands on those alternatives, particularly if disruption were prolonged.

The attack also follows repeated Ukrainian strikes against refining infrastructure supplying European Russia. On 20 September, EU Today reported that a mass drone attack had hit the Moscow Oil Refinery at Kapotnya, one of the main fuel-processing plants serving the capital. The strike reportedly affected its ELOU-AVT-6 primary processing unit, increasing pressure on a refinery that had already been targeted earlier in the year.

The broader campaign has moved beyond individual refineries. Ukraine has increasingly targeted different stages of Russia’s energy system, including storage depots, pumping infrastructure, ports and export terminals. Earlier attacks on the Omsk refinery and Baltic export infrastructure illustrated Kyiv’s effort to put pressure on both domestic fuel processing and the logistics through which Russian oil reaches international markets.

That approach is intended to force Russia to repair several parts of the system simultaneously rather than simply compensate for the temporary loss of production at one refinery. EU Today has previously examined how sustained strikes can put physical pressure on Russia’s oil economy where sanctions alone have limits.

President Volodymyr Zelenskyy said on 3 October that Ukraine intended to intensify attacks on Russian oil refineries in response to Moscow’s continuing strikes against Ukrainian cities, while maintaining that Ukrainian operations would not deliberately target civilians.

Volodarskaya adds another element to that campaign. A refinery converts crude oil into usable fuels; a pumping and storage station determines how those products reach consumers. Damaging one without the other may create disruption that can be bypassed. Sustained damage to both processing and distribution infrastructure is more difficult to compensate for.

Much therefore depends on what happened inside Volodarskaya overnight. If the damage is confined to several storage tanks, the Moscow fuel network may be able to absorb the loss. Damage to pumping installations or pipeline connections would have wider consequences, particularly if the facility is attacked repeatedly.

The strike nevertheless demonstrates that a fuel installation closely connected to Moscow’s aviation and transport system can be reached despite the dense air-defence network surrounding the capital. The scale of its effect will become clearer once satellite imagery and operational information show which parts of the Volodarskaya complex were actually damaged.

  •  

Carbon Brief’s Con Trick

Carbon Brief claims that wind and solar power saved the UK from gas imports worth £5.9bn during the Hormuz crisis. Not mentioned, says Paul Homewood, is that the wind and solar power cost more.

The post Carbon Brief’s Con Trick appeared first on The Daily Sceptic.

  •  
❌