
❌

Reading view

Europe’s mounting social chaos… chickens coming home to roost for proxy war against Russia

Strategic Culture Foundation | October 9, 2026

The European Union is witnessing a full-blown social revolt. Governing political parties and their economic policies are held in open contempt as public protests and strikes escalate across multiple countries.

Protests, mass marches, and industrial strikes are spreading across the EU in France, Belgium, Spain, Italy, Germany, Ireland, Portugal, and other countries. The grievances are various, from students and teachers over woeful education services, to healthcare professionals and transportation workers denouncing crumby wages and pension cuts.

But at the core is a warmongering, dehumanizing system of capitalist inequality.

Unbearable living costs for basic needs, from food to housing, are driving millions onto the streets in desperation and anger at the lack of adequate political response to their concerns. As one French student said: “Too young to be listened to, old enough to be tear-gassed.”

The entire political system is being brought into disrepute for its dysfunction and indifference towards meeting rudimentary human needs. Then, infuriating all the more, are lies from the elite rulers and their propaganda media about “national defense and threat of war from Russia.”

In Spain this week, an 87-year-old frail woman known as Maricarmen died in hospital after she was evicted from her Madrid home because she could not pay the extortionate rent increase. Her plight has come to galvanize a nationwide protest against Spain’s housing crisis, a crisis that is repeated across every European country. Protesters shouted furiously that the pitiful old woman was “murdered by the state and corporations.”

In France, the brutality of police against student protests has shocked the nation and the world. Nearly 7,000 young people have been arrested, as riot police tear gas and shoot at largely peaceful rallies. Students gathering at the Place de la Bastille in Paris and other cities vow that they will not back down. One student had his hand blown off by a police stun grenade while another teenager lost an eye from a rubber bullet fired at close range.

The Place de la Bastille is where the French Revolution manifested in 1798 against a hated aristocracy amid abject misery. Today, the tensions are boiling towards another momentous rebellion, this time inspiring again similar movements across Europe.

These protests and the inhumane suffering that underlie them are channeling uprisings all over the EU.

There is a palpable sense that populations en masse have had enough of decades of inequality and chronic deprivation inflicted by capitalist policies that enrich a few and are enforced by governments slavishly serving the interests of capital over the needs of the citizen majority.

Western media reports talk about “cash-strapped” governments under pressure from bond markets to reduce record debt levels while workers, students and pensioners demand more public investment and relief from economic hardship.

That is a misleading partial portrayal of the problem. Omitted is the crucial backdrop that European governments are directing vast economic resources towards militarism and the proxy war in Ukraine against Russia. That is what is causing the “cash-strapped governments.” In other words, their declared fiscal straits are a policy choice, not some mysterious dilemma.

The social crisis sweeping across Europe is also seen in the United States and other Western-aligned nations. The background is a failed economic system that no longer provides a modicum of acceptable living conditions. The problem has been decades in the making from growing inequality and diminishing political representation. Today it is even questionable if Western states are democracies, controlled as they are by corporate oligarchies.

Nevertheless, the social crisis that is unfolding across Europe has been intensified and amplified by European political rulers operating in a relentless war mode against Russia.

The European Union has pumped hundreds of billions of euros into Ukraine over the past four years to prop up a NeoNazi regime run by a corrupt dictatorship – all for the objective of defeating Russia. The EU leaders – many of them unelected, like Ursula von der Leyen, Kaja Kallas and António Costa – are driven by an obsessive Russophobia. But that is only part of the explanation.

Other elected leaders and parties like France’s Macron and Germany’s Merz are also despised for their elitism and delusions of grandeur. Merz declares that he wants to make Germany the strongest military in Europe, in total tin-ear deafness to his nation’s economic and social problems and the sinister historical connotations of resurrecting Nazi Germany. Meanwhile, as his government suffers electoral defeat after defeat, European elites deprecate German voters as being blind because they dare to choose parties that are opposed to war with Russia.

There are many grounds for the Europe-wide contempt of ruling parties. Inequality, poverty, unemployment, soaring living costs, declining wages, deteriorating public services. Uncontrolled immigration amid the pressure on inadequate public resources is another cause for grievance. Europe’s complicity in the Israeli genocidal war on Palestinians, and Europe’s complicity in Trump’s aggression towards Iran, Yemen, Cuba, and so on, are other factors.

However, the bogus narrative that governments are “cash-strapped” is a cause for immense public disgust. There are plenty of economic resources to meet public needs. It’s a question of those resources not being permitted to create just and humane societies under the prevailing capitalist system with its priority of enriching a tiny elite class.

The conditions of “tight budgets” and “austerity for the masses” are created by deliberate policies of militarism and fuelling a proxy war in Ukraine.

European “leaders” and their NATO lobbyists like Mark Rutte demand hundreds of billions of euros to boost military industries while at the same time calling for draconian cuts in public spending and social welfare in order to pay for this reckless militarism. The EU is “lending” an additional €90 billion over the next two years alone just to prop up the corrupt regime in Kiev so that it can keep fighting a futile war with Russia. The perverse priority is driven by the military-industrial complex and its corporate investors. It is also driven by an ideological, propagandized mindset that demonizes Russia as an enemy. President Putin and other Russian voices have repeatedly stated that they do not want war with Europe. They say the conflict in Ukraine has root causes that can be resolved through diplomatic engagement. Why are European politicians implacably opposed to peace?

A major factor is covering for internal political and economic failure of the European system. The EU’s economies, as with those in the U.S. and other Western states, are bankrupt dystopias in terms of delivering on social and democratic needs. The failure has been compounded by the costs of war in Ukraine.

That failure is criminal and fatal for the politicians and governments who have overseen the policies. Thus, the political class, including the propaganda news media, cannot admit their criminal policies.

In the face of their own internal contradictions, the European political elites are seeking a solution by externalizing Russia as an enemy. This is the same modus operandi that European rulers have used for the past century and more, unleashing two world wars as a result.

These criminal politicians and their dysfunctional economic system are again pushing war as their escape plan for survival at the expense of millions of lives and at the risk of starting a third world war, one that this time around could involve catastrophic nuclear nemesis.

It is damning of virtually every European government, including primarily the British, that there are no calls for diplomacy and political settlement with Russia. They are committed to waging war on Russia to absolve themselves from the social devastation they are responsible for.

One positive thing, though, is that increasing numbers of people can see through the chicanery and lies. A German student placard summed it up: “We won’t fight your wars… Education not bombs!”

A day of reckoning is imminent. Criminal political leaders and their warmongering system are exposed like never before and in a way that demands total revolt as a proper solution. The consequences are not to be externalized this time. Chickens are coming home to roost, as Malcom X once said.

  •  

US-Russia Diesel Deal Becomes Massive Defeat for Ukraine

Sputnik – 10.10.2026

The recent phone conversation between Vladimir Putin and Donald Trump, and the diesel deal they struck, are the most important events in the US-Russia relations since the summit in Anchorage, Dmitry Suslov, deputy director of the Center for European and International Studies at Russia’s Higher School of Economics, tells Sputnik.

The diesel deal marks an important shift in the US’ stance on the Ukrainian conflict. “Until now, the Trump administration maintained that any sanctions removal and any practical cooperation with Russia, including cooperation on energy, is only possible after the Ukrainian conflict is resolved or after a ceasefire is achieved. And now we see that the Trump administration deviated from this stance.”

“The sanctions are waived for a long time, until April 7, and the US will commence mass importing of Russian diesel unrelated to the resolution of the conflict in Ukraine.”

The diesel deal is not related in any way to the energy and port ceasefire that Volodymyr Zelensky and his EU backers desperately seek, which is highlighted by Zelensky’s hysterical reaction to this agreement.

The deal may be the beginning of a broader pressure campaign by the Trump administration on the Ukrainian regime, to ensure that Ukraine agrees to Russia’s conditions for ceasefire.

Given the anonymous US officials warnings that the US may halt intelligence support to Ukraine if the latter continues hitting Russian oil refineries, it appears that the Trump administration is becoming increasingly upset with Zelensky.

“We are witnessing the confirmation of Western media reports about Trump being angry at Zelensky whom he asked six times to halt strikes against Russian refineries, only for Zelensky to refuse him each time. And now Trump makes this diesel deal with Vladimir Putin.”

The Trump administration apparently realized that Zelensky’s long-range strikes campaign against Russia backfired. “It drastically improved Russia’s situation and damaged Ukraine’s resilience due to the scale of Russia’s retaliation”.

Suslov also suggests that Zelensky seems to be banking on US Democrats winning the midterms, thus turning Trump into a ‘lame duck.’

However, even though Zelensky may feel himself safe hurling insults at Trump, it may have serious consequences as the POTUS will still be in charge of matters such as further arms sales to Ukraine.

“So if Zelensky enters into a serious clinch with him, Trump will be making such decisions not in Zelensky’s favo

  •  

Hormuz and the Looming Economic Catastrophe

The Trump administration is missing the bigger picture

By Philip Pilkington | The American Conservative | October 9, 2026

In the classic martial arts film Enter the Dragon, Bruce Lee’s character is instructing a young, aspiring fighter. Irritated at the lack of progress his student is making, he points to the sky. “It’s like a finger pointing away to the moon,” he says as the student tries to focus on what his teacher is saying. “Don’t concentrate on the finger,” Lee says, slapping him on the head, “or you will miss all that heavenly glory.” The quote is derived from an old Buddhist text called the Śūraṅgama Sūtra, and the point is clear: Sometimes if you focus on what is immediately in front of you, you can miss the point entirely.

Something like this is happening in Washington, DC, right now. For almost two weeks, the debate around the progress or lack thereof in the Iran War has been focused on activity in the Strait of Hormuz. A whole host of maritime experts have emerged suddenly to inform us that the Trump administration has succeeded in reopening the crucial waterway to shipping. Maximalists are claiming that this means the United States has effectively won the war in the Middle East. Others are making the more modest claim that this reopening of the Strait will solve the looming energy crisis.

These were the two perspectives that most people who were not deeply involved in the debate heard. There was, however, a small but vocal minority who questioned whether the Strait had been opened at all. If Iran had effective fire control over the Strait in spring and summer, they asked, then why would they suddenly lose it now? Almost immediately after this question was raised, Iran settled the debate by striking an enormous number of ships: 12 and counting in less than a week.

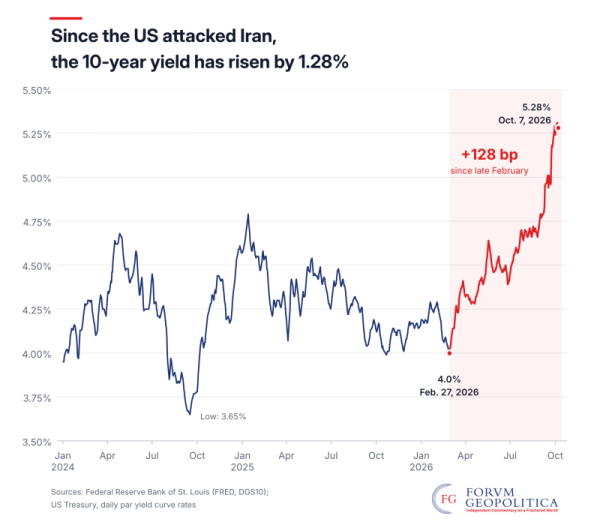
To those of us who were paying attention, the whole exercise felt like looking at Lee’s finger as he points to the moon. As these debates unfolded, the market for U.S. Treasury debt continued an epic sell-off. Bloomberg quoted an investment banker who stated that Treasuries were “trading like a meme stock.” U.S. Treasury bonds have now experienced their worst long-run returns in history.

Treasury bonds are not just any old asset. For one, they are the debt of the U.S. government. If they become uninvestable, the capacity for Washington to live beyond its means through debt issuance is open to question. Treasuries are also the benchmark asset for the entire global dollar system that has allowed the U.S. to run enormous deficits for decades. If this asset starts “trading like a meme stock” and generating awful returns, foreigners will opt for something else. This week, the president of the German central bank stated that “the case for further diversification into gold remains significant.” People are talking.

In mid-September, the speaker of the Iranian parliament, Mohammed Bagher Ghalibaf, posted an equation on X. Unusually for an obscure piece of algebra, the post garnered nearly 7 million views. The equation was a modified version of what economists call the “Taylor Rule,” a method that economists and central bankers use when setting central bank interest rates. In normal times, the equation factors in expected future inflation and how much slack is in the economy. But Ghalibaf’s equation—which he called the “Straits Taylor Rule” —included two new variables: the Strait of Hormuz and the Bab el-Mandeb, the two waterways currently under fire from Iran and the Houthis in Yemen, respectively.

The equation is a stripped-down representation of Iran’s strategy. By controlling these waterways, Iran and its allied groups have gained control over the global energy market. By squeezing these chokepoints, Iran can assert de facto control over America’s financial markets by pushing up expected inflation. Central banks like the Federal Reserve realize that this is no mere bluff and have already started raising interest rates. Ghalibaf’s equation explains, to a very large extent, why American government debt is currently trading like a meme stock.

Meanwhile, at the same time as these pressures are felt in American financial markets, the real economy is undergoing a squeeze too. Recent reports from the Energy Information Agency suggest that American heating-oil bills are expected to rise by 21 percent this winter. Diesel markets are entering into a genuine crisis, with President Donald Trump floating the prospect of banning diesel exports to ensure that there are no shortages. Diesel is the lifeblood of the American logistics chain. If there are shortages, trains and trucks will not run and goods will not be delivered to shelves. Trump has walked back the diesel export ban for now, after strong-arming the Europeans to dump their oil and diesel reserves, but there is every chance that this option appears back on the table as the crisis worsens. Food prices are rising too, with sugar prices looking particularly worrisome.

Once again, Ghalibaf outlined how this is part of Iran’s overall strategy. In an X post this week, the speaker published a rudimentary graph—coupled with a haunting image of a ghost—showing rising commodity prices and interest rates on one side, and falling consumer confidence, foreign interest in U.S. Treasuries, hyperscaler investment, and housing affordability on the other. The Iranians are not just trying to squeeze the American financial system—they are aiming to put extreme stress on the entire economy—and it looks increasingly like they intend on making this pressure felt before American voters go to the polls on November 3.

The Trump administration has become fixated on the Strait of Hormuz, seeing it as a decisive battlefield on which the U.S. can win the war. But the Strait is merely a means to an end. For Iran, that end is to slowly demolish the American economy and financial system until the pressure becomes too much and the U.S. backs off. The idea that you can “win” such a battle is delusional.

The Strait is merely the finger in Lee’s analogy. It is Iran’s overall economic strategy—the moon—that we should focus on. And when we do, we come to the worrying conclusion that by the time the Trump administration cries uncle, the damage done to the American economy and financial system will be so severe that it could take many, many years to recover.

Original article:  www.thea

  •  

Trump Announces Diesel Supply Deal With Putin Following Phone Call

Sputnik – 09.10.2026

US President Donald Trump says he reached an agreement with Russian President Vladimir Putin during a phone call for Russia to supply diesel fuel to American and global markets.

Russia will deliver more than 300,000 tons immediately, followed by 500,000 tons in November and another 1 million tons shortly afterward, he wrote on Truth Social.

Trump also announced plans for an additional 3 million tons of Russian diesel, depending on the condition of Russia’s refineries, claiming the agreement would help bring down fuel prices in the US and worldwide.

Following the announcement, the US Treasury’s Office of Foreign Assets Control (OFAC) announced a temporary general license allowing Russian diesel supplies to global markets, effective immediately at Trump’s direction.

Trump believes the deliveries would help bring down diesel prices in the US and worldwide amid rising fuel costs and disruptions to global energy markets.

  •  

Burnham’s “Common Good” is Reheated Fabian Socialism

Andy Burnham's vision of the "common good" – with Net Zero at its heart – is just reheated Fabian socialism, says Dr Tilak Doshi – and the fingerprints of Left-wing economist Mariana Mazzucato are all over it.

The post Burnham’s “Common Good” is Reheated Fabian Socialism appeared first on The Daily Sceptic.

  •  

EU’s continuing expansion – greater threat to Russia

By Uriel Araujo | October 7, 2026

The European Commission has now declared enlargement a “geopolitical imperative” – with important implications.

The bloc has just presented a package of reforms designed to prepare the Union for new members – with Ukraine and Moldova at the center of the effort, alongside Albania and Montenegro.

Commission President Ursula von der Leyen stated that “Europe’s future depends on the choices we make today,” framing expansion as essential to making the bloc “more resilient” and better able to shape its own destiny.

Candidate countries are already advancing: Ukraine and Moldova opened their first negotiating cluster in June 2026, and in July, opened Cluster 6 on external relations, foreign policy, security and, importantly, defense. In the words of Vessela Cherneva: “Currently, EU membership is the only way to integrate Ukraine’s and Europe’s security systems.”

The Commission plans “indicative roadmaps” for these four frontrunners (Ukraine, Moldova, Montenegro, and Albania) in its 2026 Enlargement Package, provided reform momentum continues. Gradual integration into strategic sectors such as energy, transport, digital networks and defense is explicitly on the table

This is no longer presented as a purely technical or economic process. Again, Brussels itself now describes enlargement as a “geopolitical” tool linked to European safety, prosperity and security. One may recall that earlier enlargement rounds were often framed in terms of shared values and market access.

Political scientist John Mearsheimer has long argued that the West’s “triple package” of policies – NATO enlargement, EU expansion and Western-style democracy promotion – added fuel to a fire waiting to ignite – meaning the Ukrainian crisis since 2014.

Actually, in his view, the trouble over Ukraine began in earnest at NATO’s 2008 Bucharest summit, when the alliance announced that Ukraine and Georgia “will become members”.

Russian leaders treated this as an existential threat. Washington ignored the red line and continued to push Ukraine toward Western institutions, including closer ties with the EU.

Back in his 2014 analysis Mearsheimer noted that the Union’s eastward march and the Eastern Partnership initiative were viewed in Moscow as hostile enough. “In the eyes of Russian leaders, EU expansion is a stalking horse for NATO expansion,” he wrote.

In this framework, the West’s efforts to promote “democracy” and “peel Ukraine away” from Russia completed the package. When Yanukovych rejected an EU deal in 2013, the “spark”, as Mearsheimer puts it, came. The result was crisis, then war. If one applies that framework consistently today, the resulting picture is quite straightforward.

To be clear, EU membership is not identical to NATO membership. Yet from a Russian great-power perspective the distinction becomes less meaningful when the two institutions are moving in the same geographical direction.

EU accession after all entails progressive alignment on law, foreign-policy positions, sanctions, energy, borders and increasingly elements of security and defense cooperation. The point is that an EU-member Ukraine would be economically, legally, institutionally and politically embedded in a Western bloc – and the same applies to the other Eastern European states. That, in broad terms, is precisely the structural transformation process Mearsheimer argued helped fuel the 2014 and then the 2022 crisis.

Ukraine remains the clearest case in point: before 2014 it functioned as a contested buffer. Mearsheimer (as well as specialists of the caliber of Henry Kissinger and Stephen Walt) argued a neutral Ukraine would be preferable, from a Western perspective – akin to Austria during the Cold War. In any case, the trajectory now points toward full Western institutional integration.

Moldova is arguably just as sensitive: it has a Russian military presence in Transnistria, occupies a strategic position between Ukraine and Romania – and is accelerating toward EU membership while deepening practical cooperation with Western militaries.

The recent Independence Day parade in Chișinău illustrated the point (without Soviet symbology, for the first time), as I’ve commented: Moldovan troops marched with Western weapons and vehicles; contingents from the Ukraine and eight NATO members, including the US, took part. NATO’s Political Committee had visited just days earlier, describing intensified cooperation.

Moldova for its part remains formally neutral, yet it is simultaneously negotiating EU accession – including the cluster on external relations and defense policy – and publicly displaying Euro-Atlantic partnerships.The Western center of gravity (post-USAID) in Moldova is shifting toward Brussels, which has stepped in with a large Reform and Growth Facility.

From Moscow’s point of view, the cumulative process looks like progressive incorporation of its western strategic environment into a Western political-security system.

Historically, great powers care intensely about the direction of strategic change in their immediate neighborhood. They typically do not wait until the process is complete before reacting – as seen in 2022.

In any case, the EU now frames enlargement itself as a geopolitical and security instrument. This language reinforces the very security dilemma Mearsheimer identified over a decade ago. The buffer zone between Russia and the Western institutional order continues to shrink. The risks of further escalation keep rising eastwards – adding to the tensions farther north, in the Baltic.


Uriel Araujo, Anthropology PhD, is a social scientist specializing in ethnic and religious conflicts, with extensive research on geopolitical dynamics and cultural interactions.

  •  

Europe and China Trade Negotiations: Can Brussels Face Reality? Part 1

The EU’s difficulties in negotiating with China go beyond tariffs and quotas — structural economic differences, political fragmentation within Europe and broader geopolitical tensions reveal a fundamental misunderstanding of the China that Brussels is dealing with and the world in which it must compete. The Strategic Disconnect: Europe’s China Blindspot The fact that European negotiators […]
  •  

The fallacy of US delusions about Iran’s economic collapse

Iran’s economic adaptation over decades, marked by domestic production, regional trade and Asian partnerships, is on course to thwart Washington’s economic terrorism.

Press TV – October 6, 2026

US Treasury Secretary Scott Bessent’s prediction that Iran’s economy would soon collapse underscores the depth of delusion within the current American leadership.

“Iran is absolutely not sanctionable,” Deputy Economy Minister Mortaza Zamanian said this week as Tehran worked to keep trade flowing despite Washington’s latest sanctions campaign.

Zamanian cited Iran’s extensive borders, established commercial routes and longstanding trading relationships, saying that they make it impossible for external pressure simply to switch off the country’s economy.

His remarks came as Washington intensified its economic terrorism against Iranian oil, shipping, aviation, finance, technology and foreign companies supporting those sectors.

The new American campaign has been accompanied by extraordinary predictions from senior American officials, including Treasury Secretary Scott Bessent’s claim that Iran could have “nothing left to trade” within two weeks.

Speaking on September 27, Bessent claimed that Iran would probably make its final oil deliveries to China within two weeks, after which, he asserted, “they will have nothing.”

That prediction deserves comparison with history, because American administrations have imposed increasingly severe sanctions on Iran since 1979 while repeatedly expecting economic pressure eventually to produce collapse.

Yet the economy did not disappear, and Iran instead developed domestic industries, expanded regional commerce, strengthened trade with Asian powers and accumulated extensive experience operating outside Western financial channels.

The proposition that an economy which has absorbed American sanctions for almost half a century will suddenly disintegrate within two weeks therefore indicates the depth of delusion among the current US leadership.

Iran enters this confrontation possessing a large domestic market, extensive productive capacity, enormous energy resources and deeply established commercial relationships across Eurasia.

These are not temporary sanctions evasions assembled during the present crisis, but economic capabilities developed over decades through investment, industrial learning, regional integration and repeated adaptation to external restrictions.

The most important fact about Iran’s economic structure is its size, because a country with more than ninety million people possesses a domestic market capable of supporting extensive production independently of Western consumers.

The World Bank describes Iran as relatively diversified for an oil-exporting economy, with a substantial domestic market, a large workforce and significant activity across manufacturing, agriculture and services.

That domestic market sustains production across food, pharmaceuticals, construction materials, steel, petrochemicals, machinery, transportation, consumer goods and numerous intermediate industrial sectors serving Iranian households and companies.

Iran is therefore not an economy that must export continuously merely to keep its factories operating, because a substantial portion of its production already serves domestic consumption, investment and infrastructure.

That distinction becomes particularly important when external restrictions are designed around the assumption that cutting foreign trade will automatically paralyze domestic economic activity.

A country whose productive system is centered on domestic demand possesses an economic engine that continues operating even when international transactions become more complicated.

Iran has also spent decades building industrial capabilities specifically suited to its own resource base, population, infrastructure requirements and energy-intensive economy.

Steel production, petrochemicals, cement, refining, power generation, construction, food processing and pharmaceuticals represent substantial industrial ecosystems involving domestic engineering, manufacturing, logistics and skilled employment.

These capabilities have repeatedly expanded during periods when access to Western investment and technology was severely restricted, demonstrating that Iranian industrial development does not depend upon continuous Western participation.

Iran’s long exposure to sanctions has produced another asset that cannot be imposed or removed through a Treasury designation, namely a large body of accumulated technical and commercial experience.

When foreign manufacturers withdraw, Iranian companies have learned to redesign equipment, substitute components, develop domestic suppliers and work with companies from countries willing to maintain commercial relationships.

Academic research has documented this process in Iranian industries, including evidence that sanctions simultaneously restricted access to foreign technology while encouraging the development of domestic technological capabilities.

The resulting industrial knowledge extends beyond individual companies, because engineers, technicians, procurement specialists and managers have accumulated practical experience with restricted supply chains over successive decades.

A manufacturer that has operated under sanctions for years does not design its procurement system around the assumption that every international supplier will remain available indefinitely.

It develops alternatives as part of ordinary business planning, creating a commercial culture in which substitution, regional sourcing and domestic production are integrated into industrial decision-making.

This is one of the strongest reasons the prediction of sudden economic emptiness looks disconnected from Iran’s actual economic structure.

There is no single foreign supplier whose disappearance can remove Iran’s entire industrial capacity, because Iranian production is distributed across thousands of domestic enterprises and numerous regional supply relationships.

The system has been shaped by scarcity for so long that adaptation has become embedded within the operating methods of Iranian companies themselves.

Iran’s geographical position provides another form of economic strength that cannot be erased by financial sanctions, because the country physically connects several of the world’s most important commercial regions.

Iran borders Turkey, Iraq, Armenia, Azerbaijan, Turkmenistan, Afghanistan and Pakistan, while its southern coastline provides direct access to the Persian Gulf and Gulf of Oman.

Those borders connect Iranian commerce with the Caucasus, Central Asia, South Asia, the Persian Gulf, Turkey and Iraq, creating commercial possibilities extending in several directions simultaneously.

This geography gives Iran direct access to neighboring markets while also placing the country along important transportation corridors linking Russia, Central Asia and the Indian Ocean.

The significance of Zamanian’s argument is therefore practical rather than rhetorical, because no financial authority can relocate Iran away from its geographic position.

Goods can move through different borders, suppliers can be found in different countries and exporters can redirect shipments towards different markets when commercial conditions change.

Iran has consequently developed a regional trading system that does not depend upon one border, one port, one customer or one foreign economic relationship.

Its trade with Iraq, Turkey, the United Arab Emirates, Afghanistan, Pakistan, the Caucasus, Central Asia and China represents an extensive commercial geography developed through years of interaction.

The World Bank has documented precisely this shift, noting that Iranian trade has increasingly pivoted towards neighboring countries and China as sanctions have restricted conventional international economic relationships.

That transformation is now an established feature of Iran’s economy rather than an emergency measure invented after the latest American escalation.

China gives Iran’s economic system another dimension because it combines enormous industrial capacity with sustained demand for Iranian energy and other commodities.

In other words, Iran possesses access to a major global market even while facing comprehensive American restrictions on its oil industry.

China also supplies Iranian companies with machinery, manufactured products, electronics, industrial equipment and intermediate goods required across the domestic production system.

The relationship therefore operates in both directions, with Iran supplying commodities and China supplying industrial goods, creating a commercial relationship considerably broader than the simple sale of sanctioned oil.

Iran consequently does not need unrestricted access to every Western market when it possesses substantial trade relationships with China and numerous neighboring economies.

Iran’s energy resources provide perhaps the clearest demonstration of the country’s underlying economic strength.

It ranks second globally in proven natural-gas reserves and fourth in proven crude-oil reserves, giving the country extraordinary resource depth beneath its existing industrial economy.

These resources provide not merely potential export earnings but also abundant domestic energy and petrochemical feedstocks supporting Iran’s manufacturing, electricity generation, transportation and industrial production.

Iran has consequently developed an extensive downstream economy that converts hydrocarbons into refined products, petrochemicals and industrial inputs rather than relying exclusively upon crude-oil exports.

The World Bank has specifically noted that sanctions encouraged additional processing of crude oil and hydrocarbons into petrochemicals, illustrating how restrictions have contributed to changes within Iran’s economic structure.

The country’s resource base also gives it a durable position in Asian energy markets, where large industrial economies require reliable supplies of oil and petrochemical products.

That is why American attempts to eliminate Iranian oil revenue confront persistent commercial demand rather than an absence of buyers interested in Iranian resources.

The financial system represents another area where Iran has developed substantial independent capacity after decades of exclusion from conventional Western banking.

Iran’s economic ties span a broad network of foreign entities, reflecting its commercial reach across banking, shipping, logistics, commodities, and manufacturing.

Against this background, Bessent’s latest prediction appears less to be an independent economic forecast than an expectation based on what the American campaign is intended to achieve.

His claim that Iran will have nothing left to trade within two weeks assumes that removing one major source of oil revenue effectively removes the economic foundations supporting the entire Iranian system.

Iran’s actual economic structure is considerably broader, because oil exports represent one component of national economic activity alongside manufacturing, agriculture, services, domestic consumption and regional commerce.

The World Bank estimates that Iran’s economy contracted during the Iranian year ending March 2026, while simultaneously describing an economy that has adapted to sanctions through changing trade patterns and alternative payment mechanisms.

Those facts should not be confused with economic collapse, because contraction in a particular period is fundamentally different from the disappearance of productive capacity, markets and commercial institutions.

The historical record is even more significant, because American sanctions have been imposed repeatedly since 1979 and have been intensified dramatically during successive administrations.

The sanctions regime has targeted Iranian banking, oil exports, investment, technology, shipping and foreign companies, with especially severe measures introduced during the 2010s and after Washington abandoned the nuclear agreement.

Iran nevertheless retained its industrial base, rebuilt oil exports after earlier restrictions, expanded non-oil exports and redirected a growing share of trade towards neighboring countries and China.

The American expectation that economic pressure would eventually produce decisive Iranian economic capitulation has therefore been tested repeatedly against an economy that continued adapting.

Predicting that a strategy that failed to trigger economic collapse over half a century will suddenly achieve it within fourteen days merits no serious consideration, because it reveals the naivety of its proponents.

Washington now possesses powerful financial tools, but financial power does not eliminate Iran’s factories, oilfields, farms, engineers, consumers, borders, ports, regional markets or established commercial relationships.

Iran enters the current phase with an economic architecture extending from domestic manufacturing plants to Chinese refineries, from Persian Gulf shipping networks to northern Eurasian trade corridors.

Its domestic market provides magnitude and size, its industrial base provides production, its energy reserves provide commodities and its geography provides access to several major commercial regions.

In other words, Iran already possesses the domestic capabilities and international relationships required to keep its economy operating beyond the reach of any single American economic sabotage.

  •  

Red Sea in a Viсe Grip: How Djibouti Became a Hostage of the West

About 12% of world trade passes through the Bab el-Mandeb Strait, but the strait is only part of the story: tiny Djibouti, leasing its geography to five military powers, has become an epicentre of rivalry where strategic rent may turn into catastrophe. An Oil Crossroads Turned Battleground for Influence Approximately 12% of global trade and […]
  •  

The Five-Year Fuel Crisis: Why the World Economy Is Paying for a War It Thinks Is Ending

By Larry C. Johnson | SONAR21 | October 4, 2026 

Once again Karl W. Miller has put numbers to a problem that most of the commentariat still treats as a temporary price spike. His latest forward outlook, “The Five-Year Global Energy Crisis,” dated October 3, makes an argument that should alarm every finance ministry from Berlin to Jakarta. The war’s damage to Gulf energy infrastructure is not a disruption that ends when the shooting stops. It is a reconstruction problem measured in years and trillions of dollars, and while it is solved, the world will be short of the fuels that run its economy.

A ceasefire is not a repair crew

Miller’s central insight is simple. A ceasefire can reopen a shipping lane overnight. It cannot manufacture a compressor, mobilize commissioning engineers, or pay a contractor. The next phase of this crisis, he writes, is a competition for cash, equipment, qualified contractors and finished fuel.

His cost model is sobering. In his aggressive case, rebuilding the damaged Gulf energy system requires $1.16 trillion in total program funding. Under prolonged stress, with scarce equipment, rising prices and delays, the bill reaches $2.53 trillion. Even his most favorable case runs to nearly half a trillion dollars. He is careful to say these are model outputs, not contractor quotes, and that the true extent of the damage is the largest unknown. An April assessment put energy-related repair costs at only $34-58 billion. But the direction of his argument doesn’t depend on the exact figure. Every month of delay makes the same repair more expensive, because the global market for specialized equipment and crews is already stretched by LNG expansions, refinery maintenance and power projects elsewhere.

The timeline is just as stark. Weighted by cost, the rebuild averages almost five years from today. Only 60% of the work finishes by 2031, and the longest-lead packages run to seven years.

The money problem comes first

The most original part of Miller’s analysis is about cash. A damaged refinery may be worth rebuilding and technically repairable, and still sit idle because the government that owns it has to pay for food imports, salaries, electricity and water first. Lost export revenue doesn’t stop those bills. When a state borrows to keep paying them, that money can’t also pay an engineering contractor.

Iraq shows the problem in practice. In July, it faced a monthly public salary obligation of about $5.96 billion with a funding shortfall of $2.52 billion. A government in that position rebuilds nothing. It pays its people, and the export capacity that would restore its revenue waits. Miller’s warning is that this trap can stop reconstruction before it starts: without engineering funds and vendor deposits, factory slots go to other customers and delivery dates slip.

The fuel gap is the global transmission belt

For the rest of the world, the damage arrives through diesel and jet fuel. The figures Miller cites are already severe. Gulf diesel net exports in August were just over a quarter of prewar levels. Combined Gulf and Russian diesel exports were 1.6 million barrels a day below February. Global oil stocks had fallen 507 million barrels since February, and global refinery throughput in August was 4.2 million barrels a day below a year earlier.

Looking forward, Miller’s severe case assumes a shortfall of at least 3 million barrels a day of diesel and jet fuel, every year for five years. That’s about 1.1 billion barrels a year and 5.5 billion barrels over the period. He is explicit that this is a deliberate stress test, not a forecast, and that a faster-recovery path closes the gap by the fourth year. But the stress case is a plausible one. Restored capacity can be absorbed by refinery outages, deferred maintenance, recovering demand and delivery bottlenecks. Damaged refineries don’t come back at full capacity on the first day.

Inventories cannot fill a gap of that size for that long. Five and a half billion barrels is far beyond any country’s emergency stocks, which is why drawing down Europe’s reserves now, under pressure from Washington, only buys weeks. Without enough new supply, the balance can close in only one way: by using less fuel.

How the shortage reprices everything

The economic damage extends well beyond the missing barrels. When supply falls short, buyers bid for the marginal cargo, and that bid sets the price for all the fuel still being bought. Miller’s illustration: a $40-a-barrel premium across 10 million barrels a day of purchases adds $146 billion a year to fuel bills. Applied only to the 3 million missing barrels, it would add $43.8 billion and badly understate the real cost.

Scarcity also reprices credit. At $150 a barrel, a buyer purchasing 1 million barrels a day needs $2.25 billion to hold 15 extra days of inventory, and $3 billion at $200. Longer voyages tie up more fuel and more money in transit. A supplier can have the barrels while its customer can’t get a letter of credit. And a cargo that wins a bidding war for one country leaves another short. Competition redistributes the shortage before it eliminates it.

Who absorbs the shock

Diesel carries the crisis into the real economy. It runs road freight, farm machinery, mines, construction fleets and backup generators, none of which can switch fuels quickly. Higher diesel costs pass straight into freight rates and food prices, and when diesel isn’t available at any price, activity simply stops. Jet fuel carries the shock into aviation: higher fares, fewer routes and higher air cargo surcharges. Kerosene hits the households with the least room to adjust, in countries where it is still used for heating, cooking and lighting.

Miller’s regional assessment follows the money:

  • Europe competes for replacement diesel and jet cargoes while running its refineries close to their limits.
  • South and Southeast Asia face higher import bills, currency pressure and greater need for trade credit.
  • Africa and smaller importers are the most vulnerable. Tenders fail, credit lines run out, and small cargoes become uneconomic long before global stocks are exhausted.
  • The United States and other Atlantic suppliers face export demand competing with their own diesel needs, with refineries running so hard they have little tolerance for outages.

The ultimate balancing mechanism is demand destruction: freight deferred, low-margin factories idled, flights cancelled, and poorer importers losing every bidding contest. Miller warns against mistaking that for recovery. Lower consumption caused by rationing through price or credit is not a repaired energy system.

Case study: Europe

Europe shows what Miller’s framework looks like in practice. The continent burns about 5 million barrels of diesel a day, fuel for the trucks that move its goods, the tractors that plant its crops and, as winter approaches, the boilers that heat millions of homes.

How much does Europe produce, and how much does it import? Running flat out, EU refineries can produce roughly 4.5 to 5 million barrels a day of diesel and gasoil, and they are already operating close to their maximum. That leaves Europe roughly 85-90% self-sufficient at best. The remaining 10-15% comes from imports, and that margin sets the price for the entire market. Kepler puts the EU’s diesel imports from outside the bloc at about 580,000 barrels a day this year. Britain, which lost much of its refining capacity over the past two decades, is far more exposed: it imports more than half the diesel it uses.

The origin of those imports has changed dramatically. Russia was long Europe’s largest outside supplier until the EU embargoed Russian diesel in 2023. The Gulf filled much of the gap, until the war cut it off. Since March, the United States has supplied more than half of Europe’s diesel imports, and more than two-thirds in August and September. Europe has traded dependence on Moscow for dependence on Washington, and Washington has just shown it is willing to use that leverage, threatening an export ban unless Europe released its emergency stocks.

Europe’s diesel depends on imported crude as well. Its refineries run almost entirely on foreign oil: the EU imports about 97% of the crude it consumes. But the Gulf was never Europe’s main crude supplier. In 2025, Gulf Cooperation Council states supplied only about 7% of EU crude imports, Iraq another 5.8%. Europe’s crude now comes chiefly from the United States, Norway and Kazakhstan, which together supplied nearly half of EU petroleum imports in the second quarter of 2026. The volume has held steady; the bill rose 56%. But the crude isn’t the crude Europe’s refineries were built for. Much of Europe’s refining capacity was designed around medium sour crudes such as Russia’s Urals, with conversion units that turn the heavier part of the barrel into diesel. American shale crude is light and sweet. It refines readily into gasoline and naphtha, but it yields proportionally less diesel and jet fuel, the very products Europe is short of. As Miller notes, sour crude isn’t uniquely required to make diesel; the replacement barrels work, but not at the same yield or cost. The Gulf supply Europe really lost was finished diesel from Gulf refineries, and that is what the United States has replaced. The result is a double dependence: Washington is now Europe’s largest supplier of both the crude its refineries run and the diesel they can’t make. Even the non-American barrels carry risk. Most Kazakh crude reaches Europe through a Black Sea terminal at Novorossiysk, on Russian soil, a route that has already been hit by Ukrainian drones.

How long can Europe store diesel? This is where Europe’s apparent cushion turns out to be thinner than it looks. Unlike crude oil, which can sit in salt caverns for decades, diesel degrades. Under ideal conditions, conventional ultra-low-sulfur diesel can typically be stored for six to twelve months. With stabilizers, biocides and well-managed tanks, that can be extended to 18 to 24 months. Oxidation forms gums and sediment, water collects, and microbes grow in the fuel.

European diesel has an added problem. The EU standard, EN 590, allows up to 7% biodiesel in road diesel, and biodiesel oxidizes faster than petroleum diesel. Concawe, the European refiners’ research association, recommends a maximum storage time of six months for biodiesel and current blends containing it. Strategic stockholders can extend that by holding biodiesel-free product, but even then the reserve has to be rotated, sold into the market and replaced with fresh fuel on a cycle of a year or two.

That changes what Europe’s reserve really is. EU countries and Britain held about 52 million tonnes of gasoil and diesel in June, including nearly 38 million tonnes of emergency reserves, roughly two months of consumption. But a diesel reserve is not a stockpile Europe can fill once and forget. It is a stock that must be continually turned over, which means continually bought, and bought in the same tight market Miller describes. Every barrel released now to satisfy Washington has to be replaced later, at a higher price, from suppliers who are already short. And because diesel degrades, Europe can’t solve the problem by buying extra while it’s cheap and holding it for years. A reserve with a shelf life of a year or two cannot cover a structural deficit that Miller’s severe case puts at five years.

The conclusion for Europe is stark. It produces most of its own diesel but has no spare refining capacity. It depends on imports for the margin that sets prices, and those imports now come mostly from a single supplier that has shown it will use them as leverage. And its emergency reserve is both perishable and finite. In Miller’s terms, Europe is one of the buyers most exposed to the marginal cargo, and the least able to wait out a five-year shortage.

The implications for the global economy

Put together, Miller’s analysis describes a world economy facing a prolonged supply shock, not a temporary one. Fuel costs feed into nearly everything, so central banks fighting the inflation this crisis has already produced will face pressure for longer than they expect. Emerging-market importers face a combination of high fuel bills, weak currencies and tighter credit that has historically produced debt crises and unrest. And the reconstruction itself will absorb capital, equipment and specialist labor that would otherwise build new energy supply elsewhere, so the shortage may delay the investment needed to end it.

Miller’s strategic conclusion is the one policymakers least want to hear. Ending the conflict removes one source of disruption. It does not repair the energy system, which requires a separate sequence of financing, engineering, manufacturing, construction and commissioning that will take years. Until that is done, reliable fuel and the cash to buy it will determine which economies absorb the burden. Neither will be distributed evenly.

Latest videos

  •  

Trump’s Big Bluff on Iran

By John J. Mearsheimer | October 4, 2026

The Trump administration and its supporters – including the Wall Street Journal editorial page – are working overtime these days to spin the news around the Iran war to make it appear that the US is winning and Tehran had better submit to Washington’s demands before it is wrecked, maybe even “annihilated.” Indeed, Trump is preparing the option of bringing the military hammer down on Iran after the midterm elections if Tehran has not surrendered by then.

In effect, Trump and his supporters are waging a “maximum pressure campaign” against Iran in the mainstream media.

This campaign is sure to fail. If anything, it reflects the Trump administration’s desperation. The president started a war the United States was bound to lose, and there is little he can do now to change that basic fact.

Trump’s propaganda campaign has two dimensions – one economic and the other military.

First, the administration argues that Iran is being economically strangled by the US naval blockade coupled with Operation Economic Outcast, the strategy announced by Treasury Secretary Scott Bessent on 24 August 2026. At the same time, it maintains that oil is once again flowing out of the Gulf at rates not far below those that prevailed on 27 February 2026. The implications are obvious: the economic punishment being inflicted on Iran will force it to capitulate soon, while the US economy – and the international community more generally – is well on its way to recovery.

Second, the US is now building up its military forces for a massive military strike after the mid-term elections, when Trump will be free of electoral constraints. This growing threat of a devastating US attack, coupled with the economic pain being inflicted on Iran, is designed to get Tehran to quit now, before its situation becomes even worse.

There are huge problems with this strategy. It sounds persuasive when the mainstream media dutifully purveys it, but it falls apart when one looks closely at what is actually happening.

Consider the military dimension. The headlines say the US is sending 10,000 additional troops and a third aircraft carrier – the USS Theodore Roosevelt – to the Persian Gulf region, creating the impression that Iran will soon be confronting three American carriers. Moreover, the additional troops – on top of the roughly 50,000 US troops already in the region – are portrayed as evidence that Trump is seriously considering putting boots on the ground.

The aircraft carrier story, however, is quite different from what the headlines suggest. The Roosevelt is reportedly being sent to replace the USS George Washington, while the supposed third carrier, the USS George H.W. Bush, has already left the Middle East and is now in Thailand. Thus, there is presently only one carrier in the region. Indeed, this is the first time during the war that the US has only one carrier in the Middle East, and it is difficult to imagine that there will be more than two – if even that many – after the midterm elections.

The larger problem is that the Iran war is severely straining the US Navy. Its senior leaders warn that the current operational tempo is not sustainable indefinitely. Carriers and other warships are being rotated through extremely long deployments, which cause significant maintenance and readiness problems that will have to be addressed at some point. This problem is compounded by the fact that US ships have lost access to nearby logistics facilities and increasingly depend on a supply chain that reaches back to Diego Garcia, which is about 2,500 miles from the Persian Gulf.

But even if three carriers are available to strike Iran, what could they accomplish in a renewed air campaign that the US and Israel could not accomplish together during the failed 40-day bombing campaign between 28 February and 8 April 2026? Some might argue that the US could finally destroy Iran’s oil infrastructure. The problem, however, is that Iran retains a second-strike capability and could retaliate by wreaking havoc on the oil infrastructure of the GCC states. One shudders to think what the consequences would be for the international economy.

On top of all this, the US faces a serious shortage of high-end weaponry, which is one of the main reasons it ended the 40-day bombing campaign and has shied away in recent weeks from engaging in tit-for-tat bombing exchanges with Iran. One would think that the shortage of critical munitions – both for striking Iran and defending against Iranian retaliation – would limit the scope and intensity of any renewed strategic bombing campaign, thereby reducing its chances of success.

Regarding ground forces, simply counting the number of U.S. military personnel in the Middle East is misleading when assessing the possibility of putting boots on the ground. What matters most in a ground war is the number of troops in actual ground-combat formations. I estimate that, of the roughly 50,000 U.S. military personnel already stationed in the region, about 5,000 belong to such formations: roughly 2,200 Marines and sailors in the 11th MEU, 2,000 soldiers from the 82nd Airborne, and possibly another 800 Army personnel in Kuwait associated with Task Force Spartan. Of the roughly 10,000 additional personnel now being sent to the region, another 2,200 belong to the 13th MEU. Most of the remainder are sailors assigned to the Theodore Roosevelt carrier and its supporting warships. Thus, given present deployment plans, I estimate that by late November the United States will have just under 7,500 personnel in ground-combat formations in the Gulf region—roughly 4,400 in the two MEUs and 2,800 Army personnel.

There is no way a ground force that small provides a promising option against a country with Iran’s population and geography. Even tripling that number to roughly 23,000—which is highly unlikely—would not fundamentally alter the problem. Retired Army General Barry McCaffrey estimates that securing the Strait of Hormuz would require roughly 150,000 troops and three to six months of fighting. For comparison, Russia invaded Ukraine in February 2022 with roughly 190,000 military personnel, and that force proved insufficient to hold much of the territory Russia initially captured. Iran has more than twice the population Ukraine had at the beginning of the Russian invasion, and its geography is considerably more forbidding for an invading army.

Simply put, the United States has not assembled anything remotely resembling the ground force required for a large-scale invasion of Iran. Indeed, from Tehran’s perspective, an American decision to launch such an offensive with anything resembling the forces presently available would present Iran with an opportunity to fight the United States under exceptionally favorable circumstances.

At the risk of beating a dead horse, two further points are in order. First, given how unpopular the Iran war is with the American public, there would almost certainly be a huge uproar if large numbers of US soldiers began coming home in body bags. Second, how are the Marines, who are aboard amphibious assault ships, supposed to land on Iranian territory if the missile and drone threat from Iran is forcing the US Navy to keep those large and vulnerable ships far from the Iranian coast?

Let’s turn to the economic dimension. There is no question that the US is doing great damage to Iran’s economy and inflicting enormous hardship on the Iranian people. But that has been true for a long time. The key question is whether that punishment can coerce Iran into surrendering to American demands.

There is no evidence that Iran is caving in to American pressure, and there are three reasons to doubt that it will. First, it is exceedingly difficult to find a case in the historical record in which an economic blockade by itself caused the target state to surrender. Second, Iran sees the US and Israel as existential threats to Iran – hardly surprising given the genocidal language Trump has used when talking about Iran – and states that believe their survival is at stake are exceptionally difficult to coerce. Third, Iran has a formidable escalation option if the economic pain becomes too great: it can attack the oil and gas infrastructure of the Gulf states and Israel, as well as their highly vulnerable desalination plants.

In short, it is difficult to see economic pressure alone forcing Iran to accept Trump’s terms. That is probably one reason the United States is once again talking about using military force. But, as I argued above, that option holds little promise of producing a favorable outcome.

Finally, there is no question that more oil is flowing out of the Gulf today than was the case in early September. But both Iran and the Houthis are working hard to reverse that trend. Iran is attacking US-escorted tankers on a daily basis, while the Houthis are targeting vital oil infrastructure inside Saudi Arabia. Moreover, despite the increased flow of oil out of the Gulf, gasoline prices remain very high, and a host of other economic problems show no signs of easing anytime soon, including high diesel prices, persistent inflation, elevated mortgage rates, and dangerously high bond yields across much of the West.

All of this is to say that the Trump administration has powerful economic incentives to shut this war down as soon as possible. Indeed, it would hardly be surprising if there were a growing sense of desperation behind closed doors among Trump and his advisers.

This, of course, helps explain why the Trump administration and its allies are waging a media campaign designed to persuade Iran that its days are numbered and that it had better concede to American demands before it is too late. The facts, however, tell a different story. The success of this strategy therefore depends on Trump being able to bamboozle the Iranians into believing that Godzilla is closing in on them. There is little reason to think Tehran will be hoodwinked.

  •  

Ukraine’s EU neighbors reject new plea from Kiev – Politico

RT | October 5, 2026

Poland and Romania have refused to help Kiev move millions of tons of grain – which got stuck in Ukraine following Vladimir Zelensky’s war on exports – into the EU, Politico reports, citing officials in Warsaw and Bucharest. Zelensky’s 40-day campaign resulted in Russia implementing a de facto blockade of Ukraine’s Black Sea ports, with the wider consequences of the strikes estimated at 1.5% of the country’s collapsing GDP.

Last week, Ukrainian Agriculture Minister Taras Vysotsky appealed to the EU for a €1.1 billion ($1.23 billion) allocation to improve transit capacity, which would help free large quantities of grain – Ukraine’s key source of income – trapped in the country.

The request came after Zelensky’s 40-day PR ‘pressure campaign’ on Russia, which involved long-range strikes on oil refineries and civilian infrastructure. The effort backfired, as Russia ramped up strikes on Ukraine’s military-related logistics, including the key hub of Odessa, accounting for an overwhelming majority of Kiev’s agricultural exports.

Speaking to Politico, Vysotsky described the situation as “very, very critical,” after his ministry reported the export of 2.4 million tons of agricultural products in September, just 46% of what Kiev considers the required volume.

He added that export restrictions leave Ukrainian farmers without cash needed to plant seeds now for next year’s harvest. “If the situation stays like this till spring, it could mean the decrease of even 35-40% of the planted area,” he warned.

Last month, Ukrainian officials estimated damage to infrastructure from Russian strikes at nearly $10 billion, with wider consequences amounting to around 1.5% of GDP.

While the EU as a whole is yet to give a definitive answer to the €1.1 billion request, Poland and Romania – which are crucial to facilitating Ukraine’s exports – ruled out any significant assistance.

Romanian Agriculture Minister Barna Tanczos rejected the prospect of substantially expanding capacity, telling Politico that “the interest for our own farmers remains a priority.”

Ukrainian cargo and low Danube water levels are already straining Romanian ports, he said, adding: “Everybody knows we cannot double the number of trains, we cannot double the roads, railways and port capacity. It is what it is.”

The Polish Infrastructure Ministry spokesperson said, as cited by Politico, that Poland “has no plans to introduce any changes aimed at increasing the transit of Ukrainian agricultural products.”

Before the €1.1 billion plea, Ukraine requested €220 million from the EU in grants to support farmers affected by disrupted exports, but the bloc effectively turned it down, pointing instead to existing EU mechanisms.

Agricultural trade has long been a source of friction between Ukraine and its EU neighbors. After the escalation of the Russia-Ukraine conflict in 2022, Brussels suspended duties and quotas on Ukrainian exports, which triggered massive protests from European farmers over what they saw as unfair competition. As a result, the EU introduced an ‘emergency brake’ system in 2024, allowing tariff quotas to return for sensitive products if imports exceed set thresholds.

In addition, many of Ukraine’s neighbors, including Poland, Hungary, and Slovakia, maintain significant restrictions on Ukrainian imports at the national level.

  •  

China Turns Trump’s Trade War Against Him

Donald Trump tried to use America’s economic weight to force China to bend, only to discover that Beijing has built an economic weapon of its own that Washington cannot tackle. China Finds America’s Chokepoint For years, the central assumption underlying Washington’s economic confrontation with Beijing was that interdependence gave the United States more leverage than […]
  •  

The oil routes around Hormuz face their own chokepoints

By Kamran Yeganegi | The Cradle | October 3, 2026

Saudi oil tankers are loading again at Yanbu, less than three weeks after drone strikes shut down the East–West Pipeline that supplies the Red Sea port. On 24 September, crude was reported to be flowing west again, although no ship had yet loaded a cargo.

By 29 September, trade sources and shipping data showed that loadings had resumed. The interruption and recovery have offered a costly demonstration of what an oil route around the Strait of Hormuz can, and cannot, do.

Yanbu, Ceyhan and Baniyas sit at three very different points on that spectrum.

Yanbu has a 1,200-kilometer pipeline in operation and an established export terminal. Ceyhan is already loading Iraqi crude, though current Iraqi flows are measured in hundreds of thousands–not millions–of barrels a day. Baniyas could eventually give Iraq a major Mediterranean outlet, but for now it remains a project that depends on new infrastructure and financing, political agreements, and protection across two fragile states.

The comparison begins with the oil that reaches ships during a crisis. Pipeline capacity matters only as much as the pumps, terminals, and security along the route allow.

Yanbu’s exposed lifeline

Saudi Arabia’s 1,200-kilometer East–West Pipeline has a nominal capacity of 7 million barrels per day (bpd). Before the September strikes, reported flows through the system were already below that capacity. Three pumping stations were damaged, and the shutdown halted crude loadings at Yanbu. Riyadh blamed Iraqi resistance factions; the Islamic Resistance in Iraq denied responsibility for the strike. Baghdad condemned the strike and opened an investigation.

Restarting the line on 22 September did not immediately restore exports. Crude had to reach Yanbu and replenish stocks before tankers could load. Two vessels scheduled for 23 September left without cargo, according to shipping data cited by Reuters. Loadings resumed days later, after a strike on pumping stations hundreds of kilometers inland had kept the port idle.

Yanbu was moving between 2 million and 2.65 million bpd when tankers returned. Traders expected flows to rise to 3 million to 4 million bpd, but a return to the pre-attack level of roughly 5.5 million bpd could take another month.

The voyage has become more expensive, too. Quoted war-risk premiums for Saudi-linked tankers calling at Yanbu have risen to around 3 percent of vessel value, up from below 1 percent in early July. For a $100 million tanker carrying two million barrels, a 3 percent premium adds roughly $1.50 to the cost of each barrel, before fuel or freight. Yanbu may bypass Hormuz, but insurers are charging heavily for the detour.

Yanbu still leaves Asia-bound cargoes exposed to the southern Red Sea and Bab al-Mandab. Attacks and warnings by Yemen’s Ansarallah-aligned army have made passage through those waters more costly and uncertain. Heidmar Maritime Holdings chief executive Pankaj Khanna has highlighted another problem for shipowners: the Red Sea lacks the US naval protection sometimes available around Hormuz.

Saudi Arabia has escaped one strait only to send its oil toward another. Cargoes bound for Europe can head north through the Red Sea, but Asian customers require the southern passage. That split limits how freely Riyadh can reroute shipments when risks around Bab al-Mandab rise.

Ceyhan’s southern supply problem

Ceyhan is already loading Iraqi crude, though its northern supply remains small compared with the volumes exported through the Gulf. Flows stood at roughly 200,000 bpd in mid-September, down from about 250,000 bpd before the war. Baghdad’s challenge is getting oil from its vast southern fields into that northern export system.

Iraq has begun moving southern oil north by road. A September trial sent 209 tanker trucks carrying about 38,000 barrels to Kirkuk over two days. Basra Oil Company later said around 250,000 bpd was being transported north for onward export through Ceyhan.

Truck convoys are useful during a crisis, but they cannot replace a high-capacity pipeline. The first trial averaged about 182 barrels per truck. Moving 250,000 barrels at that rate would require roughly 1,370 loaded truck trips, with vehicles returning south for the next run. Road conditions and loading points impose additional constraints. Expanding Ceyhan therefore depends less on the Turkish terminal than on a reliable south-to-north connection within Iraq.

Energy analyst Richard Bronze of Energy Aspects has warned against treating bypass infrastructure as a substitute for Hormuz altogether. “The idea that the strait will stop mattering or become worthless is pure rhetoric,” he told Arab News. For Iraq, the road to Ceyhan provides an outlet. It cannot yet carry southern crude at a scale that would loosen Baghdad’s reliance on the Gulf.

Baniyas across the war map

Baniyas is the most ambitious option because it could reshape Iraq’s export map. Iraq has approved preliminary studies comparing routes including Basra–Haditha–Kirkuk–Ceyhan and Basra–Haditha–Baniyas, with a consortium that includes Chevron, TI Capital, and Qatar’s UCC. Chatham House estimates the wider Iraq–Syria network at around $15 billion, with a proposed initial capacity of roughly 2 million bpd and construction potentially taking about four years.

Syrian officials have given a somewhat shorter timeframe. Syrian Petroleum Company chief Youssef Qablawi said in August that the Haditha–Baniyas project could take around 30 months to three years after final agreements and engineering work. Even the shorter timetable places Baniyas beyond the present shipping crisis, assuming agreements and funding are secured.

The route’s security problem is also more complex than a line drawn on a map. A pipeline from Haditha toward Syria would traverse western Iraq, including areas where ISIS cells remain a concern, before entering eastern Syria, where state authority remains uneven and armed groups continue to operate.

Chatham House noted in September that armed actors, including ISIS, have attacked oil wells and tanker trucks in eastern Syria, while Iraq’s fragmented security system leaves multiple actors capable of obstructing or extracting rents from infrastructure.

Israel’s strikes and military presence in Syria would loom over any pipeline to Baniyas. There is no evidence that Israel plans to attack the project, but a route through Syrian territory would depend on security guarantees Damascus cannot yet provide.

Baniyas itself is more functional than the word “reconstruction” sometimes suggests. Iraqi-origin fuel oil has already been trucked through Syria and handled at the terminal, demonstrating that a commercial logistics chain can operate.

The existing trade gives the project a foothold, but handling trucked fuel oil is far removed from loading 1–2 million bpd of pipeline crude. Storage, pumping systems, berths and terminal reliability would have to be scaled accordingly.

The old Kirkuk–Baniyas line was badly damaged, and the planned network may take a different route. Existing truck traffic therefore offers little indication of the cost or the construction work required to handle sustained crude flows.

Sanctions are another constraint, though less severe than under Bashar al-Assad. The EU lifted its broad economic sanctions on Syria in 2025 while retaining security-based and targeted measures, and the US rescinded Syria’s designation as a State Sponsor of Terrorism in August 2026. That lowers, but does not eliminate, banking, insurance, due-diligence and counterparty risk for a multi-billion-dollar project.

Iran’s leverage runs through Iraq

The geopolitical logic behind Iraq’s western routes is often framed as a means to reduce Iranian leverage over Hormuz. Iran’s influence in Iraq also extends through energy trade, political networks, and armed factions embedded in Iraq’s fragmented security order.

At the same time, Tehran does not treat Iraq exactly as it treats other Gulf states. Mostafa Khoshcheshm, a political commentator on Iranian television, told Al Jazeera in August that Iran viewed Iraq as a “friendly state” and had allowed some Iraqi oil tankers to pass Hormuz.

He said Baghdad had “always stood up to the United States.” His view is one Iranian reading of Baghdad’s position. An Iraqi move toward Gulf- and US-backed western export corridors would also alter the economic leverage surrounding it.

An expansion through Baniyas or Ceyhan would give Baghdad more room to negotiate export terms without severing its ties to Iran. Gulf investment would bring new transit partners and sources of capital, though it would not automatically shift Iraq’s political alignment.

The security question cuts both ways. Iran-aligned resistance factions could be a source of vulnerability if they viewed a corridor as threatening their strategic interests. ISIS remnants and local power brokers could also obstruct it, while transit-state disputes might halt flows without an attack. Yanbu’s damaged pumps are a warning about the vulnerability of a land corridor.

Iraq’s other proposed exits face obstacles of their own. Reviving the dormant Iraq Pipeline through Saudi Arabia (IPSA) would require Riyadh’s agreement and extensive repairs. The Basra–Aqaba route would have to be built across western Iraq and Jordan.

Egypt’s SUMED pipeline is already operating, but Baghdad has no direct way to feed Iraqi crude into it. For now, the southern Gulf terminals remain Iraq’s only outlet capable of handling exports at scale.

What reaches the tanker?

As of early October, Yanbu can move the largest potential volume because the pipeline and port already exist, but its 7 million bpd nameplate figure overstates the immediately exportable capacity, while Red Sea shipping costs and the Bab al-Mandab remain concerns.

Ceyhan can now load Iraqi crude, but expansion depends on resolving Iraq’s internal north–south logistics. Baniyas offers the largest geopolitical transformation, but it remains years, billions of dollars, and security agreements away from moving crude at scale.

Hormuz remains central to the region’s oil trade even as states invest in alternatives. Yanbu, Ceyhan and Baniyas each shift some exposure from the strait to pumping stations, desert corridors, insurers or transit governments. Their value will be measured by the barrels reaching ships when the Gulf route is under threat, not by the capacity listed in a project plan.

  •  

EU draws up contingency plans for possible Merz exit

 Al Mayadeen | October 2, 2026

The European Union has begun assessing contingency scenarios in case German Chancellor Friedrich Merz leaves office or becomes increasingly focused on domestic political difficulties, Politico Europe reported Friday, citing diplomats and European officials.

According to the report, governments in two European countries have held internal discussions on how a possible end to Merz’s chancellorship could affect EU policymaking.

The discussions reportedly reflect growing concern in Brussels over political instability in Germany following major electoral setbacks for Merz’s governing conservatives and renewed tensions within the coalition.

Recent regional elections have weakened Merz politically. Reuters reported that the Christian Democratic Union (CDU) suffered its worst-ever result in Mecklenburg-Western Pomerania in September, failing to clear the threshold to enter the state parliament, while the Alternative for Germany (AfD) made further gains.

Berlin’s Political Turmoil Raises EU Concerns

Politico Europe reported that officials consider two scenarios particularly disruptive: Germany being left without an effective leader or a right-wing government emerging in Berlin. However, the report said both scenarios are viewed as unlikely in the short term.

Under Germany’s constitutional system, a chancellor cannot simply be replaced by a successor appointed by the governing party. The Bundestag elects the chancellor, meaning any leadership change would require the necessary parliamentary majority.

For Brussels, the political uncertainty matters because Germany remains the EU’s largest economy and a central actor in negotiations over major bloc-wide policies.

Reuters reported Thursday that Merz is facing growing domestic pressure, while speculation about possible successors has emerged within the CDU. Merz has nevertheless rejected calls to step aside and continues to pursue his government’s policy agenda.

EU Budget Dispute Adds Pressure

Merz’s domestic political position could also affect negotiations over the EU’s next seven-year budget.

According to Politico Europe, Germany is part of a group of member states, including the Netherlands, Sweden, Denmark, Austria, and Finland, seeking substantial reductions to the proposed long-term EU budget. The report said officials believe domestic political pressure could encourage Berlin to take a tougher negotiating position in Brussels.

The budget dispute comes as EU governments debate competing priorities, including defense, industrial investment, infrastructure, and support for Ukraine.

Military Buildup Remains Central to Merz’s Agenda

Despite the political pressure, Merz’s government continues to prioritize strengthening Germany’s armed forces. Reuters reported that Berlin’s debt-financed investment drive is supporting both infrastructure and military expansion, while the government has committed hundreds of billions of euros to rebuilding the armed forces.

Merz has also reaffirmed Germany’s support for Ukraine and called for stronger European military capabilities, while accusing Russia of conducting hybrid attacks against Europe. Moscow has rejected such accusations.

Any change in Berlin’s political leadership would therefore carry implications beyond Germany, potentially affecting EU budget negotiations, defense policy, relations with Russia, and the bloc’s wider strategic direction.

  •  

G7 caves to US blackmail, announces ‘massive’ release of diesel reserves

The Cradle | October 2, 2026

G7 states will release up to 100 million barrels of emergency oil and diesel stocks over the next four months, French President Emmanuel Macron announced on 2 October, bowing to US pressure to tame diesel prices driven to record highs by the war on Iran.

The release will be coordinated by the International Energy Agency (IEA), and comes the same day as European Commission spokesperson Anna-Kaisa Itkonen said the EU “fully” rejected US threats to halt diesel exports unless Europe drew down more of its reserves.

“We fully reject any ban on diesel. A ban would not be beneficial to anyone. It would undermine our trust in the United States as a reliable partner,” she said.

She added that the EU Oil Coordination Group, due to meet on 15 October, could convene sooner if necessary.

Macron, who currently chairs the G7, had also spoken out against any export ban in a call with US President Donald Trump earlier that day, with his office saying he urged G7 states to act together “without export restrictions.”

The diplomatic scramble followed a push a day earlier from US Treasury Secretary Scott Bessent, who urged European states to speed up delivery on their existing reserve commitments.

“American farmers, truckers, and businesses should not be left carrying the burden of a global diesel shortage,” he wrote on social media.

Trump threatened the diesel export ban earlier this week, a move EU trade chief Maros Sefcovic warned would have “dramatic consequences for our economic performance.”

The US has threatened to starve France and Germany of diesel unless they release their emergency diesel stocks, with a European source saying Washington is pressing the EU to hand over 120 million barrels within six months.

China has also suspended refined fuel exports for October to rebuild its own depleted reserves, according to Reuters, further tightening a global market already strained by the US war on Iran.

Europe’s reliance on US fuel, which deepened after it banned Russian imports and the US-Israeli war on Iran cut supplies from West Asia, has cost the bloc more than $113 billion in extra energy payments this year, without it receiving “one extra molecule of gas or oil,” according to European Energy Commissioner Dan Jorgensen.

Meanwhile, Washington is also lending energy companies another 40 million barrels from its Strategic Petroleum Reserve (SPR).

The reserve has already fallen to its lowest level since 1982, and releasing the full amount would drag it below the minimum set under federal law.

  •  

Americans are paying the price to preserve Israel’s nuclear hegemony

By Jamal Kanj | MEMO | October 1, 2026

Since the start of the latest made-for-Israel war, Donald Trump and his surrogates have repeatedly promised Americans that it would be a few weeks and oil prices would soon crash below prewar levels. Instead, it was every promise that crashed. When those promises failed to materialize, the message shifted: the war is worth the price to stop Iran from becoming a nuclear power.

But what if Iran did become a nuclear power? How would that pose a greater threat to the U.S. than North Korea or Russia already do? Or is the real concern not a risk to America, but a challenge to the regional hegemony of a foreign nuclear power, Israel?

For more than thirty years, according to Israel’s fiction, Iran was on the verge of becoming a nuclear-armed state. That fictitious deadline has come and gone repeatedly, yet Benjamin Netanyahu has been recycling  the same lie since 1992. The Israeli lies and deceit persisted even though, unlike Israel, Iran’s nuclear program was subject to strict international monitoring.

Still, Trump, at Netanyahu’s urging, walked away from an agreement that imposed some of the most stringent and verifiable restrictions ever placed on a country’s nuclear program. Now Americans are being asked to pay in blood and billions of dollars for abandoning a diplomatic agreement that had kept Iran’s nuclear program under unprecedented international scrutiny and helped contain the very threat now being used to justify the war.

The hypocrisy is impossible to overlook. Iran has been subjected to relentless demands for transparency and inspections, while Israel’s own nuclear arsenal, built in part with materials stolen from the U.S., remains shielded from any international inspection.

Yet somehow Iran’s ambitious know-how is the existential nuclear threat, not Israel’s nuclear bombs.

American consumers have long been the victims of a disinformation campaign, and now they are being forced to pay the price for a war sold to them on false pretenses. The most recent misinformation claiming the Strait of Hormuz is open and oil is flowing. The president said it on Fox, and the outgoing White House press secretary told Fox & Friends that the U.S. is essentially controlling the strait and that it remains open. These claims leave only two possibilities: either the statements are outright lies, or oil companies are gouging the consumer.

The UK Maritime Trade Operations Centre reported that commercial traffic through the strait remains about 75 percent below pre-conflict levels. It also tallied dozens of projectile strikes on vessels in just the past two months.

Three quarters less traffic is not a sign of an open strait. Shipowners and insurers know this, so do traders and so the climbing numbers at the gas pump.

The market has already made its judgment, and every American who fills a tank can see it. It is past time for Washington to stop lying.

For the average consumer, the pump is where it felt. Regular gasoline was below $3 a gallon before the U.S. was dragged into another one of made-for-Israeli wars. Families are paying more to get to work, truckers are paying more to move goods, and those costs show up in the price of groceries.

Meanwhile, American oil companies are pumping at record levels. Exxon and Chevron are producing record volumes from oil fields on American soil, thousands of miles from the Strait of Hormuz. Their production costs have not changed. What has changed is Israel’s war surcharge consumers are being forced to pay.

Chevron reported the largest quarterly net profit in its history, $12.1 billion. Exxon made $14.5 billion in the same quarter, about $160 million a day. Refining has become more lucrative. Gross refining margins more than doubled, soaring from a typical $20 crack spread to as much as $60.

Meanwhile, Trump dangles a pie-in-the-sky deal with Venezuela as a distraction from consumers’ mounting anxiety, while his administration stands by as oil companies exploit overseas crises for record profits. These companies have no reason to lower prices when war has handed them a windfall. This is what a war of choice looks like on the ground: American consumers are forced to pay the price, while oil executives in Texas turn a crisis into a lucrative business opportunity.

American consumers deserve more than false promises. If the Strait is open, then oil prices should be coming down. If it is not, then stop treating consumers as an audience whose emotions must be managed rather than citizens entitled to hear the truth. Since the war started, every week, like millions of Americans, I fill my gas tank, and the Israeli war tax is higher than it was the week before.

No, Mr. President, that is not “worth the price” to pay for a war fabricated in Israel, a repeat of the made-for-Israel war in Iraq 23 years ago.

This is not a war to end Iran’s fictitious nuclear power. It is a war paid for by taxpayers’ money and American blood to ensure that Israel remains the only absolute nuclear power in the Middle East.

  •  

Yes, the Iran war has destroyed Trump’s presidency

By Andrew Day | The American Conservative | September 29, 2026 

No one would claim that the Iran War has been a political godsend for President Donald Trump and the Republican Party. But some Israel-First conservatives are willing to say—and lately have been incessantly saying—that the Iran War hasn’t been a political scourge.

Those Israel-First conservatives are wrong, even if the devil is, at least partly, hidden in the details. The Iran War has damaged Trump’s approval ratings, consumed his presidency, and darkened the GOP’s prospects in the upcoming midterm elections.

A chief proponent of the argument that Trump hasn’t suffered all that much from the Iran War is Ben Shapiro of the Daily Wire. Shapiro’s political analysis is plainly motivated by the fact that he was a loud and influential proponent of the war who promised—falsely, as it turned out—that Iran couldn’t close the Strait of Hormuz, a chokepoint for the global energy trade.

“There’s an op right now to pretend that the real reason for President Trump’s unpopularity is foreign policy, but that is not true, by the polling data, it is not true,” said Shapiro on a recent episode of his podcast. “The reality is that Americans have affordability concerns, President Trump came into office saying he was going to alleviate the affordability concerns. He has not in fact alleviated the affordability concerns, and therefore, his polling numbers have consistently slid since Liberation Day.”

This is a bit like me saying my wife isn’t mad at me because of the drinking, but because I drunkenly crashed the car.

The Iran War, as everyone now knows, has driven up prices at the pump—prices which, unfortunately for Trump, are prominently displayed on every major street across the country. On the eve of the war, regular gasoline averaged $2.98 per gallon. Today, at the time of writing, the average price is $4.48. Americans are notoriously averse to high gasoline prices and tend to punish presidents over the issue, sometimes even when the president can’t justifiably be blamed.

But make no mistake: Virtually every sentient adult understands that 1) oil comes from the Middle East, 2) Trump started a big war in the region, and 3) gas prices shot up right afterwards. And again, even if Americans didn’t grok the connection between the war and the gas-price spike, the latter would still have hurt Trump politically, and it would still be a knock-on effect of the former.

It’s not just prices at the pump that have gone up because of the war. Groceries and other consumer goods travel across this vast land on tractor-trailers that run on diesel and get a lot fewer miles per gallon than even your Uncle Larry’s F-350. Diesel prices have smashed records and now sit at around $6.50, up from $3.76 before the war.

No wonder truckers are furious, prompting rumors of an imminent strike.

And no wonder the Iran War has contributed to general inflation in America. Anyone who has been reading the official economic reports knows the war is responsible for more than a third of recent inflation.

Before the war, inflation was trending down, only a couple ticks away from the Federal Reserve’s target of 2 percent. It seems likely that Trump, if he hadn’t started his dumb war in the Middle East, would have garnered praise for presiding over declining inflation and that the Fed would have cut interest rates, juicing economic growth. Instead, inflation now sits at 3.4 percent.

(As an aside, this weekend I traveled to Istanbul, where many Middle Easterners of various nationalities complained to me that Americans only oppose the war because of the gas prices. That’s simply not true. The war has been unpopular since day one, when all that Americans knew was the American-Israeli strikes had killed Iranian leaders including the Supreme Leader Ali Khamenei.)

Shapiro, ever the neoconservative, insinuated in the quote above that the decline in Trump’s approval rating owes more to his tariffs than to his war. The data doesn’t back that up, as the conservative commentator and election analyst Ryan Girdusky noted on X in response to new survey data. “The most eye opening part of this poll is that Trump’s approval rating and the strength of the economy went up right after Liberation Day,” Girdusky said. “Fell slightly afterward and then plummeted at the start of the Iran War.”

Shapiro has unwittingly helped uncover another, subtler, way in which the Iran War has indirectly damaged Trump’s approval ratings and, by extension, the Republican Party brand. Shapiro recently went on Fox News to commiserate with the host Mark Levin—another Israel-Firster and warmonger—over all those dastardly antiwar conservatives blaming the Iran War for everything.

“Iran is a 4-percent issue with the American people,” Levin said, as Shapiro nodded in agreement. Levin was referring to Fox News polling that shows not many Americans name the Iran War as their top issue. “So, whatever happens in the midterms, it doesn’t appear that Iran’s going to drive anything one way or another.”

“I think that’s exactly right,” Shapiro replied.

Part of the problem with Levin’s analysis has already been covered above. In the Fox poll, a plurality of Americans—34 percent—named the cost of living as the most important issue, and the Iran War has made living costlier.

But the subtler problem is perhaps even more illuminating. Simply put, Americans believe Trump is too focused on foreign policy at the expense of the problem they really care about, which, in fact, his Iran War has exacerbated. This is a PR disaster for the Trump administration and the GOP. Americans don’t prioritize the war that has dominated the headlines and distracted the White House, even as Trump claims to have boldly prevented Iran from unleashing nuclear apocalypse.

It may be grotesque to find silver linings in this dumb and deadly war, but here’s one: Americans no longer buy the war narratives. That is certainly not, however, a silver lining for Republican candidates in this year’s election, no matter how cynically they try to distance themselves from the war. In fact, it’s a good bet they’ll do much worse than if Trump hadn’t launched this unnecessary war, despite what Shapiro and his ilk may tell you.

  •  

The fallacy of US delusions about Iran’s economic collapse

Press TV – September 30, 2026 

US Treasury Secretary Scott Bessent’s prediction that Iran’s economy would soon collapse underscores the depth of delusion within the current American leadership.

“Iran is absolutely not sanctionable,” Deputy Economy Minister Mortaza Zamanian said this week as Tehran worked to keep trade flowing despite Washington’s latest sanctions campaign.

Zamanian cited Iran’s extensive borders, established commercial routes and longstanding trading relationships, saying that they make it impossible for external pressure simply to switch off the country’s economy.

His remarks came as Washington intensified its economic terrorism against Iranian oil, shipping, aviation, finance, technology and foreign companies supporting those sectors.

US Treasury Secretary Scott Bessent said that Iran would probably make its final oil deliveries to China within two weeks, after which, he asserted, “they will have nothing.”

That prediction deserves comparison with history, because American administrations have imposed increasingly severe sanctions since 1979 while repeatedly expecting economic pressure eventually to produce decisive Iranian economic collapse.

The economy did not disappear under those campaigns; instead, Iran developed domestic industries, expanded regional commerce, strengthened Asian trade and accumulated extensive experience operating outside Western financial systems.

The proposition that an economy which has absorbed American sanctions for almost half a century will suddenly become economically empty within two weeks therefore indicates the depth of delusion among the current US leadership.

Iran enters the current confrontation with a large domestic market, substantial productive capacity, enormous energy resources and deeply established commercial relationships extending across neighboring countries and wider Eurasian markets.

The World Bank describes Iran as relatively diversified for an oil-exporting economy, with substantial manufacturing, agricultural and service activity supported by a large population and significant domestic consumption.

That domestic market sustains production across food, pharmaceuticals, construction materials, steel, petrochemicals, machinery and consumer goods, meaning Iranian production does not depend entirely upon continuous access to Western consumers.

Iran has also developed major industrial capabilities suited to its own resources and infrastructure, including steel, refining, petrochemicals, cement, power generation, construction, food processing and pharmaceutical manufacturing.

These capabilities have continued developing despite restrictions on Western investment and technology, demonstrating that Iranian industrial activity does not depend upon permanent participation by Western companies.

Iran’s prolonged exposure to sanctions has produced accumulated technical and commercial knowledge, giving Iranian companies decades of experience managing restricted supply chains and unreliable access to foreign suppliers.

When foreign manufacturers withdraw, Iranian companies have learned to redesign equipment, substitute components, develop domestic suppliers and cooperate with businesses from countries willing to maintain commercial relationships.

Academic research has documented this process, showing that sanctions can simultaneously restrict foreign technology while encouraging domestic technological development and adaptation within affected Iranian industrial sectors.

The resulting knowledge extends beyond individual companies, because engineers, technicians, procurement specialists and managers have accumulated practical experience managing shortages, substitution and alternative sourcing.

Iranian manufacturers therefore do not design procurement systems around the assumption that every international supplier will remain available indefinitely, making adaptation part of ordinary commercial planning.

Iran’s geography provides another economic advantage, because the country borders Turkey, Iraq, Armenia, Azerbaijan, Turkmenistan, Afghanistan and Pakistan while possessing coastlines reaching the Persian Gulf and the Sea of Oman.

Those borders connect Iranian commerce with the Caucasus, Central Asia, South Asia, the Persian Gulf, Turkey and Iraq, while transportation corridors also connect Iran with Russia and wider Eurasian markets.

Financial sanctions can make transactions more difficult, but they cannot physically relocate Iran or eliminate its access to neighboring markets, suppliers, transportation routes and established regional trading relationships.

Iran has consequently developed commercial links involving Iraq, Turkey, the United Arab Emirates, Afghanistan, Pakistan, the Caucasus, Central Asia and China through years of sustained economic interaction.

The World Bank has documented Iran’s increasing trade orientation toward neighboring countries and China as sanctions restricted conventional international relationships, making this regional pivot an established economic feature.

China adds another dimension because it combines enormous industrial capacity with sustained demand for Iranian energy while supplying machinery, manufactured products and industrial inputs required throughout Iran’s domestic economy.

The US-China Economic and Security Review Commission identifies China as Iran’s largest trading partner and estimates that China imported approximately 1.4 million barrels of Iranian crude daily during 2025.

Chinese independent refiners have continued purchasing Iranian crude through commercial arrangements designed to reduce their exposure to American financial restrictions and sanctions enforcement.

That relationship demonstrates why Iran does not require unrestricted access to every Western market when Chinese demand and extensive regional commerce provide alternative markets for Iranian commodities.

Iran’s energy resources provide enormous economic depth, with the World Bank ranking the country second globally in proven natural-gas reserves and fourth globally in proven crude-oil reserves.

Those resources provide export potential while also supplying abundant domestic energy and petrochemical feedstocks supporting manufacturing, electricity generation, transportation and numerous energy-intensive industrial activities.

Iran has consequently developed a substantial downstream economy converting hydrocarbons into refined products, petrochemicals and industrial inputs rather than depending exclusively upon crude-oil exports.

The World Bank has noted that sanctions encouraged additional processing of hydrocarbons into petrochemicals, illustrating how restrictions contributed to changes within Iran’s export structure.

Iran has also developed financial mechanisms outside conventional Western banking, including bilateral currency arrangements, exchange houses, barter, intermediary companies and indirect settlement channels supporting international commercial activity.

The World Bank has documented growing use of bilateral currency exchange, barter and indirect payment mechanisms as Iranian trade shifted increasingly toward neighboring countries and China.

These arrangements provide alternative methods for exchanging value when conventional dollar-based transactions become unavailable or prohibitively difficult.

Their existence helps explain why Washington increasingly targets third-country banks, intermediaries and commercial facilitators, because Iranian commerce extends through extensive international networks beyond domestic financial institutions.

Against this background, Bessent’s prediction assumes that eliminating a major source of oil revenue would effectively remove the broader economic foundations supporting Iran’s productive system and commercial institutions.

Iran’s economic structure is considerably broader, because oil exports represent one component of national activity alongside manufacturing, agriculture, services, domestic consumption and regional commerce.

The World Bank estimates that Iran’s economy contracted during the Iranian year ending March 2026, while simultaneously describing adaptation through changing trade patterns and alternative payment mechanisms.

Economic contraction, however, is fundamentally different from the disappearance of productive capacity, infrastructure, commercial institutions and domestic relationships sustaining millions of Iranian consumers and businesses.

American sanctions have repeatedly targeted Iranian banking, oil exports, investment, technology, shipping and foreign companies, yet Iran has retained its industrial base and redirected substantial trade toward neighboring countries.

Washington possesses powerful financial tools, but financial restrictions cannot physically eliminate Iran’s factories, oilfields, farms, engineers, consumers, ports, borders or commercial relationships accumulated over decades.

The central question is therefore whether American pressure can erase the productive, geographical, resource and commercial foundations Iran has accumulated across nearly half a century of economic adaptation.

Nothing in Iran’s economic history demonstrates that those foundations can disappear within two weeks, particularly while the country retains domestic production, regional markets, energy resources and established commercial relationships.

Iran therefore enters the present confrontation with domestic capabilities, energy resources, industrial capacity, geographic advantages and international relationships capable of keeping its economy operating despite intensified American terrorism.

  •  

The legacy of US sanctions, war, and occupation in Iraq

By Hala Farhat | Al Mayadeen | September 30, 2026

Iraq’s government has declared September 30 the final date for ending the US-led coalition’s military mission. Prime Minister Ali al-Zaidi’s office says October 1 will find the country “free of any foreign military presence,” closing a deployment that once reached about 170,000 US troops.

But withdrawal leaves intact much of the damage inflicted by the invasion and the 13 years of sanctions that preceded it, along with the financial arrangements through which Washington continues to exert influence.

The US left Iraq’s productive economy devastated, its institutions dismantled and reshaped, and its workforce left increasingly dependent on a state funded by oil. Access to that income remains vulnerable to US pressure.

The question after the troops leave is how much control Iraq will have over the economy they leave behind.

Thirteen years of sanctions

The erosion of Iraq’s economy began long before March 2003. The UN Security Council imposed sweeping sanctions after Saddam Hussein’s regime invaded Kuwait in 1990. Drawing on internal UN records, Joy Gordon’s Invisible War describes one of the most comprehensive and devastating sanctions regimes ever imposed.

The embargo quickly collapsed incomes. Reconstructed World Bank estimates showed GDP per capita collapsing to a third in a single year,  going from about $3,527 in 1990 to $1,255 in 1991.

Public employees who had earned $150 to $200 a month before sanctions were earning $3 to $5 by 1996, according to a 1997 assessment. By 2000, the International Committee of the Red Cross reported salaries as low as $2 a month and unemployment around 50 percent.

Factories, power stations, and water plants could not recover without imported equipment and spare parts. Yet any member of the sanctions committee could hold an entire contract indefinitely, even over a single disputed item. Gordon documents Washington’s use of the “dual-use” designation to restrict goods as basic as water pipes. By August 2002, the UN counted 2,058 contracts worth about $5.2 billion that had been placed on hold, including $745 million in oil industry equipment.

The restrictions also placed Iraq’s oil income beyond Baghdad’s direct control. Under the Oil-for-Food program, buyers paid into a UN-administered escrow account. After deductions for compensation, administration, and weapons inspections, the proceeds could finance only approved purchases. Iraq exported roughly $65 billion in oil under the program but could not use that money as ordinary budget revenue for wages, maintenance, or local services.

The collapse pushed skilled workers out of their professions. A UN humanitarian survey of 1,157 degree holders employed by aid organizations found 725 in general-service or menial jobs, including doctors, engineers, and scientists working as drivers, clerks, and guards.

By the time US troops arrived, Iraq had endured years of falling wages, industrial decline, and lost expertise. The occupation’s first decisions deepened that damage.

Dismantling the state, contracting out reconstruction

On May 16, 2003, the occupation authority issued Order 1, barring senior Baath Party members from public employment and requiring the screening of senior staff in ministries, hospitals, and universities. A week later, Order 2 dissolved the Defense Ministry, army, Republican Guard, and intelligence bodies.

The International Center for Transitional Justice estimates that Order 2 alone left about 400,000 conscripts, officers, and officials without jobs. The World Bank counted more than 2 million unemployed Iraqis, nearly 30 percent of the labor force, around 2003–2004. Meanwhile, Iraq’s health minister estimated that roughly half the country’s prewar doctors had fled as kidnapping and assassination made their work increasingly dangerous.

The occupation then opened the weakened economy to foreign competition. Order 39 allowed wholly foreign-owned companies and guaranteed investors treatment no less favorable than Iraqi businesses, while excluding natural resource extraction. Other orders suspended tariffs, later replaced by a flat 5 percent levy, and capped income tax at 15 percent from 2004. The World Bank warned that rapid opening would cost jobs in a country whose private sector was too weak to employ displaced workers.

Reconstruction brought billions of dollars, but much of the spending flowed through foreign contractors. The United States spent more than $60 billion over roughly a decade, according to the Special Inspector General for Iraq Reconstruction (SIGIR). More than $25 billion went to training and equipping security forces after the occupation had dissolved Iraq’s existing military institutions.

SIGIR found that reconstruction began without adequate security, consultation with Iraqi ministries, or planning for long-term maintenance. Its final report estimated waste at $3 billion to $5 billion from the main reconstruction fund and as much as $8 billion overall. The largest early infrastructure contracts went mainly to US firms. A $1.8 billion award to Bechtel in January 2004 was open only to American bidders.

Iraq’s own money followed a similar path. UN Security Council Resolution 1483 established the Development Fund for Iraq to receive oil revenue, with the occupation authority directing spending until June 2004.

An Iraq Revenue Watch analysis of contracts paid from Iraqi funds found that US companies received 74 percent of their value. US and British companies together received 85 percent, while Iraqi firms received 2 percent. Audits found that 73 percent of the value of Development Fund contracts above $5 million had been awarded without competitive bidding.

Oversight was inadequate even to establish how some of that money had been used. A 2010 SIGIR audit found that the Defense Department had failed to establish required accounting controls for about $8.7 billion of the $9.1 billion it received from the fund. It could not document spending of about $2.6 billion.

The result was a reconstruction process that directed vast sums abroad while leaving Iraq with damaged services, limited productive capacity, and institutions struggling to rebuild.

An oil-funded system of patronage

With factories closed or looted and no private industry to replace them, the state became the place where Iraqis look for work. An assessment by the International Fund for Agricultural Development, using World Bank data, says public employment accounts for nearly all formal jobs and 40 percent of all jobs. Salaries and pensions took about 90 trillion dinars, roughly $69 billion, more than 40 percent of the 2024 budget, and the World Bank says another half a million government jobs were added during the spending expansion that preceded 2025.

The private sector has not filled the gap. Estimates put imports at more than 90 percent of the goods in Iraqi shops, while manufacturing makes up only around 2 percent of GDP. The World Bank says nearly 29 percent of the population is aged 15 to 29, and that this large group is entering the labor market amid limited job creation, a preference for public-sector work, and a private sector too small to absorb them. Youth unemployment is about 32 percent, and only around 11 percent of women take part in the labor force.

The IMF’s 2025 assessment describes the same pattern, citing high unemployment, an excessive state footprint, corruption, a weak banking system, and an inefficient electricity sector, and it called the wage trajectory fiscally unsustainable. Analysts describe a cycle in which secure public wages raise the pay that educated workers expect, private firms struggle with unreliable power and weak finance, and young graduates keep turning to the state for jobs, which raises the demand for more public hiring.

Oil pays for all of it. The World Bank estimates that oil supplied about 88 percent of government revenue and 91 percent of exports in 2025.

The financial levers Washington keeps

Iraq’s oil income has passed through outside hands since 1996, first a UN escrow, then the occupation authority’s fund, and now the New York Fed.

The Development Fund’s accounts were opened at the Federal Reserve Bank of New York, where Iraqi oil revenue still flows. Buyers pay dollars into a Ministry of Finance account, and the Central Bank of Iraq converts part of the income into dinars for government spending. US jurisdiction over dollar clearing, correspondent banking, and physical cash shipments gives Washington substantial influence over Iraq’s access to its money.

In January 2020, after Iraq’s parliament called for foreign troops to leave, the Trump administration threatened to block access to the account. Iraqi officials said it then held about $35 billion and warned that losing access would disrupt salary payments and the exchange rate.

US restrictions introduced in November 2022 forced banks seeking dollars for international transfers to disclose the final beneficiaries and purposes of transactions through an electronic platform, with requests screened by the New York Fed. US and Iraqi accounts linked the measures to concerns about transfers to sanctioned Iranian actors.

Consequently, more than 80 percent of daily wire requests were initially blocked or returned. Transfers fell from $224.4 million on October 17, 2022, to $22.9 million on January 17, 2023. Demand shifted to the parallel market, where the dinar traded at about 1,588 to the dollar in February against a newly set official rate of 1,300. In a country dependent on imported food and consumer goods, restricted dollar access raised costs for ordinary households.

In April 2026, Washington applied pressure through physical cash, halting a shipment of about $500 million and suspending parts of security cooperation. Iraqi officials said the halt affected banknotes used for travel, medical treatment, education, and retail exchange, while electronic transfers for imports continued. Some shipments resumed in July. On September 26, Baghdad announced that Washington had agreed to continue them.

US sanctions have also reshaped access to Iraq’s oil fields. Russia’s Lukoil left West Qurna 2 after sanctions, and Chevron signed agreements to take over its development. During al-Zaidi’s July visit to Washington, Iraq signed dozens of agreements with companies including ExxonMobil, KBR, Halliburton, and Shell. US Energy Secretary Chris Wright cited more than $60 billion in commercial agreements, while al-Zaidi told The National that US companies would receive top priority. According to the Atlantic Council, Donald Trump framed the deals as American oil companies taking the place of US forces.

As US forces prepare to leave Iraq, they leave behind a trail of devastation. Decades of sanctions and occupation have weakened its productive economy, dismantled state institutions, and left livelihoods dependent on an oil-funded system of patronage. The consequences will endure long after the troops depart.

Washington retains substantial power over Iraq through its influence over dollar access and the financial channels that sustain the state. The withdrawal ends a military mission, while leaving Baghdad to contend with both the damage of US intervention and the control Washington continues to exercise.

  •  
❌